

Behaviour..5 min read
The behaviour gap: fund return vs investor return
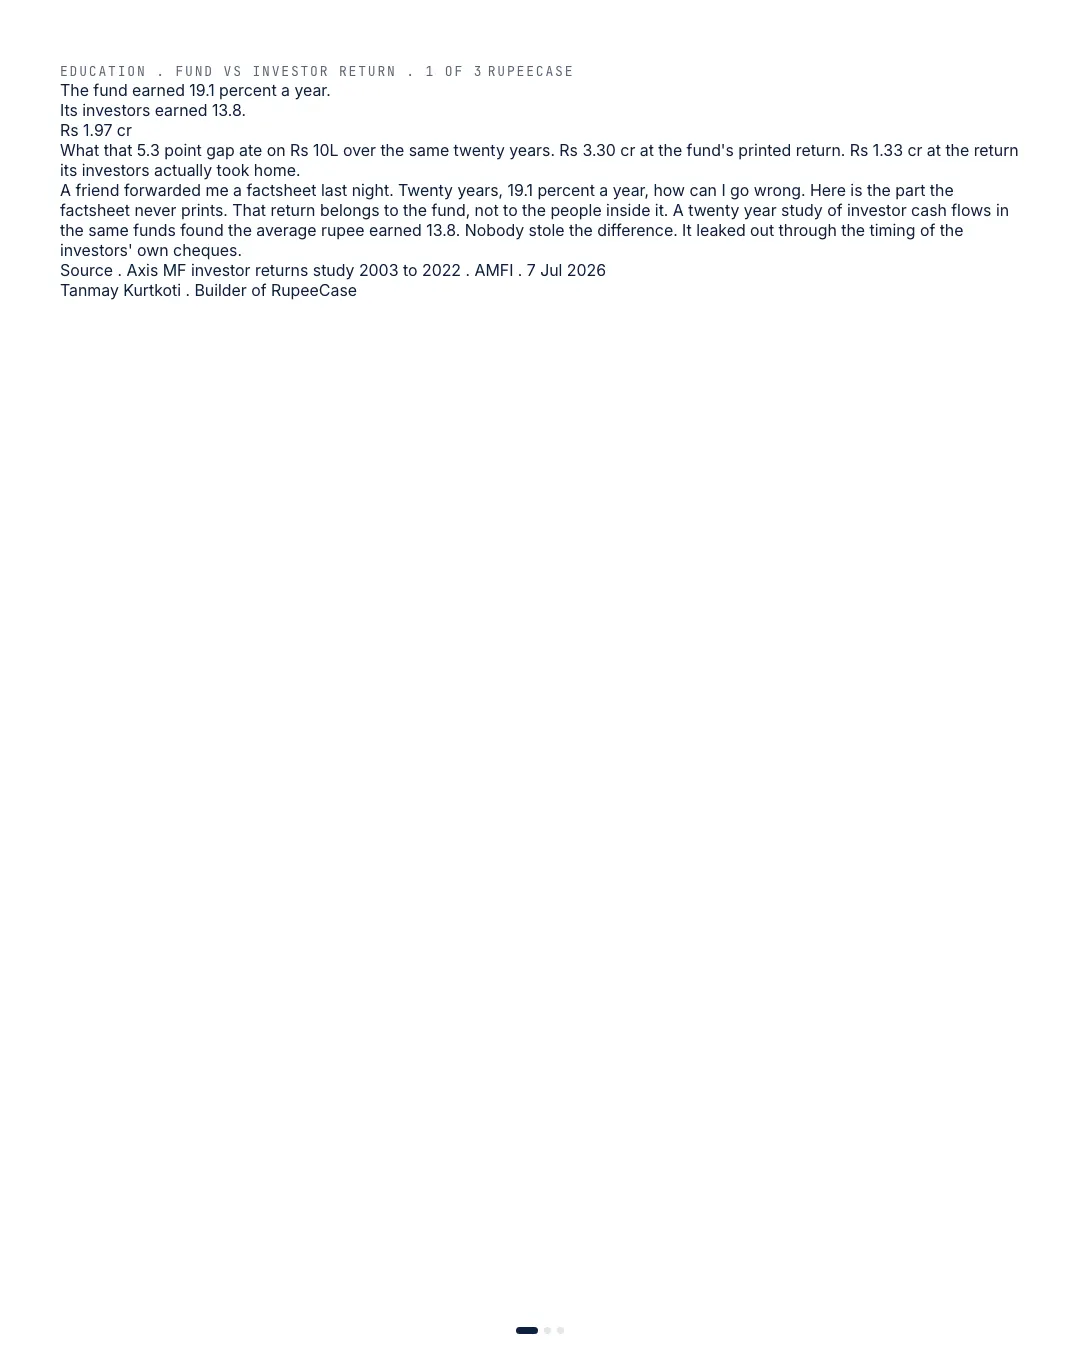
Indian equity funds returned 19.1 percent a year from 2003 to 2022 while the rupees investors actually put in earned 13.8, and SIP investors earned 15.2.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
A friend forwarded me a factsheet last night. Twenty years, 19.1 percent a year. His message under it: how can I go wrong.
Honest answer: the same way almost everyone in that fund went wrong. By being human about the timing.
There is a twenty year study of Indian equity funds (2003 to 2022) that put two numbers side by side. The funds' own NAV return: 19.1 percent a year. The return earned by the actual rupees investors put in and pulled out: 13.8. Same funds. Same two decades. A 5.3 point annual gap that went to nobody. No fee collected it, no taxman took it. Investors bought after the hot years, paused after the falls, and burned it.
On Rs 10L over those twenty years, that is Rs 3.30 cr versus Rs 1.33 cr. The most expensive thing most investors ever buy is their own timing, and it never shows up on a statement.
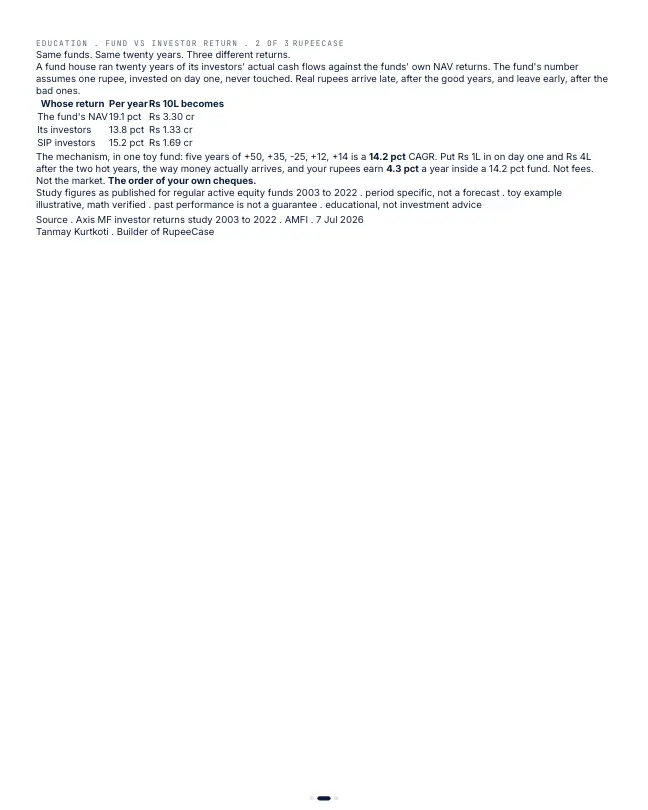
The mechanism is simple once you see whose return the factsheet even is. A CAGR times one rupee invested on day one and never touched. Real money arrives late. I built a toy fund to show a friend: five years of +50, +35, -25, +12, +14 is 14.2 percent a year. Put Rs 1L in at the start and Rs 4L after the two hot years, the way money actually shows up, and your rupees earn 4.3 percent inside a 14.2 percent fund. Industry studies measure this gap every year and finds investors leave roughly 15 percent of fund returns on the table. This is not an Indian quirk. It is a human one.
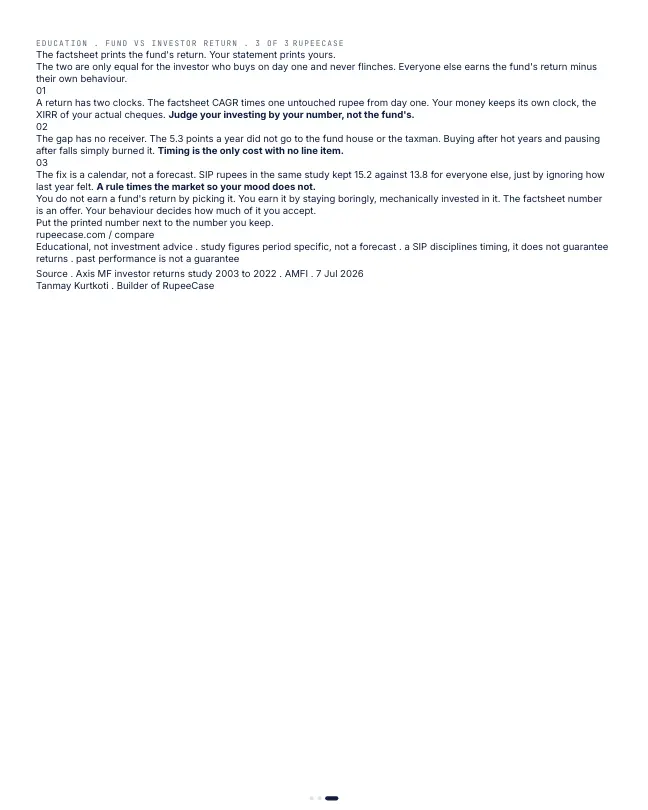
The quiet hero of the Indian study: SIP investors earned 15.2. Not because a SIP forecasts anything. Because a calendar cannot panic and cannot chase.
You do not earn a fund's return by picking it. You earn it by staying boringly invested in it
The toy fund, year by year
The toy fund in the opening is worth laying out, because the whole gap lives in the order of the years. Here are its five returns.
- Year 150%
- Year 235%
- Year 3, after Rs 4L arrives-25%
- Year 412%
- Year 514%
Worked example from the opening. 1.50 x 1.35 x 0.75 x 1.12 x 1.14 = 1.94, a CAGR of 14.2%.
I checked the opening's arithmetic. Rs 1 lakh grows to Rs 2,02,500 over the two hot years. Rs 4 lakh joins it, so Rs 6,02,500 meets the 25 percent fall and the two modest years after it. The pot ends at Rs 5,76,954. Rs 5 lakh went in. The internal rate of return on those dated flows is 4.3 percent a year, exactly as the opening says.
Same fund, three investors
Now add a third person: someone who puts Rs 1 lakh in at the start of every year, on a calendar, whatever happened last year. Five lakh in, like the late arriver, just spread evenly.
the fund's own return, one rupee from day one
Worked example
Rs 1 lakh every year on a calendar
Worked example, XIRR
Rs 1 lakh, then Rs 4 lakh after the hot years
Worked example, XIRR
The calendar investor also trails the fund, because in this sequence more of their money was in by the time the bad year came. That part is luck of the order. But they more than double the chaser's return on the same Rs 5 lakh, ending at Rs 6,60,630 against Rs 5,76,954. That is the opening's point about SIP investors in miniature. The calendar did not forecast anything. It just did not pile in after the best years.
Why the factsheet and your statement disagree
The two numbers are both correct. They answer different questions.
Time weighted, on the factsheet
- One rupee in on day one, never touched
- Measures the manager and the strategy
- Ignores when money came and went
Money weighted, your XIRR
- Every rupee in and out, on its date
- Measures the strategy plus your timing
- The only number your bank balance feels
MythIf the fund did 19.1 percent a year, my money in it did too.
FactThe fund's figure follows one untouched rupee. In the study quoted above, the rupees investors actually put in earned 13.8 percent over the same twenty years.
A practical check: take your own statement for any fund, list every purchase and redemption with its date, add today's value as a final inflow, and run an XIRR. Then put it next to the fund's return over the same period. The XIRR calculator does this with dated rows.
The calendar is now the main buyer
The SIP habit the opening credits has kept growing. AMFI's monthly data for the current financial year shows contributions rising every month after May, with the number of contributing accounts crossing 10 crore in Aug 2026.
AMFI reported Rs 31,115 crore of SIP contributions in Apr 2026 and Rs 32,297 crore in Aug 2026, from 1,001.79 lakh contributing accounts. That money arrives on a date, not on a feeling, which is the behaviour the 15.2 percent rewarded.
The free Learn module on performance measurement explains time weighted and money weighted returns, XIRR and how to compare a portfolio with its benchmark fairly. Two related posts look at the same gap from other sides: pausing a SIP in a downturn and missing the best days.
Questions readers ask
Why is my mutual fund return lower than the fund's published return?
The published return is time weighted: it follows one rupee invested at the start and never moved. Your return is money weighted and depends on when you added or withdrew money. Money that arrives after strong years and meets a fall earns less than the fund, as the toy fund's 4.3 percent against 14.2 percent shows.
What is the behaviour gap in investing?
It is the difference between a fund's return and the return its investors actually earn, caused by the timing of their purchases and sales. The Indian study quoted in the opening found 19.1 percent for funds against 13.8 percent for investors over 2003 to 2022.
How do I calculate my actual return on a mutual fund?
List every purchase and redemption with its date, add the current value as the final entry, and compute an XIRR. That gives a money weighted annual return you can compare with the fund's return over the same dates.
The cards
3 cards. Swipe, or tap to open.
Reading path
Stop 8 of 8 on What a return number hides
Related
- Pausing a SIP in a downturn is the most expensive instinctOn identical money and the same exit, the investor who kept buying through a 40 percent fall ended with 329 more units and Rs 39,471 more than the one who paused.Behaviour . . 5 min
- Missing the best daysSitting out the ten best days in twenty years cuts Rs 96 lakh to Rs 47 lakh on Rs 10 lakh at 12 percent, and those days cluster inside the worst weeks.Behaviour . . 5 min
- Ten days that matteredRs 10 lakh in the Nifty 50 TRI from July 1999 grew to Rs 2.84 crore, or Rs 96 lakh without the 15 best days, seven of which sat within two weeks of the ten worst.Behaviour . . 10 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.