

Behaviour..5 min read
Impact cost: zero brokerage was never zero cost
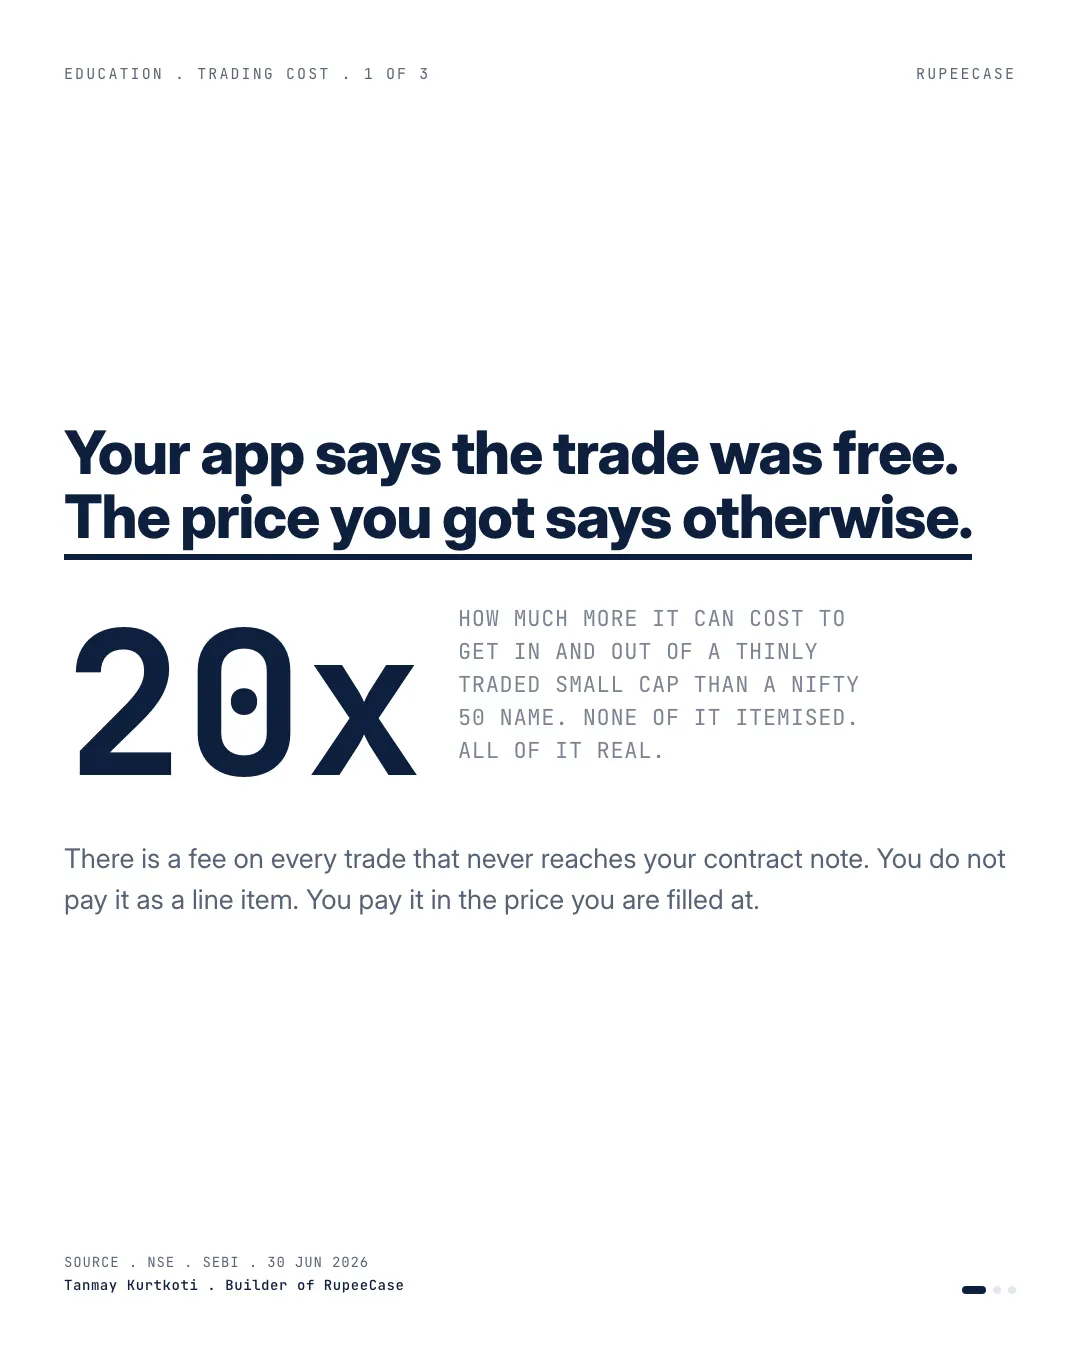
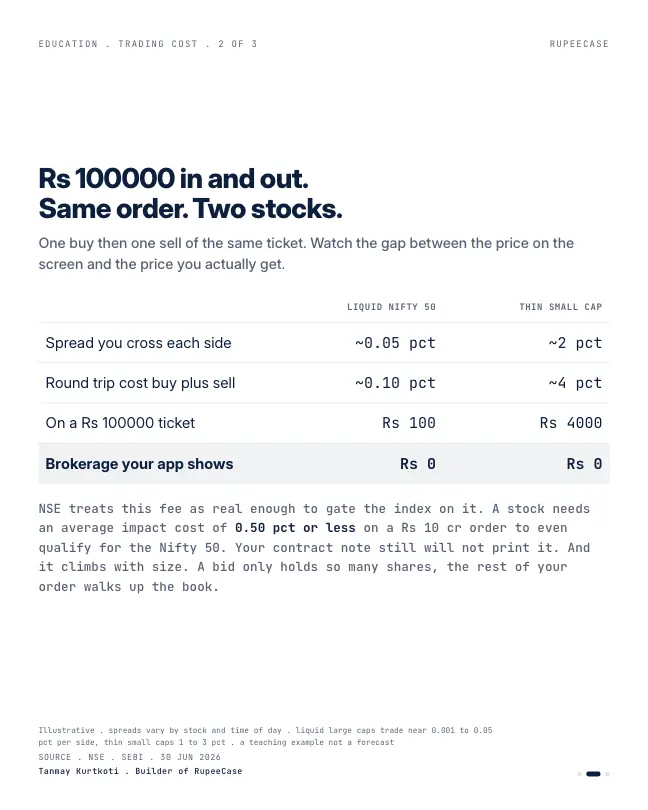
A Rs 1 lakh round trip costs about Rs 100 of spread on a liquid Nifty name and about Rs 4,000 on a thin small cap, and neither appears on the contract note.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
A friend showed me his trading app last week, genuinely pleased that it charges zero brokerage. Then he forwarded the fill prices on a small cap he had bought and sold the same week. He had paid a real fee on that round trip. It was nowhere on the contract note, because it was never going to be.
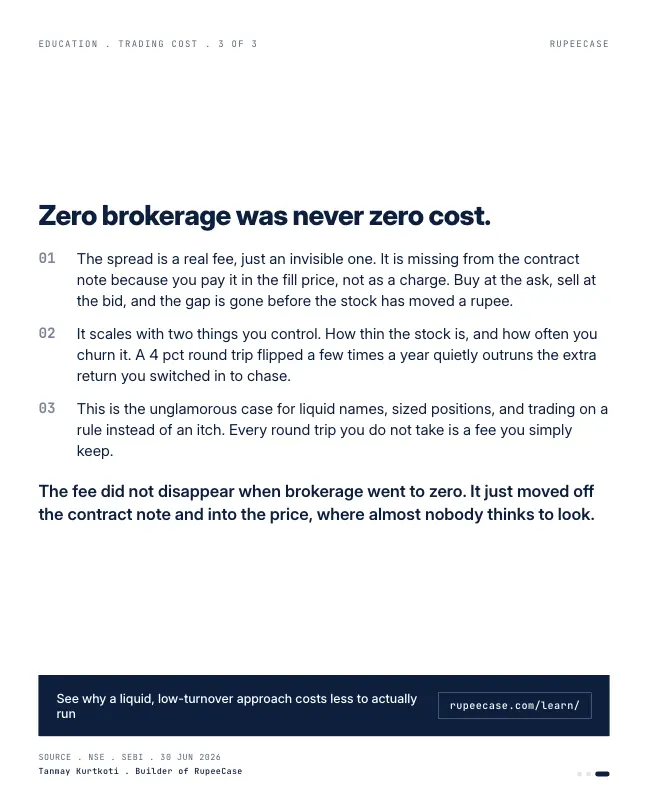
The fee is the spread. Every stock has two prices at once, the price you can buy at and the lower price you can sell at, and the gap between them is yours to pay. You buy at the ask, you sell at the bid, and that gap is gone before the stock has moved a rupee in either direction. Nobody charges it to you. You simply receive a slightly worse price than the one glowing on the screen.
On a liquid Nifty 50 name the gap is tiny, often a tenth of a percent for a full round trip. On a thinly traded small cap it can run to four percent. Same Rs 1,00,000 ticket, in and out: roughly Rs 100 on the liquid stock, roughly Rs 4,000 on the thin one. Both apps show the identical brokerage. Zero. The cost that actually mattered, twenty times larger on one than the other, was sitting in the price the whole time.
Here is the part that stays with me. The exchange takes this fee more seriously than most of us do. A stock has to trade at an impact cost of 0.50 percent or less to even make it into the Nifty 50. NSE measures it, publishes it, and uses it as an entrance exam. Your statement still will not say a word about it.
The good news is the cost scales with two things you control. How thin the stock is, and how often you trade it. Liquid names, sized positions, and a rule that moves the portfolio instead of a hand that itches to. Every round trip you do not take is a fee you simply keep.
Zero brokerage was never zero cost. The fee just moved off the receipt and into the price
What impact cost actually measures
The spread is the cost of the smallest possible trade. Impact cost is the cost of your trade, at your size. NSE defines it as the percentage gap between the price you would actually pay for a given order, walking up the order book, and the ideal price, the midpoint of the best bid and the best ask.
The Nifty 50 entrance test in the opening is precise. For a stock to be eligible, NSE checks that buying a Rs 10 crore basket of the index would have had an average impact cost of 0.50 percent or less in at least 90 percent of observations over the previous six months. That is the exchange telling you which stocks are cheap to trade in size, and the list is public.
Walk up the order book yourself
Here is a worked example with two made up stocks, both with a midpoint of Rs 100. You want 1,000 shares of each, about Rs 1 lakh.
Company A is liquid. Its best ask is Rs 100.05, with 50,000 shares offered there. Your whole order fills at Rs 100.05. Impact cost: 0.05 percent.
Company B is thin. Its order book offers only a few hundred shares at each price, so your order has to take three levels.
- 200 shares at Rs 100.50Rs 20,100
- 300 shares at Rs 101.00Rs 30,300
- 500 shares at Rs 102.00Rs 51,000
Worked example, Company B, midpoint Rs 100. Bar length is the number of shares filled at each level.
Add it up: 1,000 shares for Rs 1,01,400, an average of Rs 101.40. Against the midpoint of Rs 100, that is an impact cost of 1.40 percent on the way in. Selling hits the bids the same way on the way out, so a round trip can easily cost close to 3 percent, in line with the opening. Company A's round trip is about 0.1 percent. Same ticket, same zero brokerage, about Rs 2,800 against Rs 100.
Price your own habit
The second lever in the opening is how often you trade. Impact cost is paid on every round trip, so a thin stock traded often is the most expensive combination there is.
One round trip a month on a thin small cap, with a Rs 1 lakh ticket, costs about Rs 33,600 a year in price alone, a third of the capital. On a liquid name at 0.1 percent the same habit costs about Rs 1,200. The statutory charges come on top of both: about Rs 221 per lakh round trip at Oct 2026 rates, as worked out in the turnover tax post.
MythWith zero brokerage, trading more often costs me nothing.
FactEach round trip pays the spread and impact cost in the price. In the worked example that is Rs 100 a lakh on a liquid stock and about Rs 2,800 on a thin one, every time.
Three habits that keep the fee small
- Look at the depthCheck how many shares sit at the best five prices before you size the order.
- Use limit ordersA market order on a thin stock takes whatever the book offers.
- Trade lessA rule that rebalances on a schedule pays the fee a few times a year, not every week.
The deeper you go down the size ladder, the more these three habits matter, because the order book thins out faster than the price chart shows.
The free Learn module on the real cost of trading walks through spreads, impact cost, NSE's published impact cost data and the full Indian charge stack. The trade cost calculator itemises the statutory part of any order.
Questions readers ask
What is impact cost in the stock market?
Impact cost is the percentage by which the price you actually pay for an order of a given size differs from the ideal price, the midpoint of the best bid and ask. It rises when the order book is thin, because a larger order has to fill at several worse prices.
What impact cost does a stock need to be in the Nifty 50?
NSE requires an average impact cost of 0.50 percent or less, for at least 90 percent of observations over the previous six months, for a Rs 10 crore basket of the index. Only stocks that also trade in NSE's F&O segment are considered.
Is zero brokerage really free?
No. Brokerage is one of several costs. Every trade also pays the bid ask spread and impact cost in the price, plus STT, stamp duty and exchange charges, which together are about Rs 221 per Rs 1 lakh round trip before brokerage at Oct 2026 rates.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
- GuideHow to choose a broker for systematic or algo investing in IndiaRegistration, SEBI's algo rules, basket orders, charges per rebalance and safety.
- Free module 8.1Why Investors Lose, Introduction to Behavioural Finance11 min read
- StrategyAllcap strategyNifty Total Market, 50 stocks, every 2 weeks
- CalculatorFee drag over 20 yearsFree, with the formula and a worked example
Related
- Why your sell is not cash yetIndia settles at T plus one trading day, so a Friday sale lands on Monday and a sale before a long weekend can take five calendar days to become spendable.Behaviour . . 5 min
- The IPO pop is not the businessIn 2025, 65 of 100 mainboard listings opened above issue price and 59 of 100 traded below their listing by December, because the grey market prices the first hour, not the first year.Behaviour . . 6 min
- The day the market did not let you sellA 10 percent index move halts the whole market, and a lower circuit means the bids have vanished, which is why position size and not the exit plan is the real protection.Behaviour . . 5 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.