

Company numbers..5 min read
One company, two sets of books
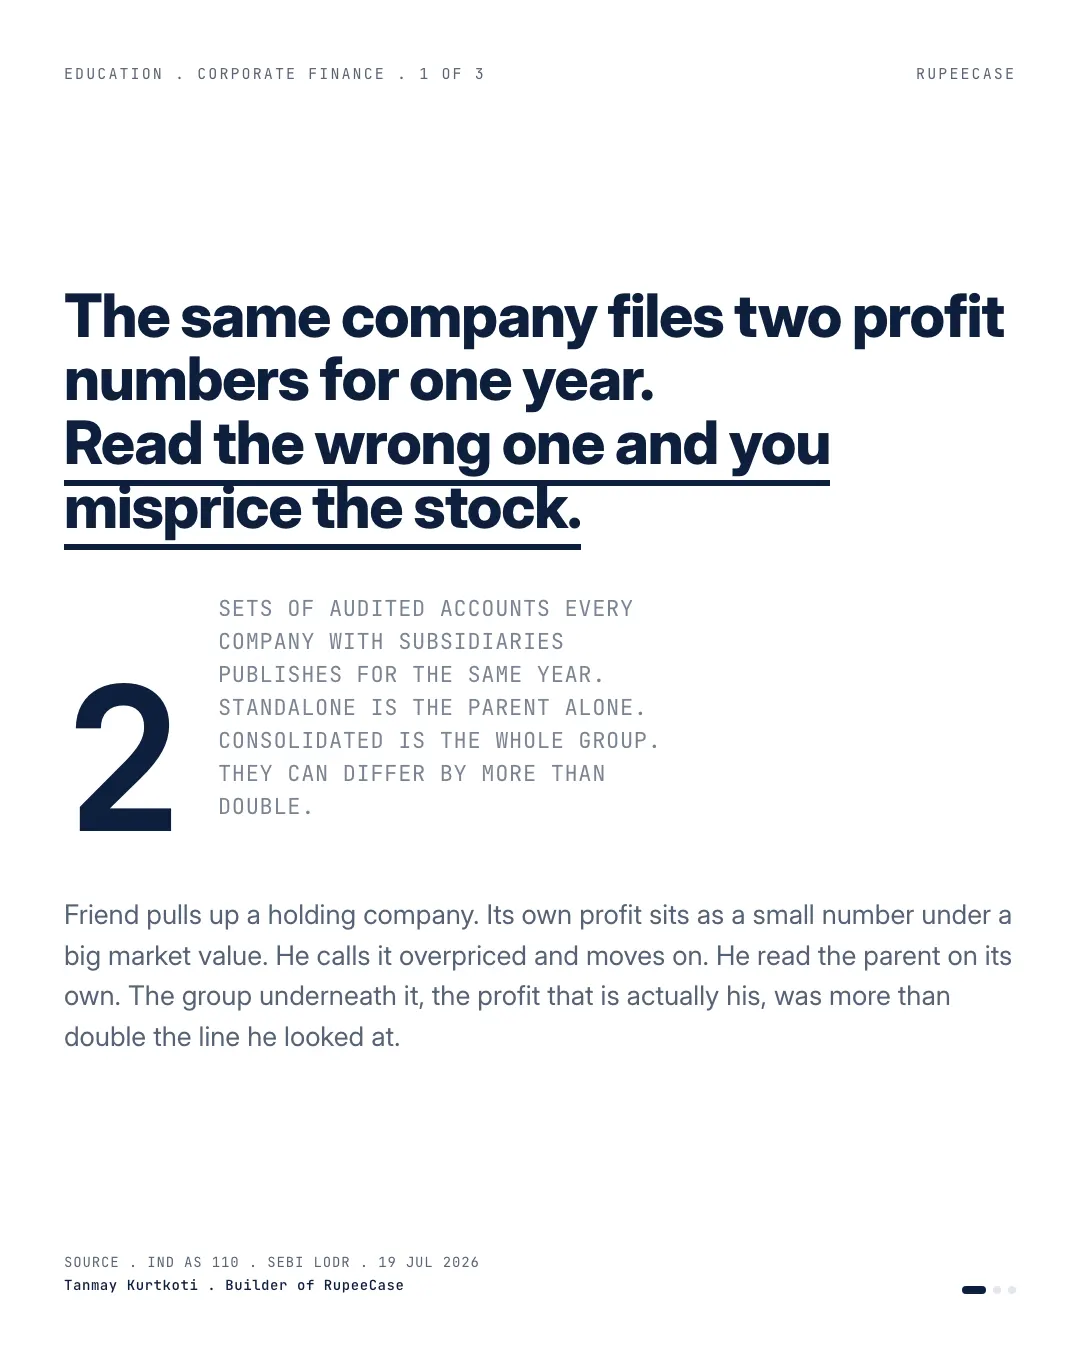
A parent's standalone profit of Rs 45 crore, consolidated Rs 140 crore and attributable Rs 100 crore give P/Es of 33, 11 and 15 on the same market value.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
A friend pulled up a holding company last week, glanced at its profit, saw a small number sitting under a big market value, and decided it was overpriced. He moved on before his coffee was cold.
He had read the wrong set of books.
Here is the thing nobody really tells you when you start reading company accounts. Any company that owns subsidiaries files two of them for the very same year. The standalone statement is the parent on its own. The consolidated statement is the whole group, stitched together line by line. Both are audited. Both are true. And they can disagree by more than double.
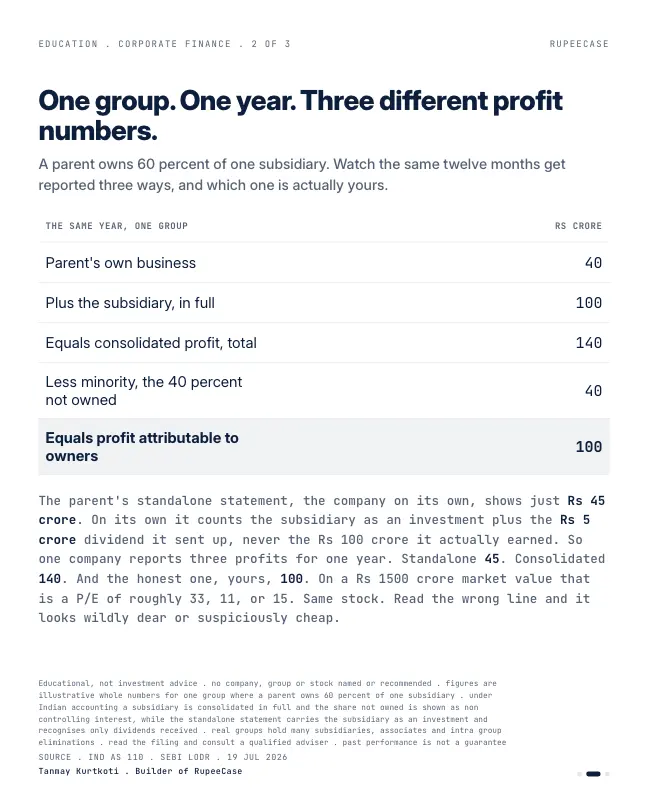
Take a parent that owns 60 percent of one subsidiary. Its own business earns Rs 40 crore that year. Consolidation adds the subsidiary in full, so consolidated profit reads Rs 140 crore. Then part of it gets handed back, because 40 percent of the subsidiary belongs to someone else, and the line that is actually yours, profit attributable to owners, is Rs 100 crore. Meanwhile the standalone statement, the parent alone, shows just Rs 45 crore, because on its own the parent only sees the subsidiary as an investment and the small dividend it sends up.
One company. One year. Three different profit numbers. On a Rs 1,500 crore market value that is a P/E of 33, or 11, or 15, depending purely on which line you read.
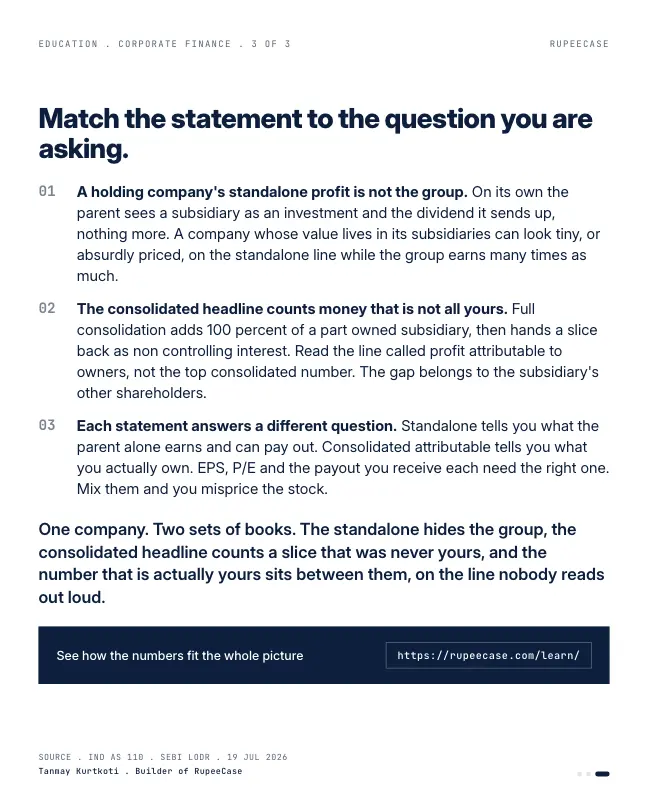
That is the whole trap. Read the standalone and a holding company looks tiny or wildly expensive. Read the consolidated headline and you are counting profit that belongs to the subsidiary's other shareholders. The honest number sits between the two, on the line nobody reads out loud.
I have watched sharp people misprice a stock by two times just by quoting the wrong statement. It is not an advanced idea. It is knowing which of the two books answers your question.
Draw the group first
Before reading any number, draw the group on the back of an envelope. Here it is two boxes. Company A, the listed parent, runs its own business and owns 60 percent of Company B. Other investors own the remaining 40 percent of Company B. Company B earns Rs 100 crore and pays out a small dividend, of which Rs 5 crore reaches Company A.
Three lines, built step by step
The standalone statement treats Company B as a shareholding, nothing more. Company A's own Rs 40 crore plus the Rs 5 crore of dividend it received gives Rs 45 crore.
The consolidated statement, prepared under Ind AS 110, adds Company B line by line as if Company A owned all of it, because Company A controls it. Revenue, costs, debt and cash of both companies are added together. Profit for the group is Rs 40 crore plus Rs 100 crore, Rs 140 crore. The dividend disappears in consolidation, since it is money moving inside the group.
Then the statement splits that Rs 140 crore in two. Forty percent of Company B's profit, Rs 40 crore, belongs to the other shareholders and is shown as profit attributable to non controlling interests. What is left, Rs 100 crore, is profit attributable to the owners of Company A. That is the only figure that describes what Company A's own shareholders earned from the whole group.
- Standalone profit45
- Consolidated profit140
- Attributable to owners100
Rs crore. Worked example, not a company.
Put each over the Rs 1,500 crore market value and the opening's three P/Es fall out: 1,500 divided by 45 is 33, by 140 is about 11, by 100 is 15. Change the stake and watch how far apart they can drift.
Which book answers which question
Profit is not the only line that changes. The consolidated balance sheet carries all of Company B's debt, even though Company A owns only 60 percent of it, and it carries goodwill from past acquisitions that never shows in the standalone. A parent with little debt on its own can sit on top of a heavily borrowed group, and a parent that has guaranteed a subsidiary's loans is exposed to that debt either way.
- What does the group earn for me?Consolidated profit attributable to owners. Use it for P/E and earnings growth.
- How much does the group owe?Consolidated borrowings, then check the notes for guarantees the parent has given.
- What can the parent pay out on its own?Standalone cash and reserves, since dividends are paid from the parent's own accounts.
- Where does the profit come from?The segment note and the list of subsidiaries with their share of profit.
Since the year beginning 1 April 2019, SEBI's listing rules have required listed companies with subsidiaries to file consolidated results every quarter on NSE and BSE, not only at year end. So both books are there every three months, side by side in the same filing.
MythThe consolidated profit headline is the profit that belongs to shareholders.
FactConsolidated profit includes the share of subsidiaries owned by others. The figure that belongs to the listed company's shareholders is the line marked attributable to owners of the parent.
The free Learn module on reading annual reports shows where these notes sit and the order I read them in, with a quiz at the end. The post on goodwill explains the asset that appears only in the consolidated balance sheet, and goodwill impairment the day it comes off.
Questions readers ask
What is the difference between standalone and consolidated results?
Standalone results cover only the listed company itself and treat its subsidiaries as investments, counting just the dividends they pay. Consolidated results add every subsidiary line by line, as one group. For a holding company the two can differ by several times.
Which profit should I use to calculate P/E?
For a company with subsidiaries, the usual choice is consolidated profit attributable to owners of the parent, because it is the group's earnings that belong to the listed company's shareholders. In the example, that is Rs 100 crore and a P/E of 15, against 33 on standalone and 11 on the consolidated headline.
What is non controlling interest in a profit and loss statement?
It is the part of a subsidiary's profit that belongs to its other shareholders. If a parent owns 60 percent of a subsidiary that earns Rs 100 crore, Rs 40 crore is profit attributable to non controlling interests and is taken out before arriving at the owners' share.
The cards
3 cards. Swipe, or tap to open.
Related
- Goodwill: the asset that exists because they overpaidA Rs 400 crore goodwill write down can turn a 500 crore profit year into 100 without a rupee of cash moving, as Tata Steel's Corus impairment showed.Company numbers . . 5 min
- Goodwill impairment: the day the future said noPaying Rs 1,000 crore for Rs 400 crore of real assets parks Rs 600 crore of optimism as an asset, and the write down only catches the books up to cash that left years earlier.Company numbers . . 5 min
- Promoter pledging: the page nobody readsA stock down 40 percent in two sessions on no news is usually a pledge unwinding, as a 30 percent fall takes lender cover from 2.0x to 1.4x and triggers forced selling.Company numbers . . 6 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.