

Company numbers..6 min read
Promoter pledging: the page nobody reads
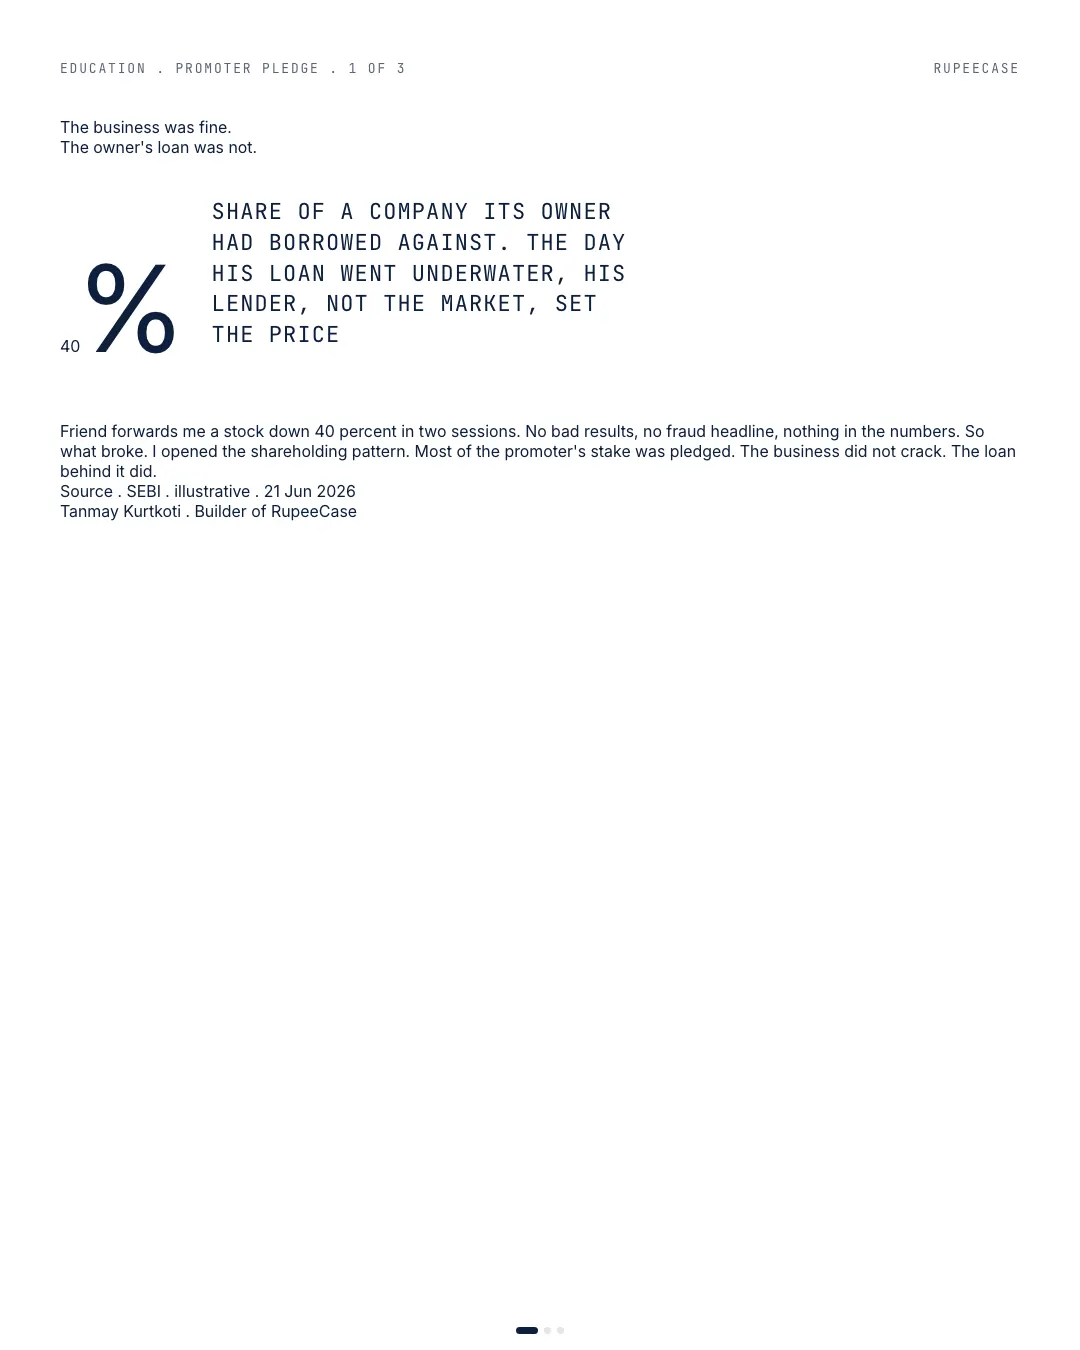
A stock down 40 percent in two sessions on no news is usually a pledge unwinding, as a 30 percent fall takes lender cover from 2.0x to 1.4x and triggers forced selling.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
A friend forwarded me a stock last week, down about 40 percent in two sessions, and asked what I thought had broken.
I checked the results first. Nothing. No profit warning, no fraud headline, no missed quarter. The business was doing roughly what it did the month before.
So I opened the page almost nobody reads. The shareholding pattern. There it was. Most of the promoter's stake was pledged.
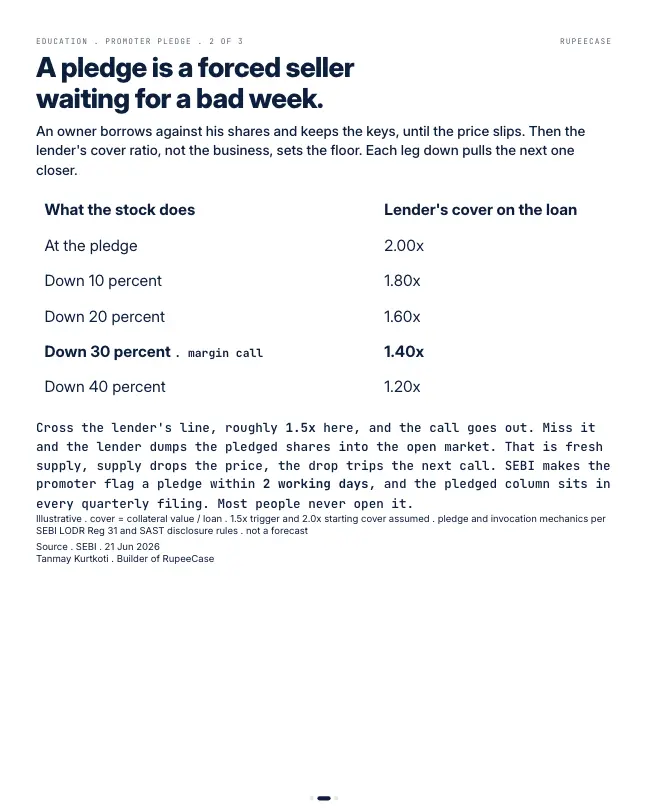
Here is what a pledge actually is. The owner borrows money against his own shares and keeps voting them, keeps running the company, keeps the keys. The lender holds the shares as collateral and asks for one thing, that the collateral stay worth comfortably more than the loan. Lend against two times cover and everyone sleeps fine.
Then the price slips. A 30 percent fall on that example takes the cover from 2.0x to 1.4x. The lender issues a margin call. If the promoter cannot put up cash or pledge more shares, the lender does the only thing the contract allows. It sells the pledged shares into the open market.
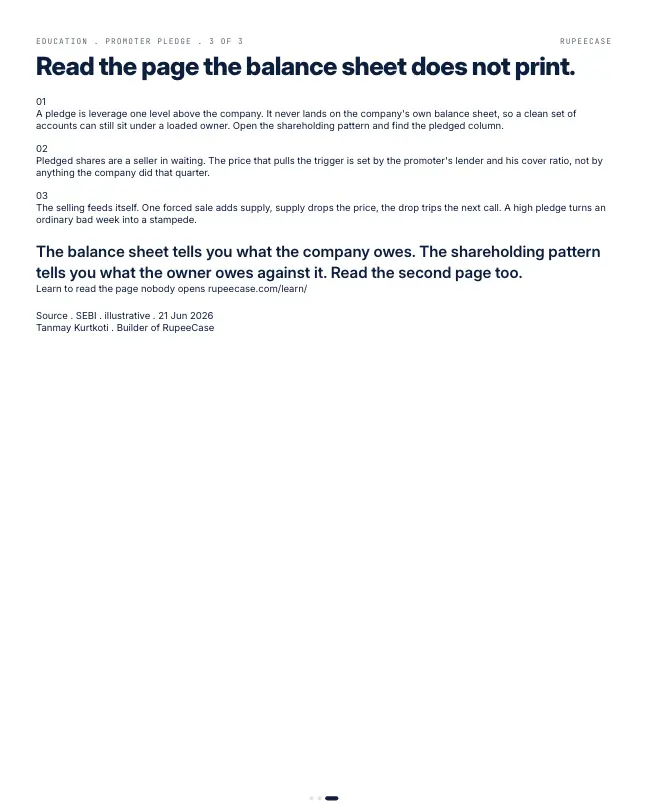
That is what turns a bad week into a stampede. The forced selling is fresh supply. Supply pushes the price down further. The lower price trips the next margin call, maybe at another lender, maybe at another promoter in the same sector. None of it is the market reaching a verdict on the business. It is a loan unwinding in public.
SEBI makes promoters flag a pledge within two working days once it crosses a threshold, and the pledged share count sits in every quarterly filing. The information is free and on time. It just lives on a page most people never turn to.
The balance sheet tells you what the company owes. The shareholding pattern tells you what the owner owes against it. Read the second page too.
Put rupees on the pledge
Take a promoter who owns 5 crore shares of Company A, priced at Rs 200. He pledges 3 crore of them, worth Rs 600 crore, and borrows Rs 300 crore. Cover is Rs 600 crore over Rs 300 crore, 2.0x. Say the loan agreement asks for top up below 1.5x.
The price falls 30 percent to Rs 140. The pledged shares are now worth Rs 420 crore against the same Rs 300 crore loan. Cover is 1.4x, under the 1.5x line. The lender asks for the cover to be restored to 2.0x. To do that, the promoter must either pledge about 1.29 crore more shares, or repay about Rs 90 crore. If he can do neither, the lender sells.
How much does the lender have to sell? Every share sold at Rs 140 cuts both the loan and the collateral by Rs 140. To get back to 2.0x it has to sell about 1.29 crore shares, roughly Rs 180 crore of stock, into a market that did not ask for it. If Company A trades Rs 30 crore of shares on a normal day, that is six days of volume arriving at once.
The spiral, one step at a time
The arithmetic is the easy part. The damage comes from the loop. A sale lowers the price, the lower price lowers the cover on every other pledge in the same stock, and each of those can trip its own call.
- The price slipsFor any reason: a weak market, a sector worry, a large seller.
- Cover fallsRs 600 crore of collateral becomes Rs 420 crore. The loan stays Rs 300 crore.
- Margin callThe promoter must add shares or cash. Each extra pledged share raises the stake at risk.
- Forced saleIf he cannot, the lender sells the pledged shares in the open market.
- New supplyThe sale pushes the price lower, and the next lender's cover falls in turn.
Cover falls in a straight line with the price, but the room left shrinks fast. At a 50 percent fall the collateral is worth exactly the loan, and the lender's cushion is gone.
- No fall2.0x
- Price down 10%1.8x
- Price down 20%1.6x
- Price down 30%1.4x
- Price down 40%1.2x
- Price down 50%1.0x
Collateral value over loan, Rs 300 crore lent against Rs 600 crore of shares. Worked example, not a company.
A 30 percent fall also needs a 43 percent rise just to get back to Rs 200. The drawdown recovery calculator in the free Learn tools shows that asymmetry for any fall.
What SEBI requires, and where to read it
The disclosure rules are clear and the data is public. SEBI's FAQ on the Takeover Regulations (SAST, 2011) sets them out.
- A promoter must disclose shares encumbered, and any invocation or release of a pledge, to the company and every stock exchange where it is listed, within 7 working days.
- From 1 October 2019, when the combined pledge of the promoter group reaches 50 percent of its holding or 20 percent of the company's share capital, the promoter must also disclose detailed reasons within 2 working days. That is the threshold the opening refers to.
- The promoter also declares every year that there is no encumbrance other than those already disclosed.
Separately, every listed company files its shareholding pattern each quarter, within 21 days of the quarter's end, under Regulation 31 of the SEBI Listing Regulations, 2015. It shows promoter shares pledged or otherwise encumbered, as a number and as a percentage. Both filings are on the NSE and BSE websites under the company's corporate filings.
MythA stock that falls 40 percent in two sessions must have bad news in the business.
FactA forced sale of pledged shares needs no news at all. It needs only a price fall large enough to break the lender's cover, and every sale lowers the cover on the next pledge.
When I look at a promoter, a high pledge tells me two things. The owner's personal finances are tied to the share price, and his decisions may follow that pressure rather than the business. The free Learn module on management quality puts pledging next to related party deals and capital allocation as signals of how owners treat minority shareholders. The post on off balance sheet debt covers the company side of the same question.
Questions readers ask
What happens when a promoter's pledged shares are invoked?
The lender sells the pledged shares in the market to recover its loan, usually after a margin call that the promoter could not meet with cash or more shares. The promoter's stake falls, and the sale adds supply that can push the price down further.
Where can I see promoter pledging for an Indian company?
In the quarterly shareholding pattern filed on NSE and BSE within 21 days of each quarter's end, which shows promoter shares pledged or encumbered as a number and a percentage. Event disclosures of new pledges, invocations and releases are also filed with the exchanges.
How much promoter pledging is considered high?
SEBI itself draws a line at 50 percent of the promoter group's holding or 20 percent of the company's share capital, above which the promoter must disclose detailed reasons within 2 working days. A rising pledge percentage over several quarters is a stronger signal than any single reading.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
Related
- Goodwill impairment: the day the future said noPaying Rs 1,000 crore for Rs 400 crore of real assets parks Rs 600 crore of optimism as an asset, and the write down only catches the books up to cash that left years earlier.Company numbers . . 5 min
- Off balance sheet debt: the notes are the balance sheetReported net debt of 1.2 times EBITDA becomes 2.7 times once lease liabilities and supply chain financing are counted, before the contingent liabilities in the notes.Company numbers . . 5 min
- Goodwill: the asset that exists because they overpaidA Rs 400 crore goodwill write down can turn a 500 crore profit year into 100 without a rupee of cash moving, as Tata Steel's Corus impairment showed.Company numbers . . 5 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.