

Company numbers..6 min read
Bonus shares: the same pizza, more slices
A 1:1 bonus doubled the share count and halved the price, left Rs 80,000 worth Rs 80,000, and started a fresh holding period clock on the new shares.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
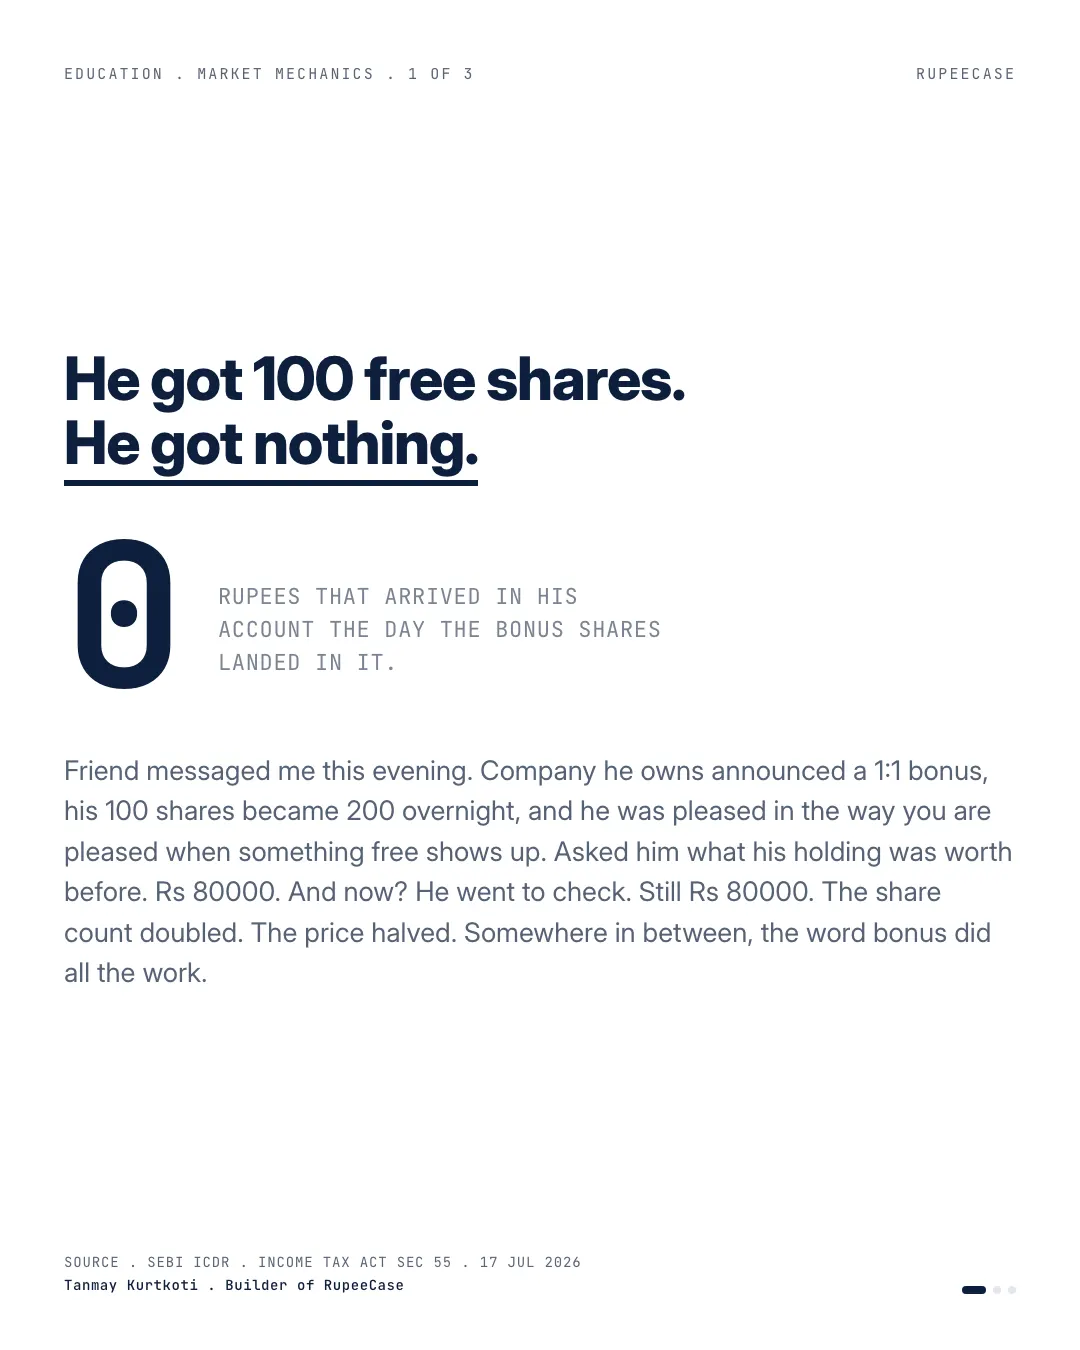
Friend messaged this evening. A company he owns announced a 1:1 bonus, his 100 shares became 200 overnight, and he was pleased in the way you are pleased when something free turns up.
Asked him what the holding was worth before. Rs 80,000.
And now? He went to check. Still Rs 80,000.
The share count doubled. The reference price halved. Somewhere in between, the word bonus did all the work.
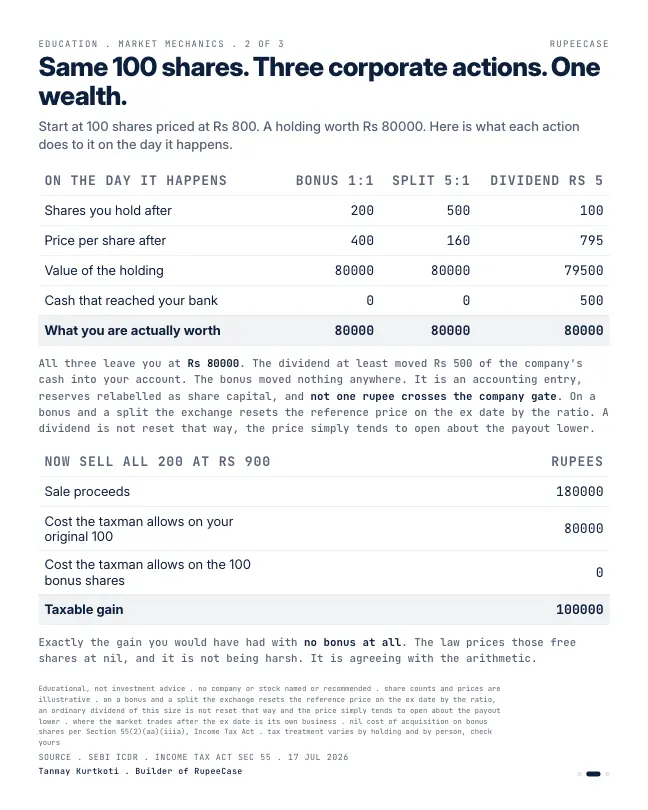
Here is what actually happens. A bonus is an accounting entry. Free reserves get relabelled as share capital. Not one rupee crosses the company gate and not one lands in your account. A split is barer still, the face value gets subdivided and the price adjusts to match. A dividend at least moves real cash from the company's balance sheet to your bank. A bonus moves a decimal.
The proof is sitting in the tax code, of all places. Sell all 200 shares at Rs 900. The law allows Rs 80,000 of cost on your original hundred and exactly nil on the bonus hundred, because you paid nothing for them. Taxable gain Rs 1,00,000, which is precisely the gain you would have had with no bonus at all. The law is not being harsh. It is agreeing with the arithmetic.
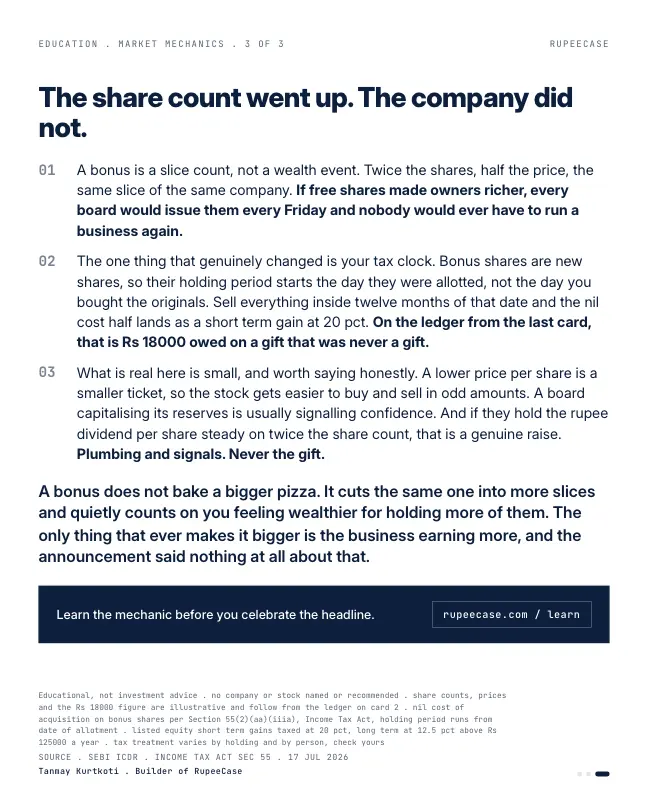
The one thing that genuinely changed is the clock. Bonus shares are new shares, so their holding period starts on the day they were allotted, not the day you bought the originals. Sell inside twelve months of that date and the nil cost half lands as a short term gain at 20 pct. On these numbers, Rs 18,000 owed on a gift that was never a gift.
What is real is small. A lower price per share is a smaller ticket. A board capitalising reserves is usually signalling confidence. Keep the rupee dividend per share steady on twice the count and that is a genuine raise. Plumbing and signals, never the gift.
A bonus does not bake a bigger pizza. It cuts the same one into more slices and counts on you feeling wealthier for holding more of them
The day the price halves
The holding in the opening was 100 shares at Rs 800. On the ex date of a 1:1 bonus, the exchange adjusts the reference price so the company's total value does not jump: the old price divided by two, Rs 400. The next morning, 200 shares at Rs 400 are worth Rs 80,000, exactly what 100 shares at Rs 800 were worth the evening before.
shares after a 1:1 bonus, up from 100
Worked example
adjusted price per share, down from Rs 800
Worked example
value of the holding, before and after
Worked example
Inside the company the same thing happens on the balance sheet. Say it had Rs 10 crore of share capital and Rs 500 crore of reserves. A 1:1 bonus moves Rs 10 crore from reserves into share capital. Net worth stays Rs 510 crore. Every line that measures the business, sales, profit, cash, debt, is untouched. Only the per share figures halve: earnings per share, book value per share and the price.
The calendar from board meeting to your demat
Since T+1 settlement, the ex date and the record date are the same day, so anyone who owns the shares at the end of the day before qualifies. SEBI also tightened how fast the new shares must arrive.
- Board approves the bonus
The company informs NSE and BSE and fixes a record date, after shareholder approval where it is needed.
- Ex date, price adjusts
The reference price is divided by 2 for a 1:1 bonus. Buy that day and you do not get the bonus.
- Bonus shares credited
The new shares reach the demat account one working day after the record date.
- Bonus shares can trade
From this day you can sell them, and their holding period has already started.
- Bonus shares turn long term
Counted from the allotment date, not from when you bought the originals.
The tax, worked both ways
Now the clock from the opening, in rupees. You bought the original 100 shares more than a year ago. The bonus 100 were allotted three months ago. You sell all 200 at Rs 900, for Rs 1,80,000.
The original 100 are long term. Proceeds Rs 90,000 less cost Rs 80,000 is a gain of Rs 10,000, taxed at 12.5 percent only above the first Rs 1.25 lakh of equity long term gains in a year. If this is your only such gain, the tax is nil. The bonus 100 are short term, with a cost of nil. The whole Rs 90,000 is a short term gain at 20 percent: Rs 18,000.
Wait until the bonus shares cross 12 months and the same Rs 90,000 becomes a long term gain. Added to the Rs 10,000 from the originals, Rs 1,00,000 of long term gain sits inside the Rs 1.25 lakh exemption, and the tax is nil. The bonus changed nothing about how much you made. It changed when the taxman sees it as short term. The free Learn module on equity shares and corporate actions walks through bonus issues, splits, rights and buybacks side by side, and the capital gains tax calculator runs your own lots.
What actually moves money
Same value, more pieces
- No cash leaves the company
- Price per share adjusts on the ex date
- Bonus shares start a new 12 month clock
Cash moves to you
- The company's cash falls by the payout
- Price falls by about the dividend on the ex date
- Taxed at your slab rate as income
The one real gain hides in the dividend. Say the company paid Rs 10 a share before the bonus, Rs 1,000 on 100 shares. If it keeps paying Rs 10 a share on 200 shares, you receive Rs 2,000. That is a doubling of the payout, a decision the board made separately from the bonus. If it pays Rs 5 a share instead, nothing changed. Read the dividend per share after the bonus, not the bonus itself. The posts on stock splits and buybacks take the other two corporate actions apart the same way.
Questions readers ask
Do bonus shares increase the value of my investment?
No. The share count rises and the price per share falls in the same proportion on the ex date, so the value of the holding is unchanged. 100 shares at Rs 800 and 200 shares at Rs 400 are both Rs 80,000.
What is the cost of bonus shares for capital gains tax?
Nil. The original shares keep their purchase cost, and the bonus shares are treated as acquired for nothing on the date they were allotted. Their holding period also starts on that date, so selling them within 12 months gives a short term gain taxed at 20 percent.
Is a bonus issue better than a dividend?
They do different things. A dividend moves cash from the company to shareholders and is taxed as income at your slab rate. A bonus moves reserves into share capital and moves no cash at all; any real benefit comes only if the dividend per share is kept the same on the larger share count.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
- Free module 1.4Reading Financial Statements11 min read
- StrategyAllcap strategyNifty Total Market, 50 stocks, every 2 weeks
- Free module 6.1Equity Shares, Structure, Rights and Corporate Actions10 min read
- CalculatorLTCG and STCG on equityFree, with the formula and a worked example
- Blog topicCompany numbers notes24 notes
Related
- The buyback illusionRetiring 15 percent of shares lifts EPS almost 18 percent on flat profit, and since October 2024 buyback proceeds are taxed as a deemed dividend at slab.Company numbers . . 11 min
- The stock split that changed nothingA 1:1 split turned 1,000 shares at Rs 200 into 2,000 at Rs 100, left the P/E and the ownership fraction untouched, and the volume bump faded within 90 days.Company numbers . . 10 min
- Why EPS growth lags net profit growthNet profit up 40 percent and share count up 25 percent is EPS up 12 percent, so read the per share line, track the count and use diluted EPS.Company numbers . . 5 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.