

Company numbers..5 min read
Why EPS growth lags net profit growth
Net profit up 40 percent and share count up 25 percent is EPS up 12 percent, so read the per share line, track the count and use diluted EPS.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
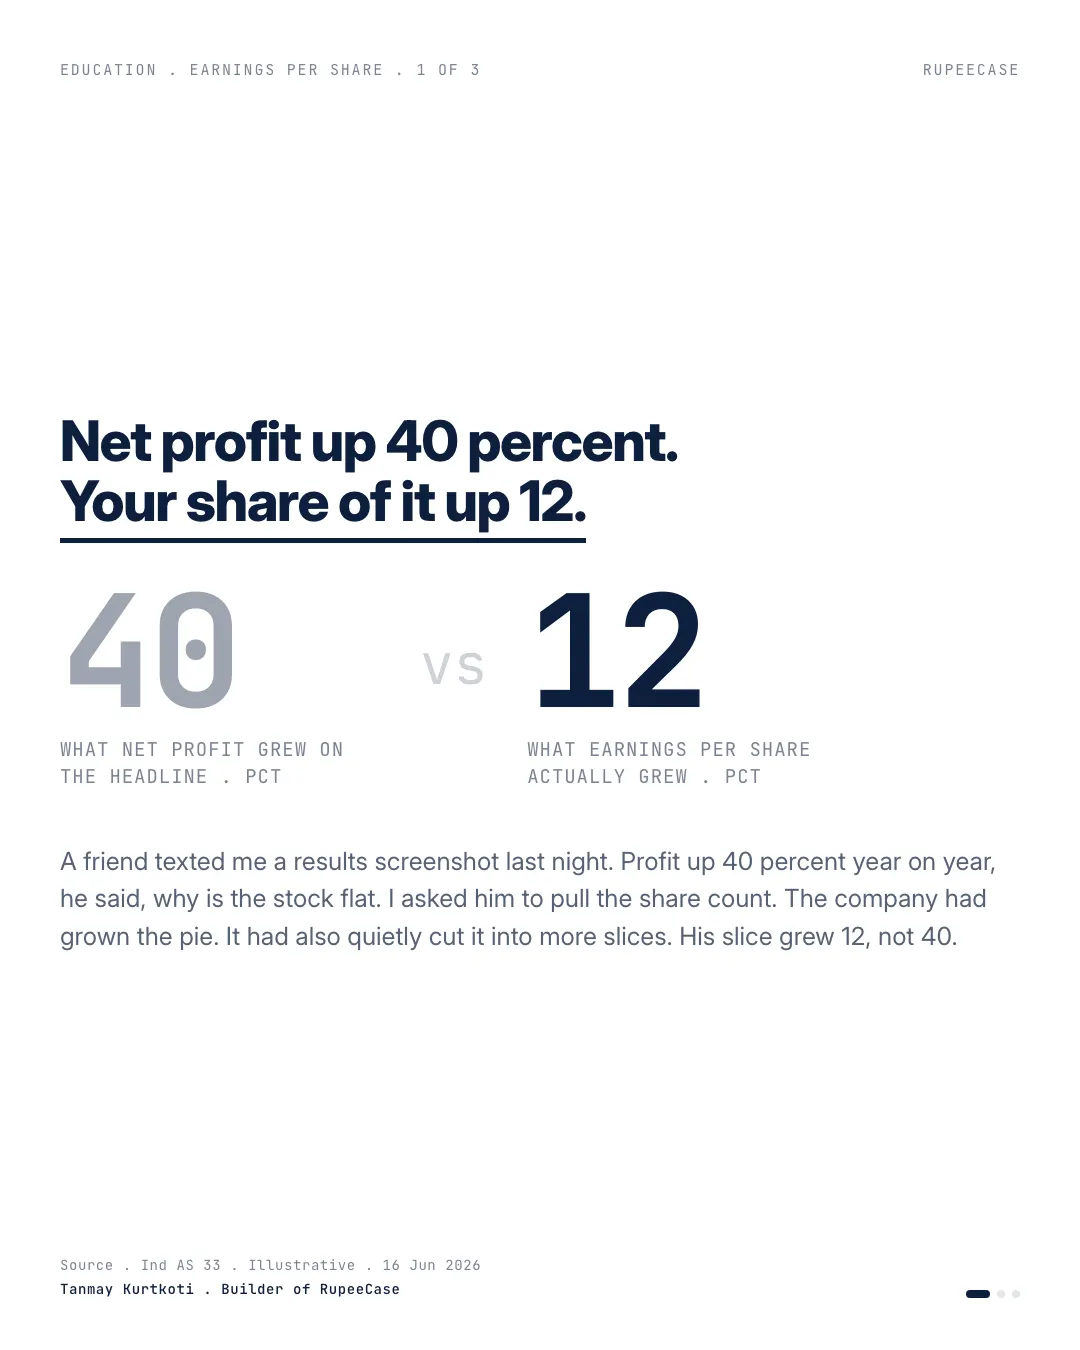
A friend sent me a results screenshot last night. Net profit up 40 percent year on year. The stock had not moved. Why, he asked.
I asked him to pull the one number a press release never leads with. The share count.
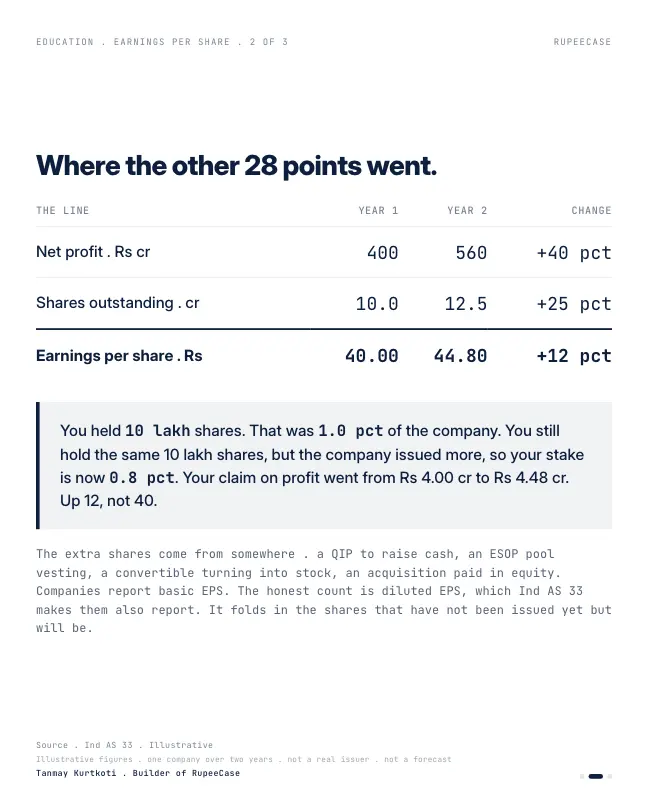
Here is the part most people miss. Net profit is the whole pie. Earnings per share is your slice of it. Over the year this company grew its profit from Rs 400 cr to Rs 560 cr, a clean 40 percent. It also issued more stock, growing the share count from 10 cr to 12.5 cr, up 25 percent. So earnings per share went from Rs 40.00 to Rs 44.80. Up 12 percent, not 40.
Watch it from the owner's seat and it gets sharper. My friend held 10 lakh shares, one percent of the company. After the issue he holds the same 10 lakh shares, but now they are 0.8 percent of a bigger company. His claim on the profit grew from Rs 4.00 cr to Rs 4.48 cr. The headline said 40. His slice said 12. The math is just 1.40 divided by 1.25, which is 1.12.
The extra shares always come from somewhere. A QIP to raise cash. An ESOP pool vesting. A convertible turning into equity. An acquisition paid in stock. None of it is automatically bad. Diluting to fund a project that earns more than its cost can grow your slice in the end. The point is to price it in your slice, not theirs.
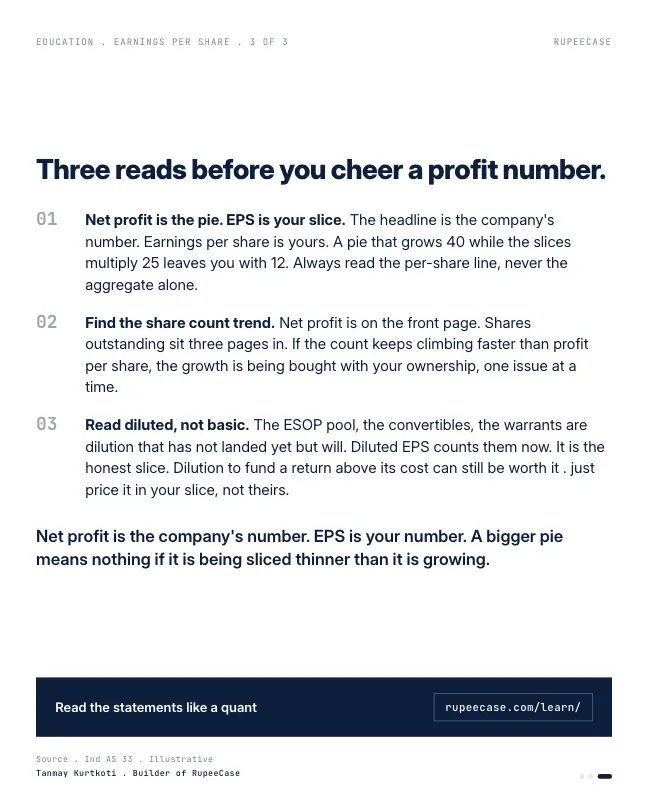
So three reads before you cheer a profit number. Read the per-share line, never the aggregate alone. Track the share count, because growth bought with your ownership is not the same as growth. And read diluted EPS, not basic, because the ESOP pool and the convertibles are dilution that simply has not landed yet.
Net profit is the company's number. EPS is your number. A bigger pie means nothing if it is being sliced thinner than it is growing.
The headline and the slice
Three numbers from the same results release. Only one of them belongs to the shareholder.
Net profit growth: Rs 400 crore to Rs 560 crore
Worked example, not a company
Share count growth: 10 crore to 12.5 crore
Worked example, not a company
EPS growth: Rs 40.00 to Rs 44.80
Worked example, not a company
The rule is one division. EPS growth is one plus profit growth, divided by one plus share growth, minus one. 1.40 over 1.25 is 1.12. Any time a company reports profit growth, run this line before anything else.
Did the new money earn its keep?
Say the 2.5 crore new shares came from a QIP at Rs 800 a share. That raised Rs 2,000 crore. Suppose the old business grew profit 15 percent on its own, from Rs 400 crore to Rs 460 crore, and the new money added the other Rs 100 crore.
Now ask the owner's question. Without the issue, profit would have been Rs 460 crore on 10 crore shares, an EPS of Rs 46.00. With the issue, EPS is Rs 44.80. The existing owners would have been better off if the company had not raised the money at all. The Rs 2,000 crore earned 5 percent after tax, and that was not enough.
The break even is simple to find. For EPS to stay at Rs 46.00 on 12.5 crore shares, profit must be Rs 575 crore. So the new money had to add Rs 115 crore a year, 5.75 percent after tax on Rs 2,000 crore. Anything above that grows your slice. Anything below shrinks it, even though the headline profit jumps.
Basic EPS, diluted EPS and what has not landed yet
Indian companies report two EPS figures under Ind AS 33. Basic EPS divides profit by the shares already outstanding. Diluted EPS adds the shares that would exist if every employee option in the money and every convertible were turned into equity. Suppose this company has an ESOP pool and a convertible bond that together count as 1.5 crore shares under the standard. Diluted shares are 14 crore, and diluted EPS is Rs 560 crore over 14 crore, or Rs 40.00. Flat on last year. (Ind AS 33 also adds back the interest saved on a convertible; it is left out here to keep the arithmetic clear.)
- EPS last year40.00
- Had there been no issue46.00
- Basic EPS this year44.80
- Diluted EPS this year40.00
Rs per share. Worked example, not a company.
A 40 percent headline, a 12 percent basic EPS rise, and a diluted EPS that did not move. That is why the stock in the opening sat still.
Where new shares come from, and where to read about them
- QIP or preferential issueRaised under the SEBI ICDR Regulations, 2018. The placement document states the price, the number of shares and the use of the money.
- ESOPsGranted under the SEBI Share Based Employee Benefits and Sweat Equity Regulations, 2021. The annual report discloses options granted, vested, exercised and outstanding.
- Convertibles and warrantsBonds or warrants that turn into shares at a set price. The notes give the number of shares on conversion.
- Acquisitions paid in stockNew shares go to the seller. Compare what was bought with what the shares were worth.
The quickest check across years is the share capital line on the balance sheet, divided by face value. If it rises every year, ask what the company bought with your ownership. The free Learn module on equity shares, rights and corporate actions covers how issues, bonuses, splits and buybacks each change the share count and what each does to your slice. The posts on bonus shares and the buyback illusion run the same per share test on two other corporate actions.
Questions readers ask
Why does EPS grow slower than net profit?
Because the company issued more shares over the same period. EPS growth equals one plus profit growth divided by one plus share count growth, minus one. Profit up 40 percent with shares up 25 percent gives EPS up only 12 percent.
What is the difference between basic and diluted EPS?
Basic EPS divides profit by shares already outstanding. Diluted EPS also counts shares that would be created if employee options and convertible securities were turned into equity, so it is equal to or lower than basic EPS. Indian companies report both under Ind AS 33.
Is share dilution always bad for shareholders?
No. If the money raised earns more per new share than the existing business earns per old share, EPS rises over time. In the worked example the new Rs 2,000 crore needed to earn at least 5.75 percent after tax to leave existing owners no worse off; it earned 5 percent.
The cards
3 cards. Swipe, or tap to open.
Related
- Bonus shares: the same pizza, more slicesA 1:1 bonus doubled the share count and halved the price, left Rs 80,000 worth Rs 80,000, and started a fresh holding period clock on the new shares.Company numbers . . 6 min
- The buyback illusionRetiring 15 percent of shares lifts EPS almost 18 percent on flat profit, and since October 2024 buyback proceeds are taxed as a deemed dividend at slab.Company numbers . . 11 min
- The stock split that changed nothingA 1:1 split turned 1,000 shares at Rs 200 into 2,000 at Rs 100, left the P/E and the ownership fraction untouched, and the volume bump faded within 90 days.Company numbers . . 10 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.