

Portfolio construction..5 min read
Survivorship bias: the backtest told by the survivors
Running a strategy on today's fifty index names flatters the curve by a couple of points a year, because the twenty five deletions left after they had already hurt.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
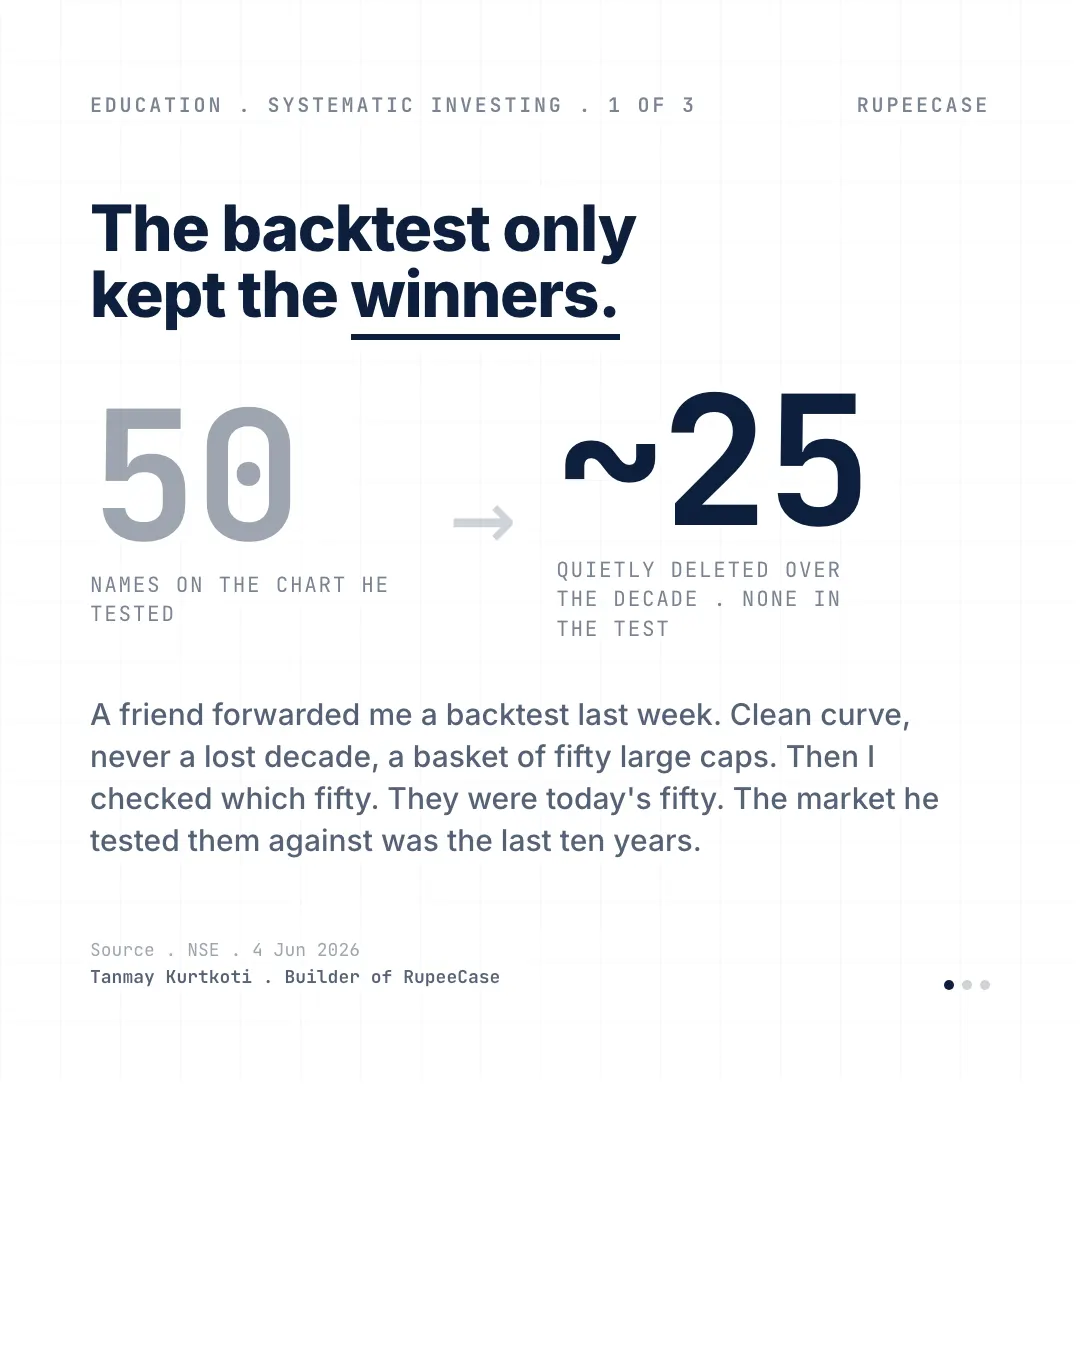
A friend forwarded me a backtest last week. Beautiful curve. A basket of fifty large caps, run over ten years, and the line never had a lost decade. His question was simple. Why not just buy this.
So I asked which fifty names. They were today's fifty. And the market he was testing them against was the last ten years. That is the whole problem, and it has a name.
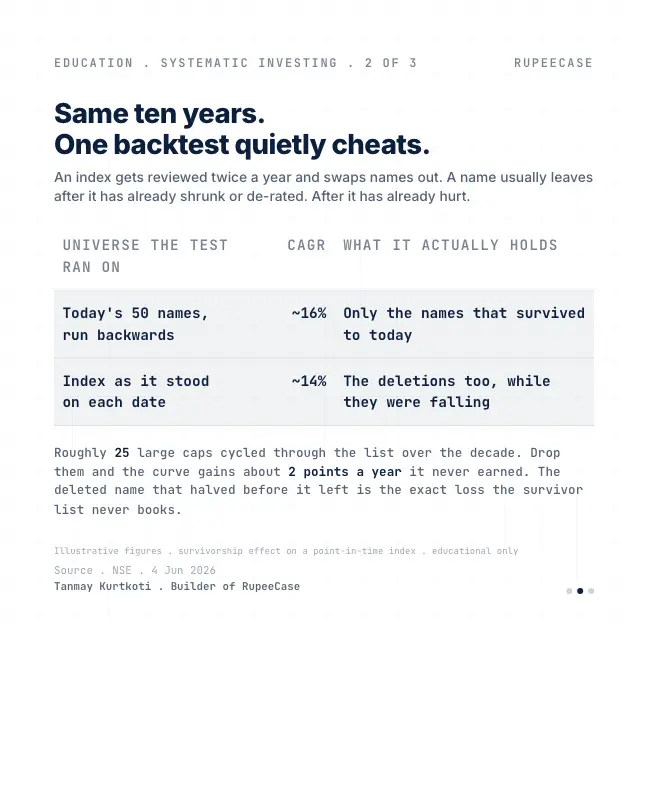
An index is not a fixed list. It gets reviewed twice a year, and names get swapped out. Roughly twenty five large caps cycled through the list over the last decade. Here is the part that matters: a name usually leaves the index after it has already shrunk or de-rated. It leaves after it has already hurt the people who held it.
Now run your backtest on today's fifty names. You are quietly holding only the companies that survived all the way to today. The ones that got deleted, often after halving, never show up. Not because the test is dishonest, but because they are not on the list you copied off the screen.
Same ten years, two different universes. The survivor list flatters the curve by something like a couple of percentage points a year. That gap is not skill. It is the losses you edited out.
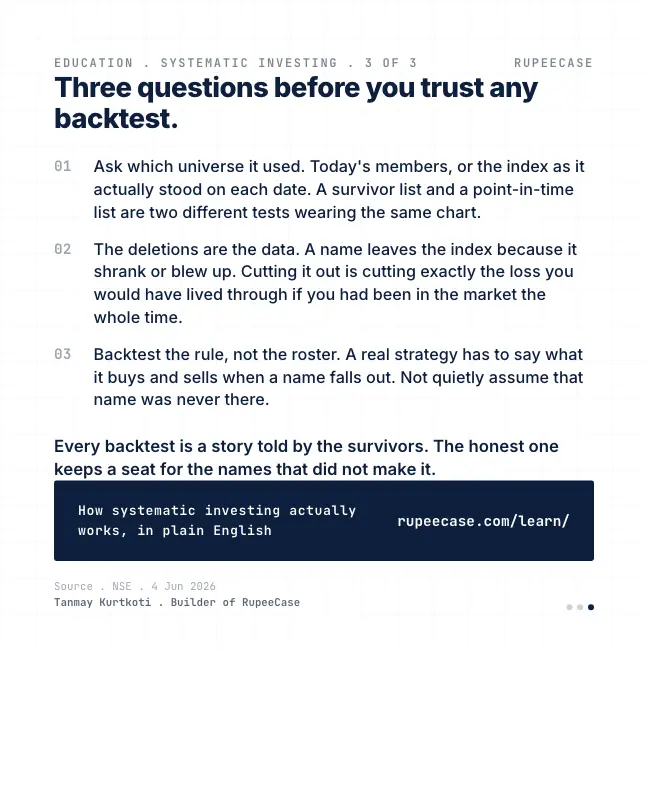
The deletions are not noise. They are the data. They are the exact drawdowns you would have lived through if you had actually been in the market the whole time. Cut them and you are not measuring a strategy. You are measuring hindsight.
So before you trust any backtest, ask one question. Did it use today's members, or the index as it actually stood on each date. And does the strategy say what it buys and sells when a name falls out, or does it just assume that name was never there.
Every backtest is a story told by the survivors. The honest one keeps a seat for the names that did not make it.
How a name leaves the list
Index membership follows a calendar. NSE reviews its broad indices twice a year, on market data for the six months to the end of January and the end of July, and the changes take effect at the end of March and the end of September. A company that has shrunk relative to the others drops in the ranking and makes way for one that has grown.
- Company A is a member
It sits in the index at its full weight and in every fund that tracks it.
- The business stumbles
The stock halves. Every index investor holds it all the way down.
- The ranking is checked
Company A's market value now ranks below the cut off on the review data.
- Company A is replaced
It leaves after the fall. A company that has risen takes its seat.
Run a backtest years later on today's list and Company A is simply absent. Its fall, which every real investor in the index lived through, has been deleted from the history. The company that replaced it is present, and present from the start of the test, long before it was large enough to be chosen.
Lists change more than people think
Index reviews a year for NSE broad indices
NSE Indices, index methodology, as of Oct 2026
Constituents in the Nifty Microcap 250
NSE Indices factsheet, 30 Sep 2026
Large caps through the Nifty 50 in a decade
Original post, 4 Jun 2026
The middle number is a small, useful reminder. An index called the Microcap 250 held 254 names at the end of September 2026, because changes between reviews and corporate events move the count. A list that looks fixed in its name is moving underneath.
What two points a year does to a backtest
The opening puts the survivor flattering at about two percentage points a year. That sounds small. Compound it and it is not.
On Rs 10 lakh over ten years, the survivor version shows about Rs 5.1 lakh that no real investor ever earned. Over twenty years the gap grows to about Rs 29 lakh. And because the deleted names usually fell hard before leaving, the survivor test also shows a shallower worst fall, which is the number most people use to decide whether they can hold a strategy.
A test you can trust
- Use the list as it stoodOn every rebalance date, pick only from the index members on that date.
- Keep the leaversHold a deleted name until the rule sells it, at the price it actually traded.
- Include the deadMerged, suspended and delisted companies stay in the data with their final prices.
- Charge real costsEvery trade pays costs and tax, as it would in a real account.
The free Learn module on how backtesting works covers survivorship, look ahead bias and overfitting with examples and a quiz. The CAGR calculator turns any two values into an annual rate, which helps when you check a backtest's claims by hand. For another way a clean looking result can mislead, read the optimizer is an error maximizer.
Questions readers ask
What is survivorship bias in backtesting?
It is the error of testing a strategy only on companies that still exist or still belong to an index today. Companies that fell, shrank or were removed are left out, so the test looks better than real history did.
How often does the Nifty 50 change its stocks?
NSE reviews the index twice a year, using data for the six months to the end of January and the end of July, with changes taking effect at the end of March and the end of September. Replacements can also happen between reviews after corporate events.
How can I tell if a backtest has survivorship bias?
Ask whether it chose stocks from the index members on each historical date or from today's list, and whether delisted and removed companies are included with their actual prices. If the answer to either is unclear, treat the results with caution.
The cards
3 cards. Swipe, or tap to open.
Related
- The lower number is your profileA real risk profile scores willingness and capacity separately out of 50 and takes the lower one, which is how a self declared daredevil with an eight month horizon ends up conservative.Portfolio construction . . 5 min
- The optimizer is an error maximizerOne point of forecast error moved eighty points of portfolio weight in a three stock demo, which is why DeMiguel, Garlappi and Uppal found equal weight hard to beat out of sample.Portfolio construction . . 5 min
- 60/40 is a 94/6 bet with better brandingAt 18 percent equity volatility and 5 percent debt volatility, a 60/40 book carries 94 percent of its risk in equity, and a true risk split needs about 22/78.Portfolio construction . . 4 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.