

Portfolio construction..4 min read
60/40 is a 94/6 bet with better branding
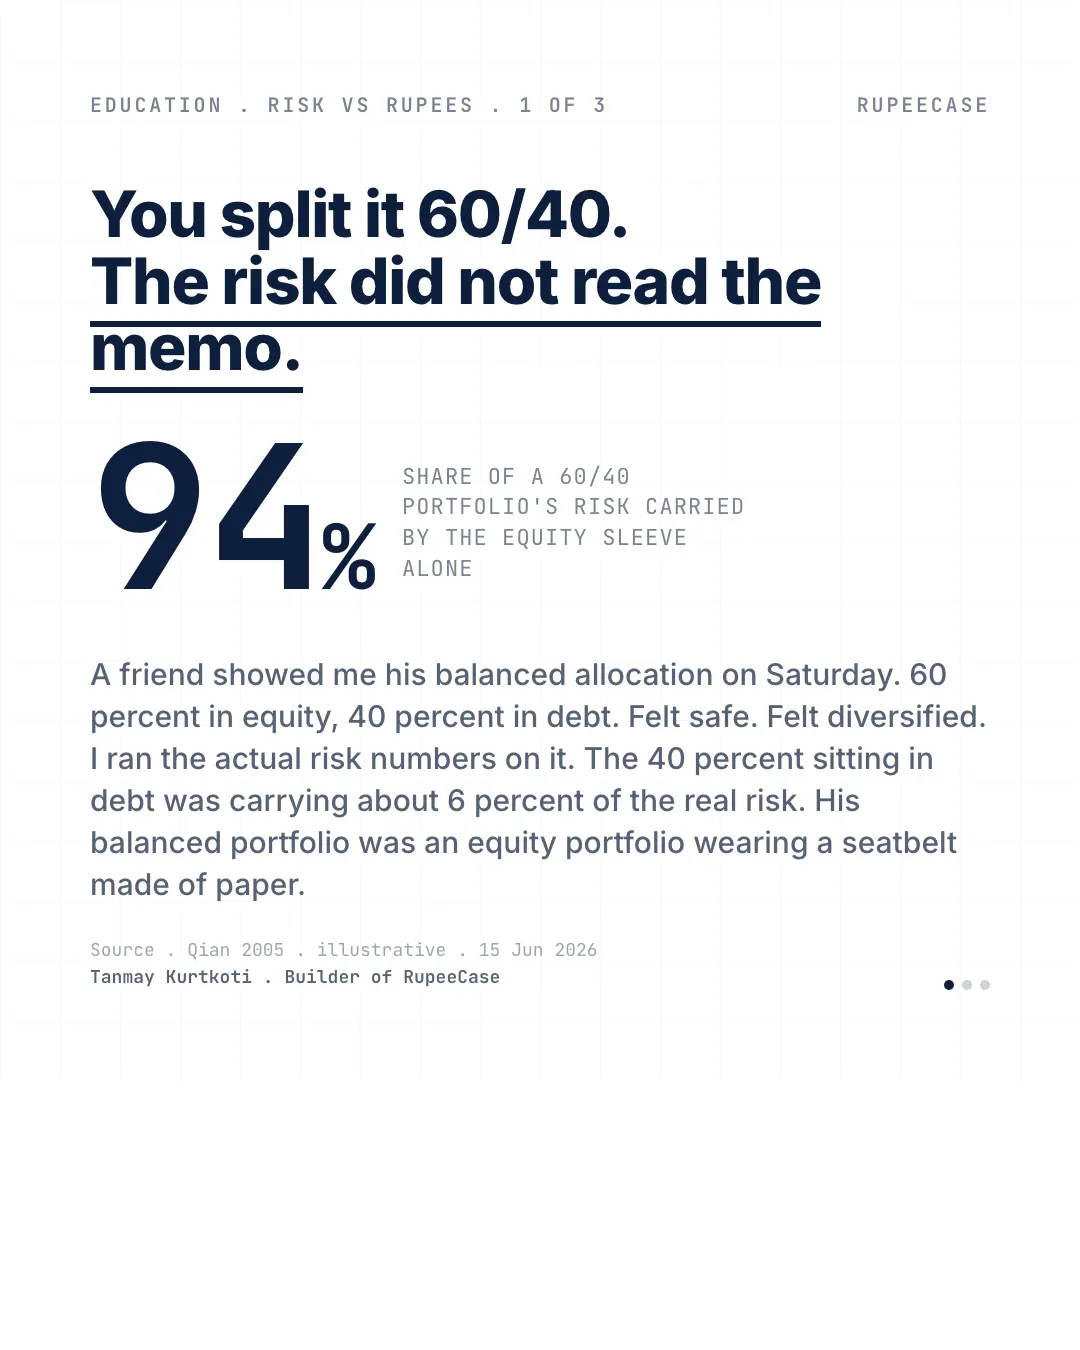
At 18 percent equity volatility and 5 percent debt volatility, a 60/40 book carries 94 percent of its risk in equity, and a true risk split needs about 22/78.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
A friend showed me his "balanced" portfolio on Saturday. 60 percent equity, 40 percent debt. He liked the symmetry of it. Felt safe. Felt diversified.
So I ran the actual risk on it. The 40 percent sitting in debt was carrying about 6 percent of the real risk. The equity sleeve was carrying the other 94. His balanced portfolio was an equity portfolio wearing a seatbelt made of paper.
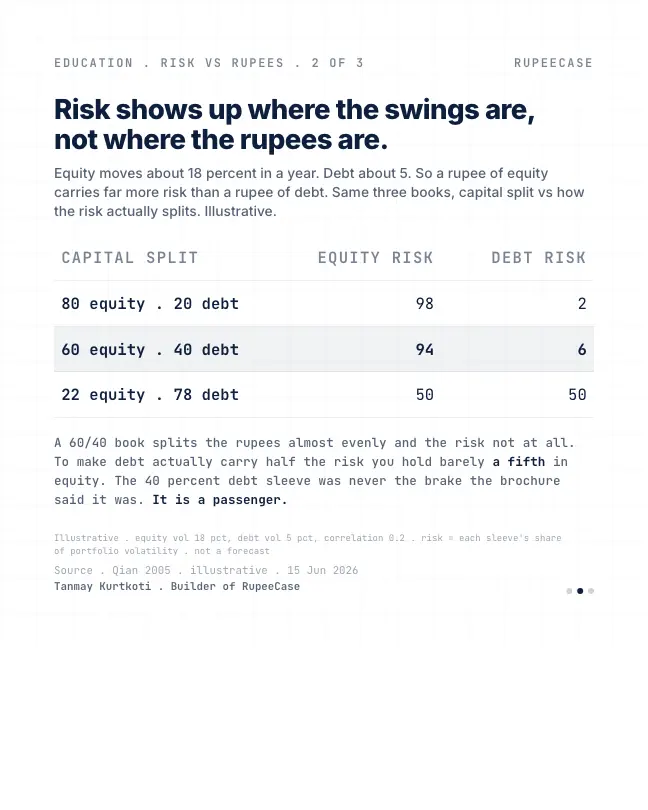
Here is the part nobody tells you. Capital weight and risk weight are two completely different things. Rupees tell you what you own. Volatility tells you what you are actually betting on. Equity swings about 18 percent in a year. Debt swings about 5. So a single rupee of equity carries far more risk than a single rupee of debt, and the risk piles up wherever the swings are, not wherever the money sits.
Run the same book three ways and the gap is almost comic. Split the capital 80/20 and equity carries 98 percent of the risk. Split it 60/40 and equity carries 94. To get debt to actually carry half the risk, you have to hold barely a fifth of your money in equity, somewhere near a 22/78 split. The 40 percent debt sleeve was never the brake the brochure implied. It softens the fall a little. It does not split the risk.
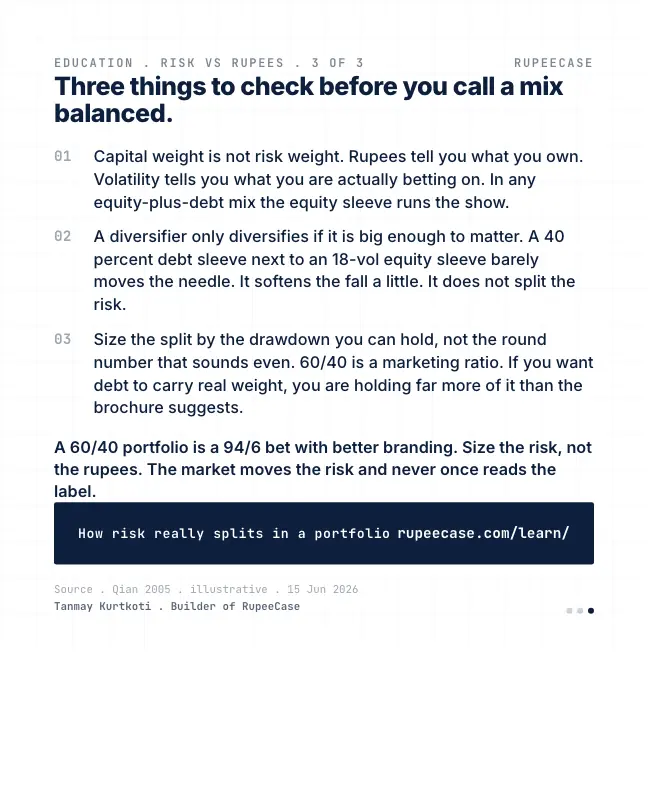
The honest version: 60/40 is a marketing ratio, not a risk decision. A diversifier only diversifies if it is large enough and different enough to move the only number that hurts you, the drawdown. Size the split by the fall you can actually sit through, not by the round number that sounds even.
A 60/40 portfolio is a 94/6 bet with better branding. Size the risk, not the rupees. The market moves the risk and never once reads the label.
The 94 shows up in a real quarter
The cleanest check is a bad quarter. From 31 Dec 2025 to 30 Mar 2026 the Nifty 50 fell 14.54 percent and the Nifty Composite G-sec Index fell 1.44 percent, by NSE closing data. A 60/40 mix of the two lost 9.30 percent. Now split that loss by sleeve.
The equity sleeve lost 0.60 x 14.54 = 8.72 points. The debt sleeve lost 0.40 x 1.44 = 0.58 points. Of the 9.30 point fall, 8.72 came from equity. That is 94 percent of the loss from 60 percent of the money.
- Equity sleeve, 60%-8.72%
- Debt sleeve, 40%-0.58%
- Whole 60/40 portfolio-9.30%
Contribution to the portfolio's return, 31 Dec 2025 to 30 Mar 2026. NSE closes: Nifty 50 26,129.60 to 22,331.40; Nifty Composite G-sec Index 3,052.91 to 3,009.05. RupeeCase calculation.
The figure matches the textbook number by accident of one quarter, but the shape is no accident. Over the two years from 14 Oct 2024 to 30 Sep 2026, quarter end NSE closes give the Nifty 50 an annualised swing of about 16.5 percent and the G-sec index about 4.4 percent. Equity was close to four times as volatile, so each rupee in it carried close to four times the risk.
Risk contribution, worked through
Each sleeve's share of the risk is its weight times its volatility times how much it moves with the whole portfolio. For two assets the equity share works out to (w x a) x (w x a + rho x (1 minus w) x b) divided by the portfolio variance. With 60 percent at 18, 40 percent at 5 and a correlation of 0.2, the variance is 116.64 + 4.00 + 8.64 = 129.28, and equity's part is 116.64 + 4.32 = 120.96. That is 93.6 percent.
Put in 80 for the equity weight and the share is about 98 percent. Put in 22 and it falls to about 51. With the NSE inputs of 16.5 and 4.4, a 60/40 still puts about 94 percent of the risk in equity.
What the label hides
MythA 60/40 portfolio splits its risk 60/40.
FactIt splits its capital 60/40. In the quarter to 30 Mar 2026, equity produced 94 percent of a 60/40 mix's loss.
MythMore debt always means a balanced portfolio.
FactEven 50/50 leaves close to 90 percent of the risk in equity at these volatilities. Balance in risk needs about a fifth in equity.
None of this makes 60/40 a bad choice. It makes it an equity portfolio with a cushion, which may be exactly what you want. The useful habit is to describe your mix by its risk and its worst fall, not by its rupees, and then to decide whether that is the bet you meant to make.
The free Learn module on risk management covers risk budgets, drawdown limits and how to size sleeves by risk, with a quiz at the end. The asset allocation calculator gives a starting split from your horizon. For the same idea told through the pie chart, read capital weight is not risk weight.
Questions readers ask
Is a 60/40 portfolio really balanced?
In capital, yes. In risk, no: because equity swings several times more than debt, a 60/40 mix carries roughly 94 percent of its risk in equity. In the quarter to 30 Mar 2026, equity produced 8.72 points of a 9.30 point loss.
What is risk contribution in a portfolio?
It is the share of the portfolio's total volatility that comes from each holding. It depends on the holding's weight, its own volatility and how it moves with the rest of the portfolio, so it is usually very different from the capital weight.
What equity and debt split gives equal risk?
With equity at about 18 percent volatility and debt at about 5, roughly 22 percent equity and 78 percent debt gives each sleeve about half the risk. The exact split depends on the volatilities you use.
The cards
3 cards. Swipe, or tap to open.
Related
- Capital weight is not risk weightA 60/40 portfolio's risk decomposes to about 95/5, and genuinely splitting risk down the middle takes roughly 22 percent in stocks and a 6 percent annual swing.Portfolio construction . . 4 min
- The optimizer is an error maximizerOne point of forecast error moved eighty points of portfolio weight in a three stock demo, which is why DeMiguel, Garlappi and Uppal found equal weight hard to beat out of sample.Portfolio construction . . 5 min
- The calm day contractThe same investor scored Moderately Aggressive on a quiet day and Conservative three weeks into a wobble, so fill the profile on a boring day and treat it as a contract.Portfolio construction . . 5 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.