

Personal finance and tax..6 min read
Goal based investing: the goal picks the vehicle
A college seat three years out and a retirement twenty two years out are a debt problem and an equity problem, and a Rs 20 lakh seat is Rs 63.4 lakh at 8 percent inflation.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
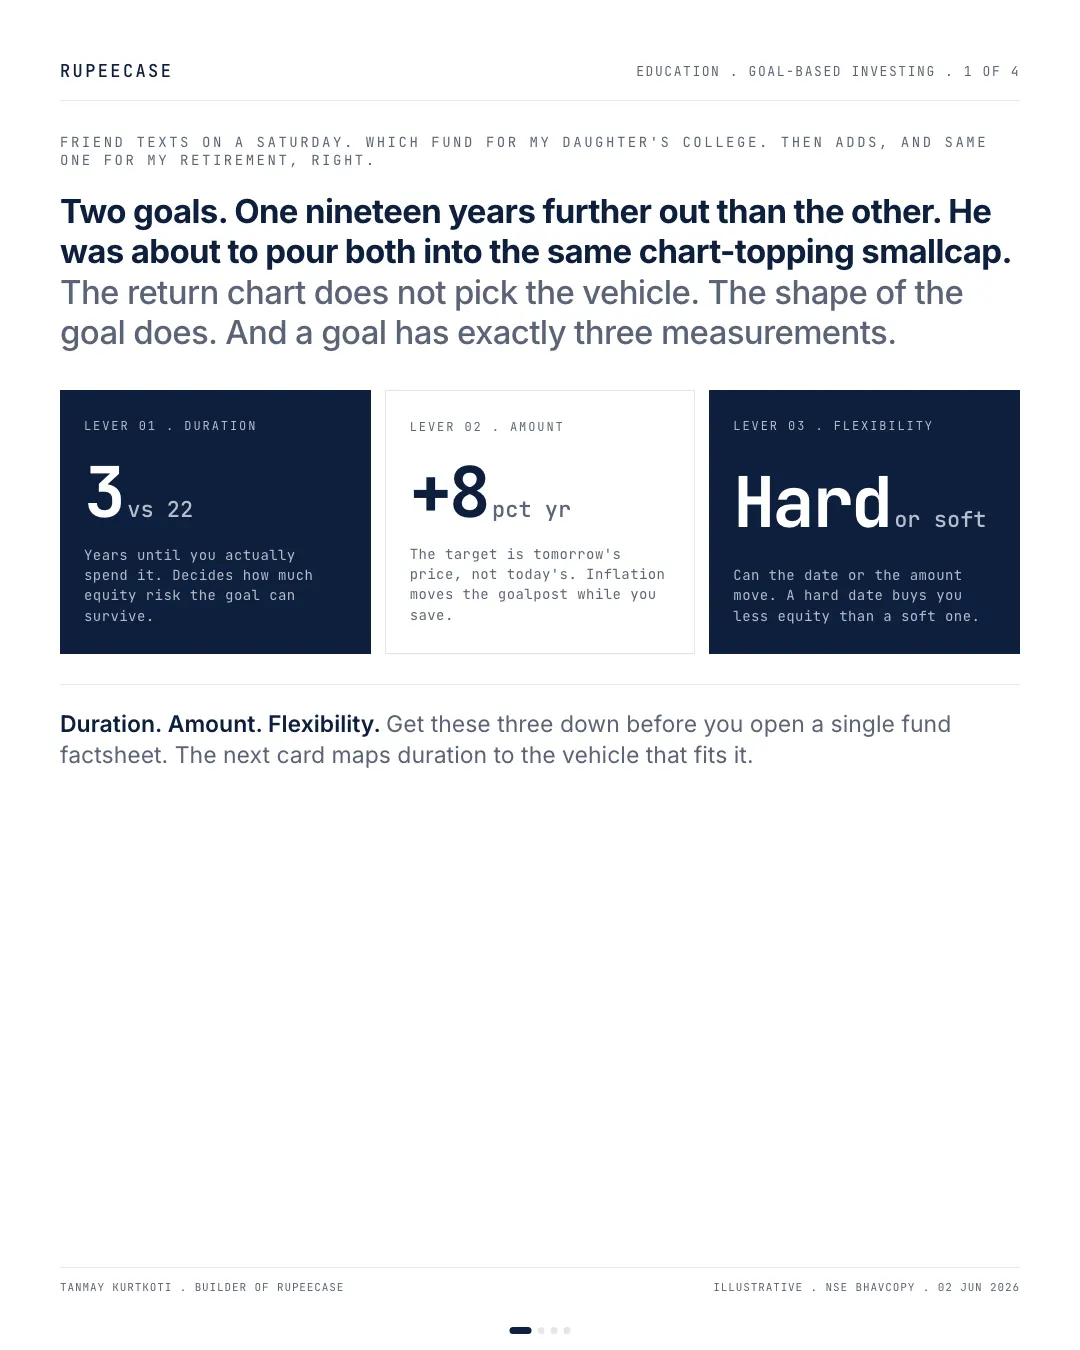
A friend texted me on Saturday asking which fund to pick for his daughter's college. Then, almost as an afterthought, "and the same one works for my retirement, right?"
His daughter starts college in about three years. His retirement is twenty-two years out. He was about to pour both into the same chart-topping model basket, because it had the best five-year line on the app.
Here is the part most people skip. The return chart does not pick the vehicle. The shape of the goal does. And every goal has exactly three measurements.
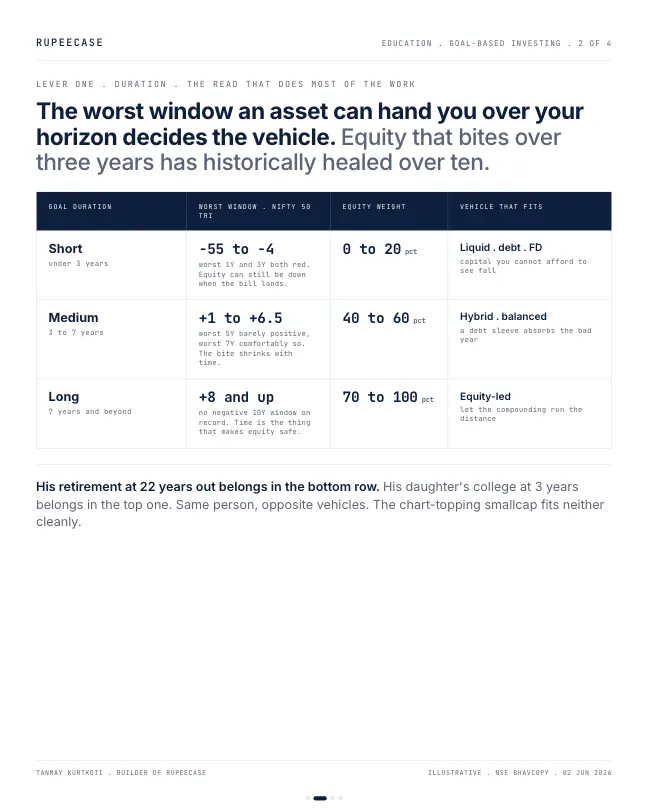
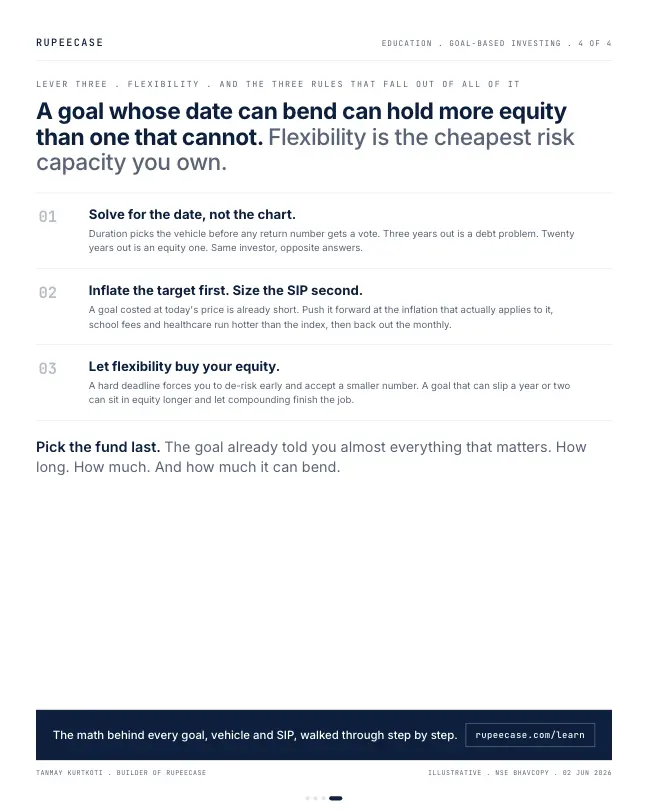
The first is duration. Money you need inside three years can still be sitting in a drawdown when the bill lands, so it does not belong in equity. Money you need in ten or more years has no negative rolling window on record, so equity is exactly where it should sit. His college seat and his retirement are not the same problem. One is a debt problem. The other is an equity one.
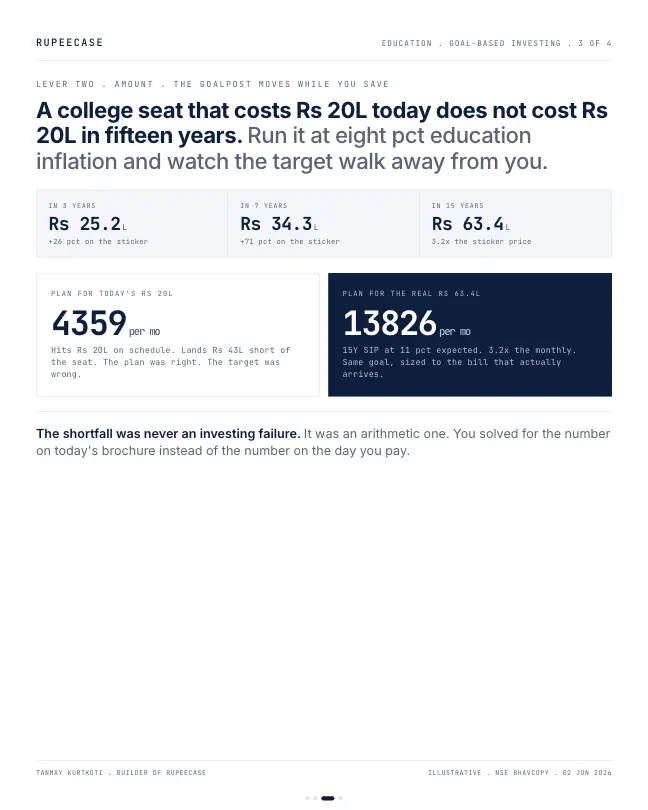
The second is the amount, and this is the one that quietly breaks plans. A college seat that costs Rs 20L today is not Rs 20L in fifteen years. Run it at eight pct education inflation and it is Rs 63.4L. Save for today's price and you will hit Rs 20L on schedule, then stand Rs 43L short of the seat. That was never an investing failure. It was an arithmetic one.
The third is flexibility. A goal whose date can slip a year can hold more equity, and let compounding finish the job. A hard deadline forces you to de-risk early and accept a smaller number.
Pick the fund last. The goal already told you almost everything that matters.
The three measurements, in the order I take them
When someone sends me a goal, I write three answers on paper before I look at a single fund. The vehicle falls out of them almost by itself.
- DurationYears until the money is spent. Under three: debt. Ten or more: equity can carry it.
- AmountToday's cost grown by inflation to the year you pay it.
- FlexibilityCan the date move? A soft date can hold more equity for longer.
- VehicleOnly now pick the fund, strategy or deposit that fits all three.
Notice that the five-year return line appears nowhere in that list. It is the loudest number on any app and it answers none of the three questions.
Why three years is too short for equity
A three year goal does not fail because equity has a bad decade. It fails because one bad stretch lands at the wrong moment. The Nifty 50 closed at a record 26,216.05 on 26 Sep 2024 and at 22,082.65 on 4 Mar 2025, a fall of 15.8 percent in a little over five months (NSE daily closes). It closed above that record again on 2 Jan 2026. Fifteen months is nothing for a retirement. On a three year goal it is close to half the runway.
And that was the broad index. Chart toppers fall harder. Allcap, the highest returning broad model on RupeeCase at a 44.70 percent CAGR, still had a worst fall of 22.72 percent along the way (Model, back tested, as of 27 Apr 2026). The best five-year line on any screen came with a drawdown like that somewhere inside it.
Nifty 50, 26 Sep 2024 record to 4 Mar 2025
NSE daily closes
Allcap model, worst fall
Model, back tested, as of 27 Apr 2026
All India CPI inflation, Aug 2026
MOSPI, 14 Sep 2026
CPI education services, Aug 2026
MOSPI, 14 Sep 2026
Here is the honest trade on the three year seat. Today's Rs 20 lakh seat costs Rs 25.19 lakh in three years at 8 percent inflation. Saving for it with a monthly SIP at an assumed 7 percent from a debt vehicle takes about Rs 62,730 a month. Assume 12 percent from equity and it drops to about Rs 57,910. The equity bet saves you Rs 4,820 a month, about Rs 1.74 lakh over 36 months. One fall like the 15.8 percent above, hitting Rs 20 lakh of savings in the final year, costs about Rs 3.2 lakh. You are taking a coin toss to save less than you could lose.
The amount: which inflation number to use
The national number is not your number. All India CPI inflation was 4.82 percent in Aug 2026, and the education services index rose 3.73 percent over the year, with higher education at 3.63 percent (MOSPI, CPI on base 2024, released 14 Sep 2026). So why did I use 8 percent in the post above?
Because the CPI tracks the average fee across every school and course in the country. A seat at a specific college, in a specific city, in a course that is in demand, moves differently. The free Learn module on inflation shows how the CPI basket is built and why your personal rate can sit far from the headline. I plan at the rate my actual bill has been rising, and use the official series as a floor.
The rate matters more than people expect. Same Rs 20 lakh seat, fifteen years out:
- 3.73% (CPI education)Rs 34.6 L
- 4% a yearRs 36.0 L
- 6% a yearRs 47.9 L
- 8% a yearRs 63.4 L
- 10% a yearRs 83.5 L
Rs 20 lakh grown for 15 years at each rate. Worked example. CPI education rate from MOSPI, Aug 2026.
The gap between 4 and 8 percent is Rs 27.4 lakh on one goal. Guess low and the plan looks affordable on paper and falls short in the year it matters.
Turning the amount into a monthly number
Once the target is fixed, the SIP is plain arithmetic. Here is the fifteen year seat from the post, with the SIP made at the start of each month. Change the inputs to your own goal.
That last line is the trap from the post in one number. Planning at today's price asks for Rs 3,964 a month. The real seat needs Rs 12,573. The friend was not going to fail at investing. He was going to save diligently for the wrong amount.
Flexibility decides how long you stay in equity
The third measurement changes the glide path, not the target. A retirement date that can move by two years lets you hold equity closer to the end, because a bad year can be waited out. A college admission date cannot move. So for a hard goal, I start shifting money from equity to debt about three years before the bill, a little each year, so no single fall lands on the full amount.
Two of the friend's goals, side by side: the seat is three years away, fixed, and goes to debt now. Retirement is twenty-two years away, soft by a year or two, and can sit in equity for most of that time with a switch to debt in the last stretch. Same family, same salary, two vehicles. The cost of waiting on the long goal is the other half of this arithmetic, and SIP against lump sum covers how the money goes in.
Questions readers ask
How do I decide between debt and equity for a goal?
Start with the years until the money is spent. Money needed within about three years sits exposed to a fall like the Nifty 50's 15.8 percent drop between Sep 2024 and Mar 2025, so it usually goes to debt. Goals ten or more years away can carry equity, and whether the date can slip decides how early you shift back to debt.
What inflation rate should I use for my child's education goal?
The CPI education services index rose 3.73 percent in the year to Aug 2026 (MOSPI), but that is an all India average across every course. Use the rate at which fees for the kind of college you have in mind have actually risen, and test a higher one: a Rs 20 lakh seat in 15 years is Rs 36.0 lakh at 4 percent and Rs 63.4 lakh at 8 percent.
Why does planning at today's cost leave such a big shortfall?
Because inflation compounds just like returns. At 8 percent a year a cost roughly triples in 15 years, so a SIP sized for today's Rs 20 lakh reaches Rs 20 lakh on time and leaves the remaining Rs 43 lakh unfunded.
The cards
4 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
- GuideHow to invest for your child's education: the cost, the monthly amount and the glide pathThe future cost, the monthly amount at different returns, and the glide path out of equity.
- Free module 11.1Equity Taxation After July 2024: The New Rules10 min read
- StrategyAllcap strategyNifty Total Market, 50 stocks, every 2 weeks
- CalculatorRule of 72Free, with the formula and a worked example
Related
- Lifestyle creep: the raise that never reaches the portfolioBanking half of every increment lifts a savings rate from 20 to 35 percent without a felt cut and ends Rs 21.5 lakh ahead over a decade on the same income and returns.Personal finance and tax . . 5 min
- SIP vs lump sum: time in the marketPutting Rs 12 lakh in at once beat dripping it over a year in about two of every three historical windows, because markets rise roughly two years in three.Personal finance and tax . . 5 min
- The cost of waiting: start small, start nowA saver who invested Rs 10,000 a month from 25 to 35 and stopped ends with Rs 4.6 crore at 60, ahead of one who invested from 35 to 60, because time did the work.Personal finance and tax . . 5 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.