

Personal finance and tax..5 min read
SIP vs lump sum: time in the market
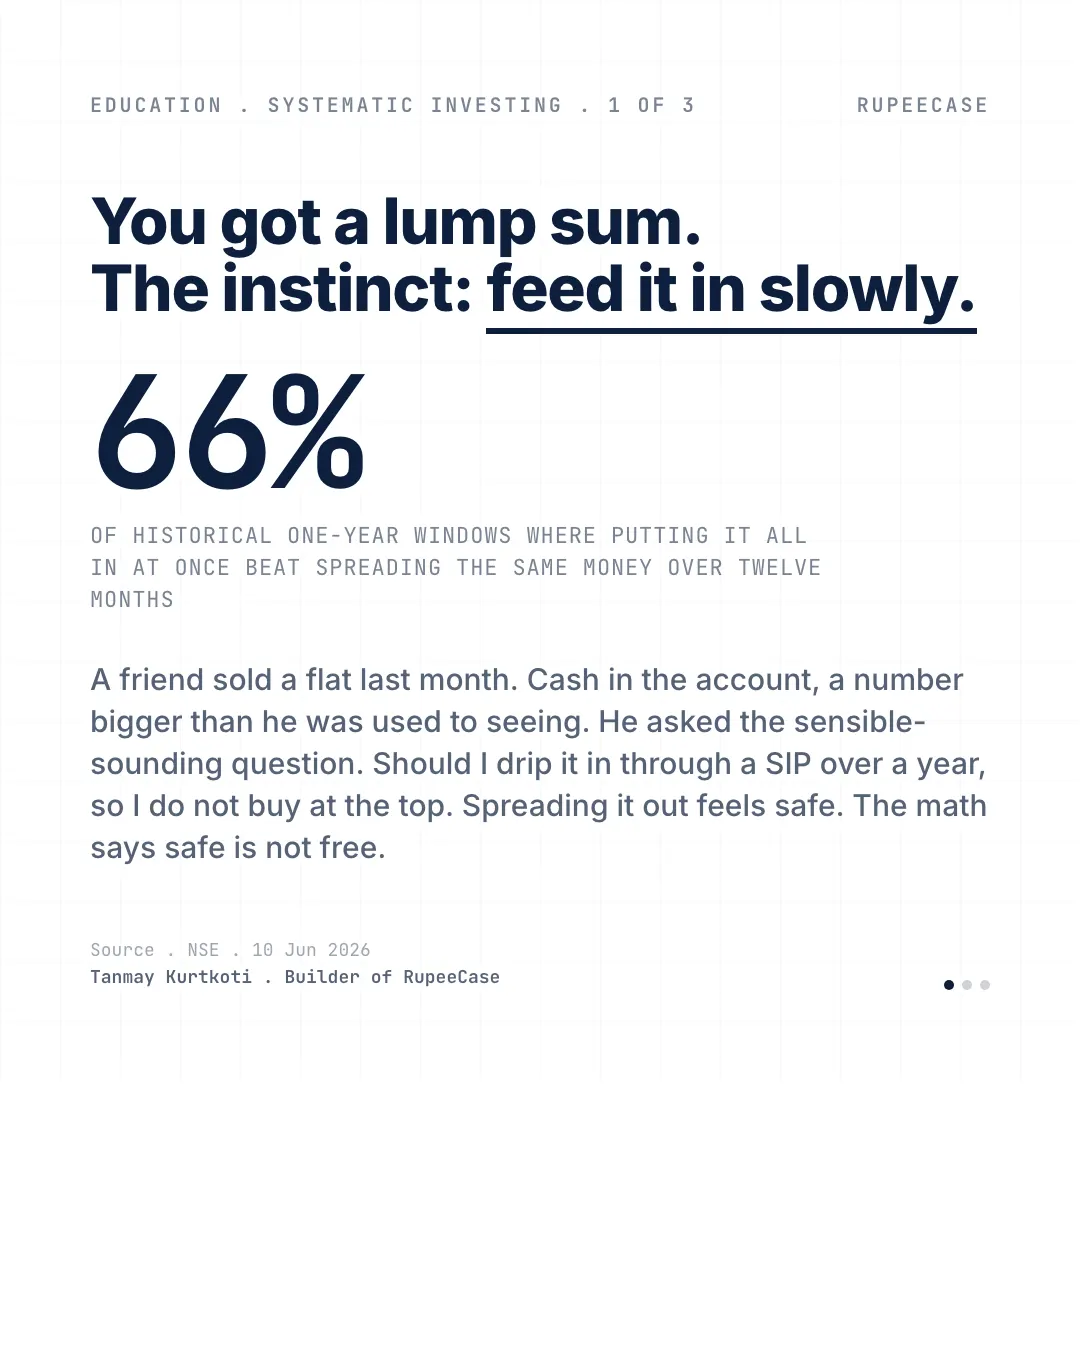
Putting Rs 12 lakh in at once beat dripping it over a year in about two of every three historical windows, because markets rise roughly two years in three.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
A friend sold a flat last month. For the first time he had a genuinely large number sitting in one account, and it made him nervous. So he asked the question that sounds responsible. "Should I drip it into the market through a SIP over a year, so I don't accidentally buy at the top?"
Spreading it out feels safe. I pulled the math, and safe turns out to have a price.
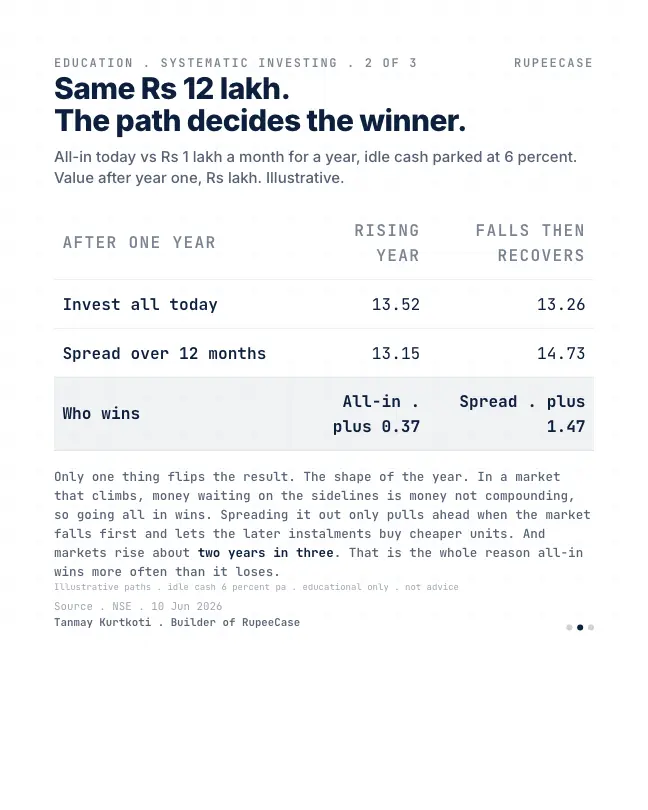
Run the same Rs 12 lakh two ways. Put it all in today, or feed in Rs 1 lakh a month for a year while the rest waits in a liquid sleeve earning about 6 percent. In a year where the market climbs, going all in ends around 13.52 lakh and spreading it out ends around 13.15 lakh. The gap is not magic. It is just that money waiting on the sidelines is money that is not compounding yet.
Then flip the year. Let the market fall first and recover later. Now all-in ends around 13.26 lakh and spreading ends around 14.73 lakh, because the later instalments quietly bought cheaper units. So staggering wins, but only in the year that drops first. And here is the thing the brochures skip: markets rise roughly two years in three. That single fact is the whole reason putting it in at once beat spreading it across twelve months in about two of every three historical windows.
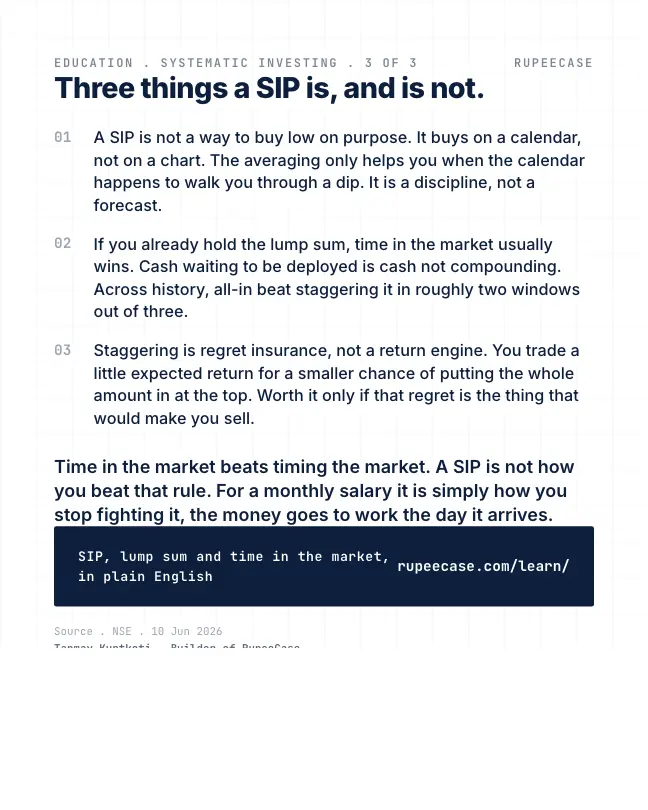
Which leads to the part most people get backwards. A SIP is not a clever way to buy low. It buys on a calendar, not on a chart. The averaging only helps you in the years the calendar happens to walk you through a dip. What a SIP actually does, for someone earning a monthly salary, is put each rupee to work the day it arrives. That is not timing the market. That is the opposite. It is the cleanest way to stop trying.
Time in the market beats timing the market. A SIP is not how you beat that rule. It is how you stop fighting it
I ran it on the last two years
The opening's two in three comes from long histories. I wanted to see the same test on the most recent stretch of real prices, so I took NSE's month end closes for the Nifty 50 from Oct 2024 and ran the friend's choice on every 12 month window I could: Rs 12 lakh all at once at a month end, against Rs 1 lakh at each of the next 12 month ends with the waiting cash earning 6 percent a year. Thirteen windows, each scored a year after it started.
12 month windows, Oct 2024 to Oct 2025 starts
NSE, Nifty 50 month end closes
won by putting it all in at once
NSE closes, worked example
won by spreading it over 12 months
NSE closes, worked example
That is the reverse of the long run result, and the reason is in the prices. The Nifty 50 closed Oct 2024 at 24,205 and was at 22,520 on 9 Oct 2026, with a deep fall in Mar 2026. Two years that ended lower are exactly the minority case the opening describes, the year that drops first. Over long histories those years are fewer. Over this particular two years they were most of the sample.
- Feb 2025 start, all inRs 13.66 L
- Feb 2025 start, spreadRs 12.56 L
- Oct 2024 start, all inRs 12.75 L
- Oct 2024 start, spreadRs 13.15 L
- Oct 2025 start, all inRs 10.51 L
- Oct 2025 start, spreadRs 11.42 L
Rs 12 lakh, value 12 months after the start. NSE Nifty 50 month end closes (Oct 2026 uses the 9 Oct close); price index without dividends, no costs; waiting cash at 6% a year.
Feb 2025 was a low month end, so putting everything in then won by over a lakh. Oct 2025 was near a high, so spreading won by about Rs 92,000. Nobody knew either on the day. That is the honest summary of the choice: the lump sum wins when the year goes up, and you only find out afterwards which kind of year it was.
Your own version
The calculator below simplifies the drip to one number: the average price your twelve instalments end up paying. Change it to see when spreading wins.
What the SIP is really for
MythA SIP is a way to buy the market cheaper than everyone else.
FactA SIP buys on a calendar. It pays a lower average price only in years that fall first. For a salary, its real job is to invest each rupee the month it arrives.
For a lump sum, both choices are rules, and that is the point the free Learn module on why rules beat gut feeling makes in general. All at once is a rule. Twelve equal monthly instalments is a rule. The one choice that has no rule behind it is waiting for the market to feel right, which is how lump sums end up sitting in a savings account for a year. The lump sum against SIP calculator compares the two at any return. Related: lump sum against drip and the cost of waiting.
Questions readers ask
Is it better to invest a lump sum or through SIP?
Over long histories a lump sum has usually ended ahead, because markets rise in more years than they fall. In the 13 one year windows from Oct 2024 to Oct 2025 starts on the Nifty 50, spreading over 12 months won 9 times, because the index ended the period lower. Which wins depends on the year, and that is only known afterwards.
Does SIP give a lower average price?
A SIP buys more units when prices are low and fewer when they are high, so its average cost is below the simple average price. That only beats a lump sum if the price falls after the start; in a rising year the lump sum's earlier entry wins.
What should I do with a large sum while I invest it in instalments?
Money waiting for later instalments usually sits in a liquid or money market fund, as in the opening's 6 percent assumption. That reduces the cost of waiting but does not remove it in a rising year.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
- GuideSIP in stocks: how a stock SIP works, and when a fund SIP is betterWhole shares, charges per instalment, tax by lot, and when a fund SIP wins.
- GuideLump sum or SIP: what to do with money you already haveEvery start month in our record, the Dec 2024 peak, and how to choose.
- Free module 11.1Equity Taxation After July 2024: The New Rules10 min read
- StrategyAllcap strategyNifty Total Market, 50 stocks, every 2 weeks
- CalculatorSIP calculatorFree, with the formula and a worked example
Related
- All in now, or drip it inVanguard's 1926 to 2022 data across seven markets shows a lump sum beat a three month drip about two times in three, and stretching the drip lowers the odds.Personal finance and tax . . 12 min
- The cost of waiting: start small, start nowA saver who invested Rs 10,000 a month from 25 to 35 and stopped ends with Rs 4.6 crore at 60, ahead of one who invested from 35 to 60, because time did the work.Personal finance and tax . . 5 min
- Lifestyle creep: the raise that never reaches the portfolioBanking half of every increment lifts a savings rate from 20 to 35 percent without a felt cut and ends Rs 21.5 lakh ahead over a decade on the same income and returns.Personal finance and tax . . 5 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.