

Costs: MF, PMS, RupeeCase..5 min read
Active fund, stripped: what 1.5 percent buys
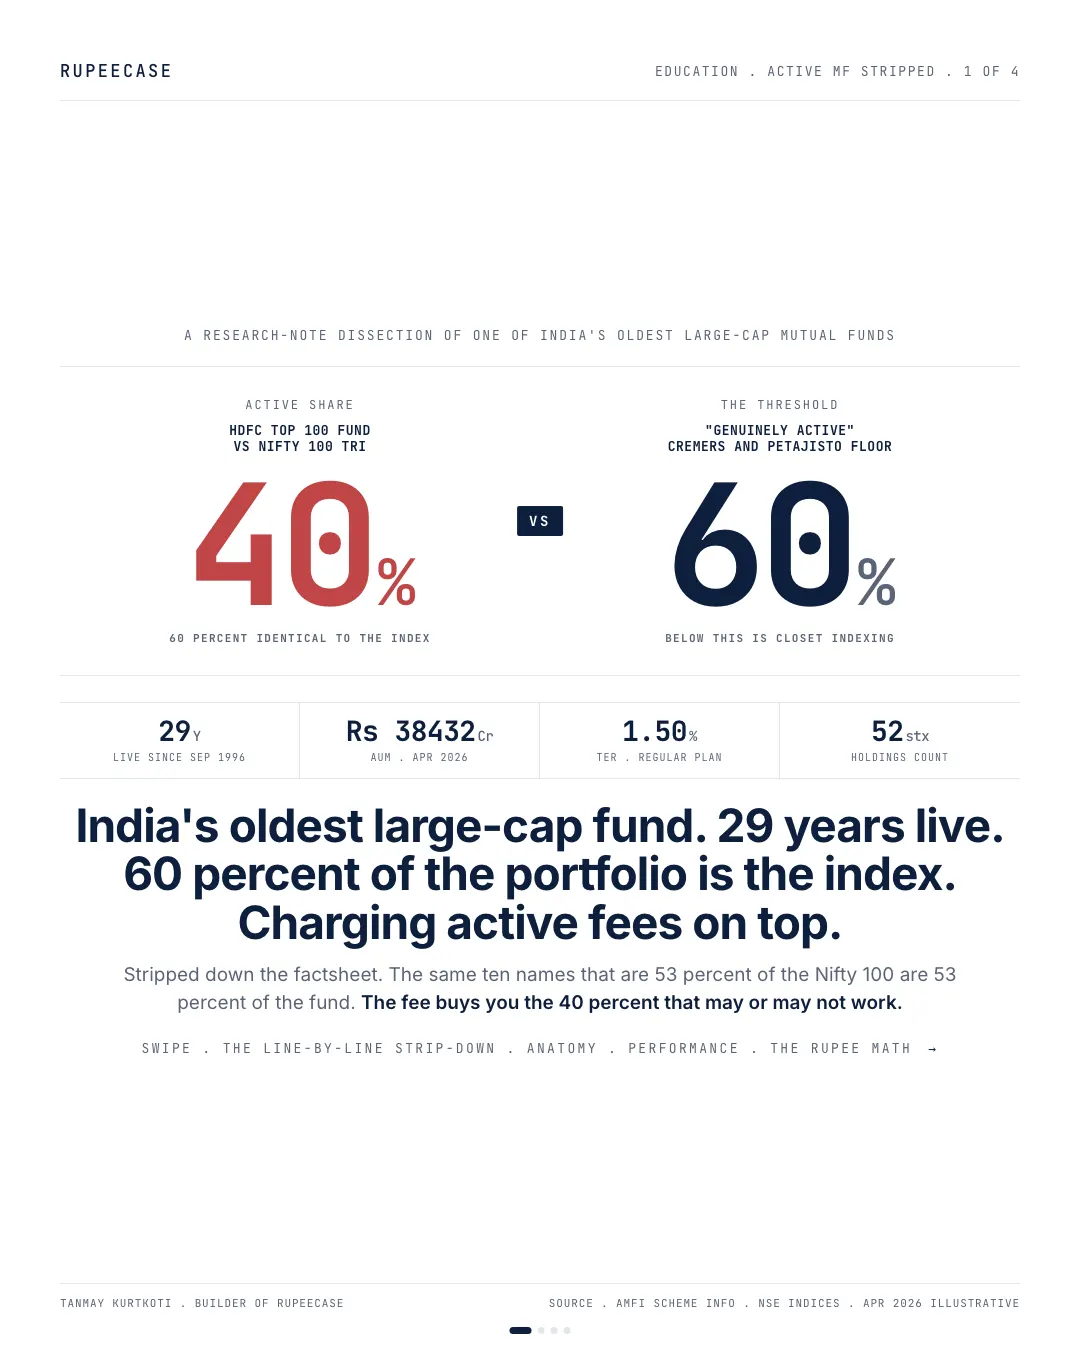
Taking apart a 29 year old active large cap fund shows about 40 percent active share, a direct plan that beats its benchmark by 0.4 points and a regular plan that trails it.
Fund figures in this note are public AMFI and factsheet data as published on 4 May 2026.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
Stripped down HDFC Top 100 Fund last weekend. 29 years live. Rs 38,432 Cr AUM. One of the oldest active large-cap mutual funds in India. Wanted to know what 1.5 percent a year actually buys you above the Nifty 100 TRI it benchmarks against.
The answer is uncomfortable.
Active share is the percent of a fund's portfolio that genuinely differs from its benchmark by weight. The concept comes from a 2009 paper by Cremers and Petajisto. Their finding . funds with active share below 60 percent are closet indexers . they look like the benchmark, charge active fees anyway, and as a group destroy value after fees. Above 60 are the funds that earn their keep often enough to justify the price tag. The plain-English explainer on active share, closet indexing and TER drag is at rupeecase.com/learn/
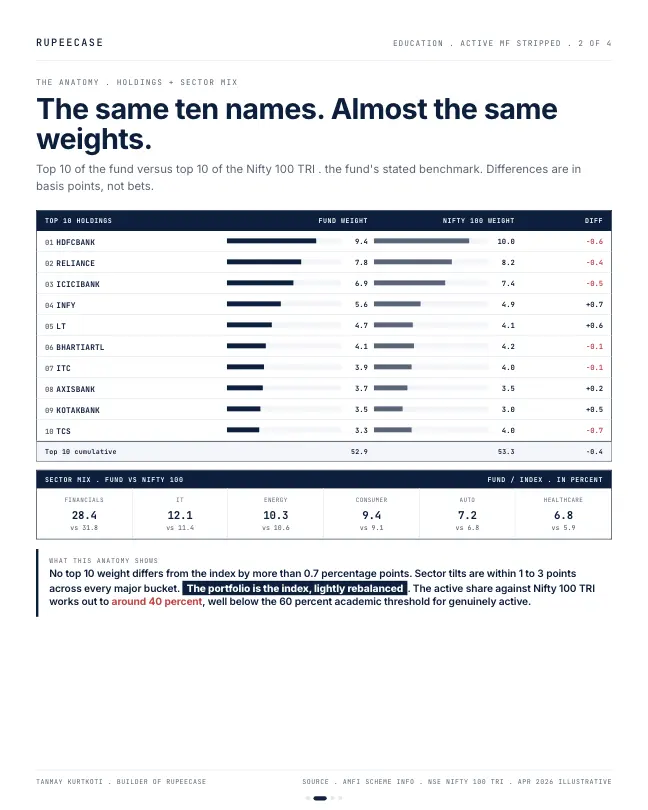
Top 100 Fund clocks in around 40 percent active share against the Nifty 100. The top 10 holdings are the same names as the index in near-identical proportions . HDFC Bank, Reliance, ICICI Bank, Infosys, L and T, Bharti Airtel, ITC, Axis Bank, Kotak, TCS . none of them differ from the index weight by more than 70 basis points. Sector deviations are all within 3 percentage points. The per-stock factsheets for the same names are at rupeecase.com/stocks/
The trap is that a long holdings list looks like effort. Active share ignores the count and measures only how far each weight sits from the benchmark weight.
MythA fund holding 60 or 80 stocks must be doing something very different from its index.
FactHolding the same names at near index weights is still the index. Active share counts weight differences, not names, and 40 percent means 60 percent of the money mirrors the benchmark.
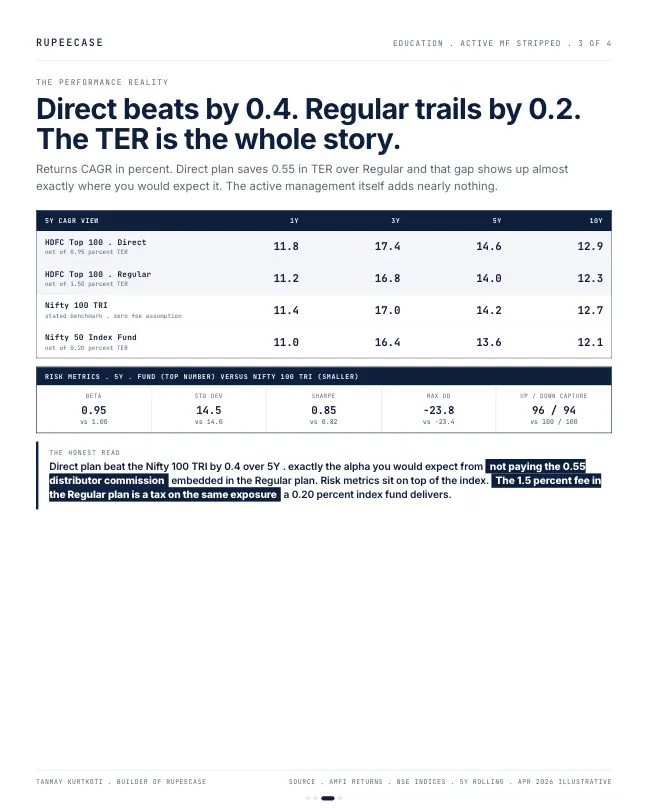
Performance reality over 5Y. Direct plan CAGR 14.6 percent. Regular plan 14.0. Nifty 100 TRI 14.2. The Direct plan beats the benchmark by 0.4 net of fees. The Regular plan trails by 0.2 net of fees. The 0.55 percentage point gap between Direct and Regular is the distributor commission baked into Regular . and that gap is the entire reason Regular trails. The active management itself adds almost nothing. Risk metrics sit on top of the index . Beta 0.95, Sharpe 0.85 versus the index 0.82, Max drawdown 23.8 percent versus index 23.4. The fee-stack laid side by side at rupeecase.com/compare
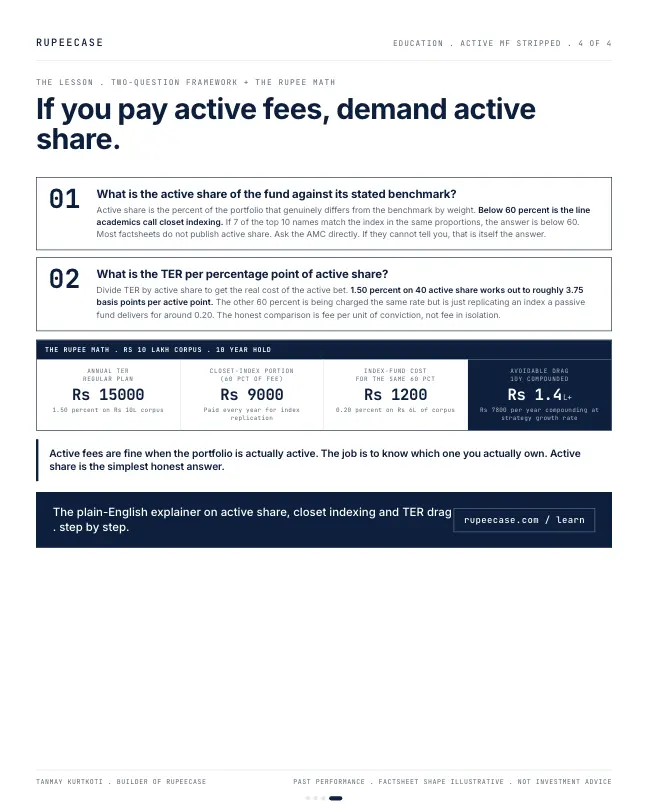
The rupee math. Rs 10 lakh held 10 years in the Regular plan pays Rs 15K in TER every year. 60 percent of that . roughly Rs 9K . is being paid for the closet-index portion that an index fund delivers for around Rs 1.2K. The compounded gap over a decade is more than Rs 1.4 lakh. That is the rupee cost of closet indexing.
Two questions worth running on any active fund before money goes in.
One. Active share against the stated benchmark? If 7 of the top 10 names match the index, the answer is below 60.
Two. TER per percentage point of active share? 1.50 on 40 active is 3.75 bps per active point. The other 60 percent is being charged the same rate but it is just replicating an index. The methodology behind a 60-plus active share rule-based picking system is open at rupeecase.com/strategies/methodology
There is a sharper way to read the same two numbers. If the 60 percent copy of the index could be bought for about 0.20 percent, the rest of the 1.50 fee is really being charged on the 40 percent slice that differs. Move the inputs and watch that hidden price.
At 40 percent active share the investor is paying about 3.45 percent a year for the part of the portfolio that is genuinely managed. Push active share to 80 and the same 1.50 fee prices that slice near 1.8 percent.
Closet indexing is not a moral failure. It is a fee structure problem. A genuinely active large-cap card with active share above 60 sits at rupeecase.com/strategies/focused-largecap-20 . And the behavioural-fit test that tells you whether you can hold any equity strategy through its drawdowns is at rupeecase.com/risk-profile
The full research-note dissection . anatomy, performance, cost structure, the rupee math, the two-question framework, what to do with this information . is in the deep-dive companion to this carousel.
If you pay active fees, demand active share.
What the rules say about the price tag
The fee in this post is not unusual, and it sits inside the ceiling SEBI sets. Under the expense ratio reset approved at the SEBI board meeting of 17 Dec 2025, the cap for an open ended equity scheme falls as the scheme grows, and statutory levies now sit outside the base figure.
Base cap, equity scheme up to Rs 500 crore
SEBI, PR No. 84/2025, 17 Dec 2025
Base cap, equity scheme above Rs 50,000 crore
SEBI, PR No. 84/2025, 17 Dec 2025
Base cap, index funds and ETFs
SEBI, PR No. 84/2025, 17 Dec 2025
The gap between the Direct and Regular plan is a separate story. Direct plans exist because a SEBI circular of 13 Sep 2012 required a separate plan with no distributor commission and its own NAV from 1 Jan 2013. Every rupee of the Regular plan's extra cost since then has been commission, which is why the two plans in this post differ by roughly the same amount every year.
Put the two questions together and the check takes five minutes with a factsheet and the index weights.
- Find the benchmarkThe index named in the scheme document, not the one in the advert.
- Compare the top tenSeven or more names at near index weights points to active share below 60.
- Price the active sliceFee minus the index cost on the copied part, divided by active share.
- Decide what you are paying forIf the slice costs 3 percent a year, it has to beat the index by more than that.
The free Learn module on index funds, ETFs and active funds runs the Indian evidence in full, and the note on why a star rating looks backwards covers the other number people buy on.
Questions readers ask
What is a good active share for a large cap fund?
The 2009 research behind the measure treats 60 percent and above as genuinely active and below 60 as closet indexing. Large cap funds tend to sit lower because the investable universe is narrow. The number matters most when you set it against the fee: 1.50 percent on 40 active points prices the active slice at about 3.45 percent a year.
Why does the Regular plan of a fund return less than the Direct plan?
Both plans hold the same portfolio. The Regular plan carries a distributor commission inside its expense ratio, and Direct plans, required by SEBI from 1 Jan 2013, do not. The return gap between the two is close to the difference in their expense ratios, every year.
The cards
6 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
Related
- Pull your CAS before you buy a seventh fundOne consolidated account statement showed six funds with 62 percent of the money in the same twelve stocks, Rs 12,800 a year of fees and Rs 72,000 of forgotten debt.Costs: MF, PMS, RupeeCase . . 6 min
- Star ratings are the rear view mirrorOnly about one in four top quartile funds is still there a few years later, which is what a coin flip sorted into four buckets would deliver.Costs: MF, PMS, RupeeCase . . 5 min
- The NAV mythRs 10,000 in a Rs 10 NAV fund and in a Rs 500 NAV fund with the same portfolio are worth the same Rs 11,000 after a 10 percent rise, because NAV is not a price.Costs: MF, PMS, RupeeCase . . 5 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.