

Costs: MF, PMS, RupeeCase..6 min read
The true cost stack of a regular plan
Stated TER, distributor commission and silent churn stack to about 178 basis points a year, and on Rs 10 lakh over five years that is closer to Rs 95,000 than Rs 17,000.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
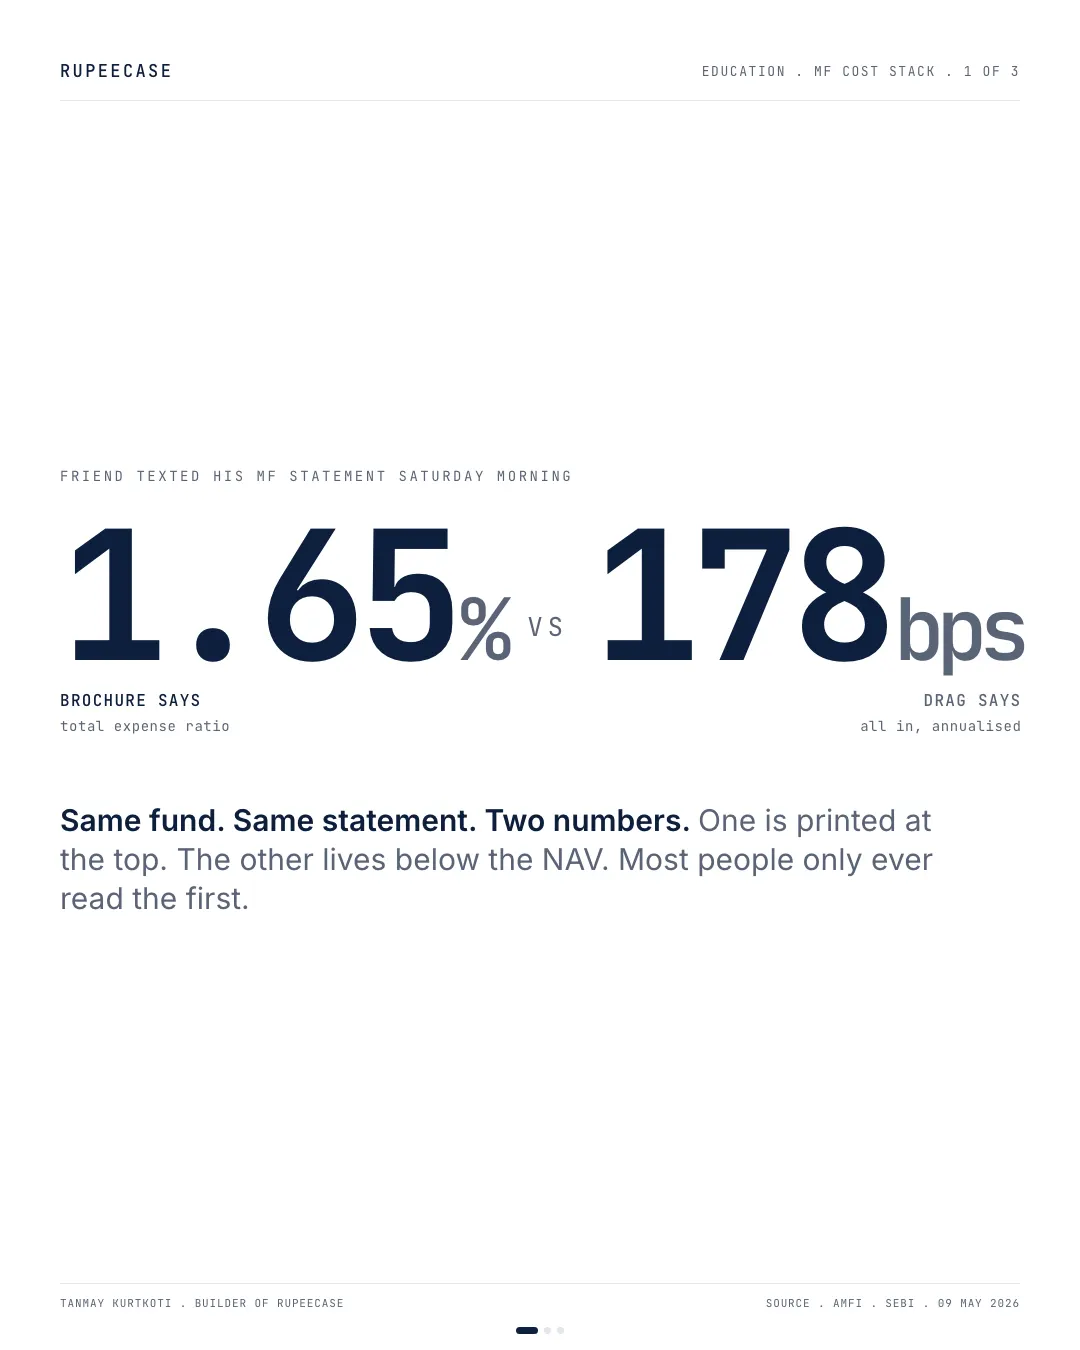
Friend texted his MF statement on Saturday morning. KIM at the top said TER 1.65 percent. He asked. Is that all I am paying. Honest answer is no. The receipt is always longer than the brochure.
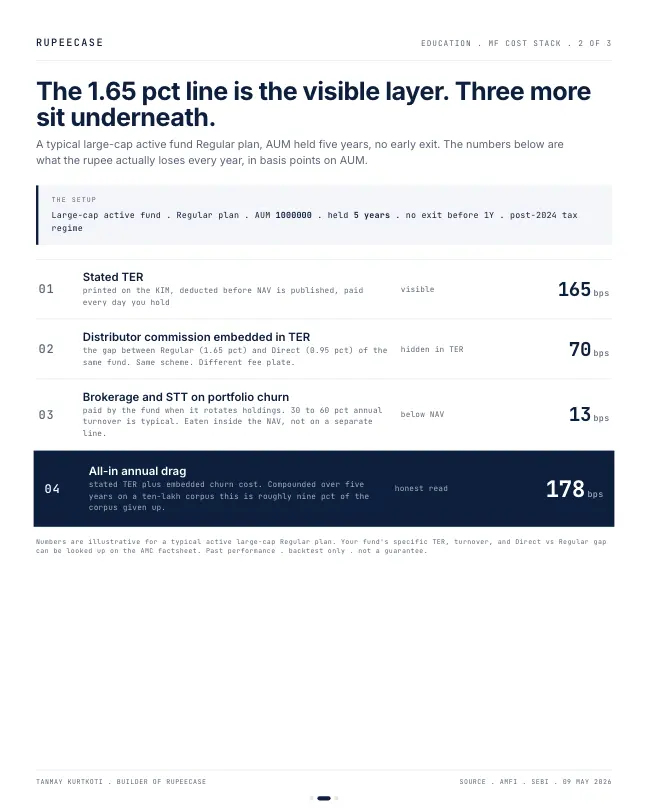
The stack on a typical large-cap active Regular plan has four lines, only one of which is printed where you can see it. Stated TER is 165 basis points. Deducted before NAV is published, paid every day you hold. That is the visible layer.
Below it sits the distributor commission. Pull up the Direct plan version of the exact same fund and you will see TER closer to 95 bps. The 70 bps gap is what your distributor is taking out of your money every year, baked into the price you signed up for. Same scheme. Same portfolio. Different fee plate.
Below that sits the silent layer. Active funds rotate 30 to 60 percent of holdings a year. Brokerage and STT on every rotation comes out of the NAV before you ever see it on a statement. Roughly 13 bps annual on a typical churn. No separate line. No invoice. Just slower compounding.
All-in drag lands close to 178 basis points a year for a Regular plan holder. The 1.65 percent on the brochure was always two-thirds of the real number.
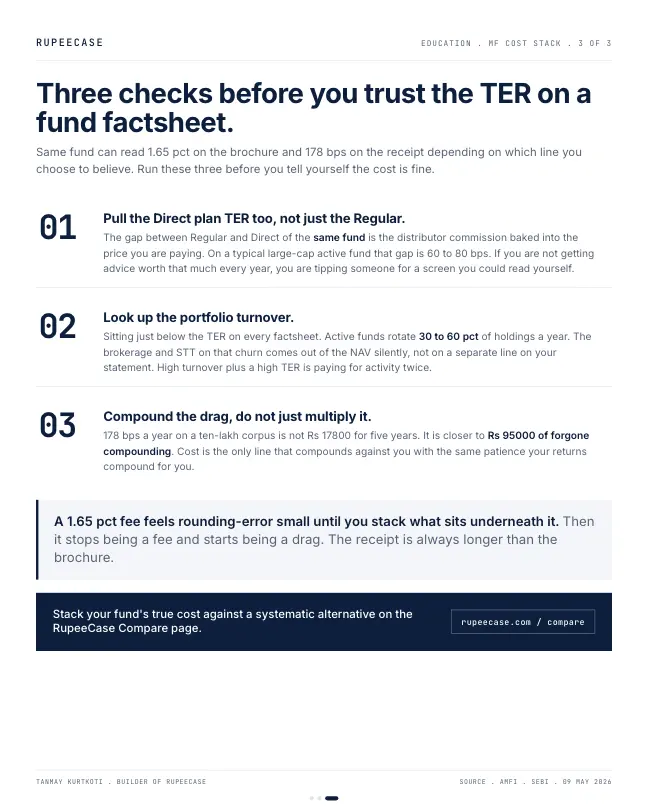
Three checks I run before I accept any fund's stated TER. Pull the Direct plan TER too. Look up the portfolio turnover, sitting just below the TER on every factsheet. And compound the drag, do not multiply it. 178 bps a year on a ten-lakh corpus over five years is not seventeen thousand. It is closer to ninety-five thousand of forgone compounding. Cost is the only line that compounds against you with the same patience your returns compound for you.
A 1.65 percent fee feels rounding-error small until you stack what sits underneath it. Then it stops being a fee and starts being a drag
Multiply or compound: the same fee, two answers
The last check in that list is the one most people skip, so here it is in full. Take Rs 10 lakh and a 12 percent gross return. The regular plan holder pays the 1.78 percent all in drag from the statement. A direct plan holder of the same scheme pays about 1.08 percent: a direct expense ratio near 0.95 plus the same 0.13 of churn, because the portfolio is identical.
Multiply the fee and it looks harmless: 1.78 percent of Rs 10 lakh is Rs 17,800 a year, Rs 89,000 over five years. Compound it and the picture changes, because every rupee taken this year would also have earned in all the years after.
- After 5 years7.7%
- After 10 years14.8%
- After 20 years27.4%
Share of the no cost end value lost to a 1.78% yearly drag, Rs 10 lakh at 12% gross. Worked example with a fixed yearly return.
In rupees: after five years the cost free value would be about Rs 17.62 lakh and the regular plan ends near Rs 16.27 lakh, a gap of about Rs 1.36 lakh. After ten years it is Rs 31.06 lakh against Rs 26.46 lakh. After twenty years, Rs 96.46 lakh against Rs 70.02 lakh: Rs 26.45 lakh gone, more than two and a half times the original cheque. The exact figure depends on the return you assume, which is why I always run it rather than quote it.
The commission line on its own
The distributor layer is the part of the stack you can change without changing the fund. Run the same money in the direct plan at 1.08 percent and twenty years ends near Rs 79.47 lakh. That is Rs 9.45 lakh more than the regular plan, for the same portfolio, the same manager and the same risk.
Switching plans is not free, and I would not pretend it is. Moving from regular to direct counts as a redemption. Gains on equity units held more than 12 months are taxed at 12.5 percent above Rs 1.25 lakh a year; inside 12 months at 20 percent, with any exit load on top. The switch math has to clear that bill first, which is why it usually makes the most sense on units already past a year, or on fresh money.
Where each line now shows up
My friend's statement was printed under the old fee rules, when the churn line had no home. That has changed. At its board meeting of 17 Dec 2025 SEBI decided that the fee cap, renamed the base expense ratio, excludes statutory levies, and that the total expense ratio is the sum of the base ratio, brokerage, regulatory levies and statutory levies. So a part of the silent layer now has to sit inside the TER you read.
- Base expense ratioThe AMC's fee and the distributor commission. Lower in the direct plan.
- Brokerage and leviesSTT, stamp duty, exchange and SEBI fees on the fund's trades, now added to the TER at actuals.
- TurnoverPrinted on the factsheet next to the TER. More turnover, more of line two.
- Half yearly CASShows your plan's average TER and the commission paid on your money, in rupees.
The CAS line is the one I would read first. SEBI's circular of 20 Sep 2016 requires the half yearly statements, for the periods ending September and March, to show the gross commission paid to your distributor against each scheme you hold, in absolute rupees. It turns the 70 basis points in the opening into a figure with your name on it.
The free Learn module on mutual fund structure and hidden costs covers plans, categories, expense ratios and exit loads with a quiz, and the fee drag calculator runs any fee over any horizon. For the stack built up from the factsheet side, read the mutual fund cost stack.
Questions readers ask
How much does a 1 percent higher expense ratio cost over 20 years?
On Rs 10 lakh at a 12 percent gross return, the difference between a 1.08 and a 1.78 percent yearly cost is about Rs 9.45 lakh after twenty years, Rs 79.47 lakh against Rs 70.02 lakh. The gap grows faster than the years because the fee compounds the same way the return does.
Is switching from a regular plan to a direct plan taxable?
Yes. A switch between plans is treated as a redemption and a fresh purchase. Equity fund units held more than 12 months are taxed at 12.5 percent on gains above Rs 1.25 lakh in the year; units held less than 12 months at 20 percent, and an exit load may apply.
Why is the direct plan NAV higher than the regular plan NAV?
Both plans hold the same portfolio, but the regular plan pays a distributor commission out of its assets every day. Over the years that higher expense ratio compounds into a lower NAV, so the direct plan's NAV ends higher even though the stocks are the same.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
- StrategyAllcap strategyNifty Total Market, 50 stocks, every 2 weeks
- CalculatorSIP calculatorFree, with the formula and a worked example
- Free module 6.3Mutual Funds, Structure, Types and Hidden Costs8 min read
- CalculatorFee drag over 20 yearsFree, with the formula and a worked example
- Blog topicCosts: MF, PMS, RupeeCase notes25 notes
Reading path
Stop 2 of 8 on The cost stack
Related
- The mutual fund cost stackA 1.65 percent TER is only the visible line; add churn, cash drag and the regular plan commission and the honest annual cost of an active large cap fund is near 178 basis points.Costs: MF, PMS, RupeeCase . . 6 min
- A 1 percent fee does not cost you 1 percentOn Rs 10 lakh at 12 percent gross for 25 years a 1.00 percent fee costs 20.1 percent of the ending corpus, and more than half of that is charged in the last five years.Costs: MF, PMS, RupeeCase . . 13 min
- Two week rebalancing and the STCG objectionA 60 percent higher short term tax rate loses to a 192 percent higher gross return, so compare after tax cheques on the same corpus rather than tax brackets.Costs: MF, PMS, RupeeCase . . 6 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.