

Returns and risk maths..4 min read
Rule of 72: count in doublings
Rs 10 lakh for thirty years becomes about Rs 3 crore at 12 percent and Rs 1 crore at 8, because four points deletes close to two doublings.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
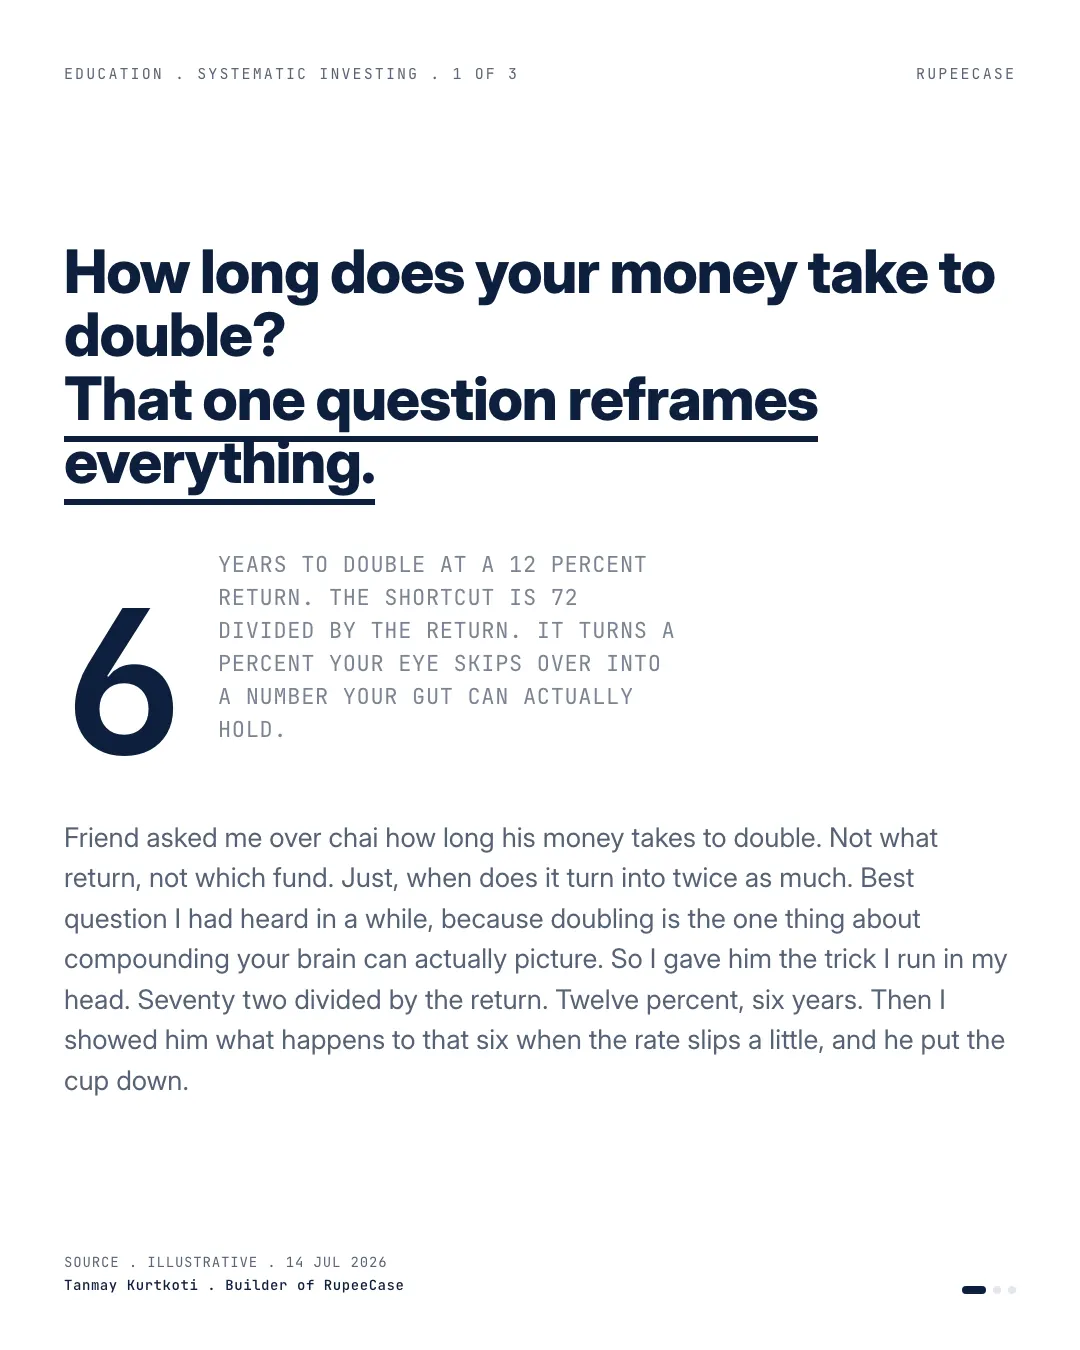
A friend asked me over chai how long his money takes to double.
Not what return he should chase. Not which fund. Just, when does it turn into twice as much. It is the best question I have heard in a while, because doubling is the one thing about compounding your brain can actually picture. A percent slides right past you. "Twice as much" does not.
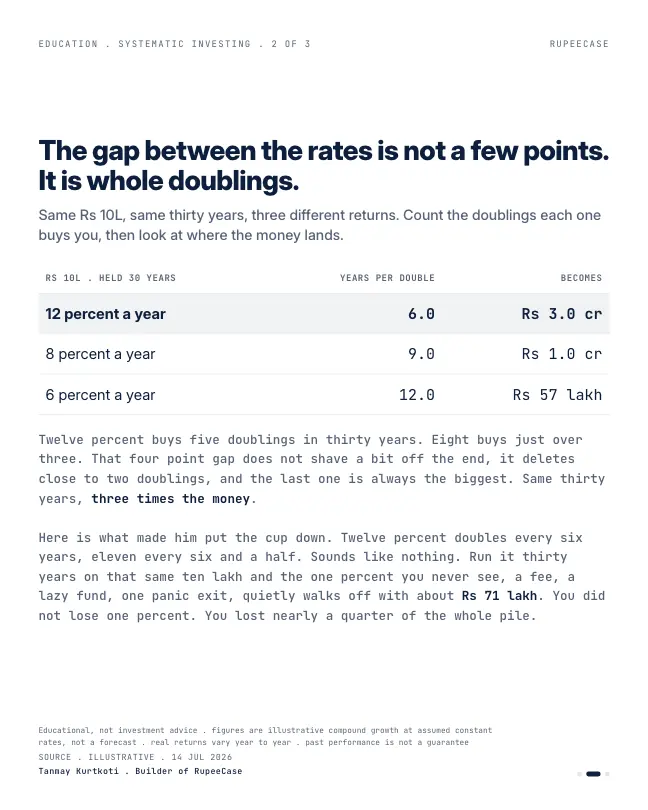
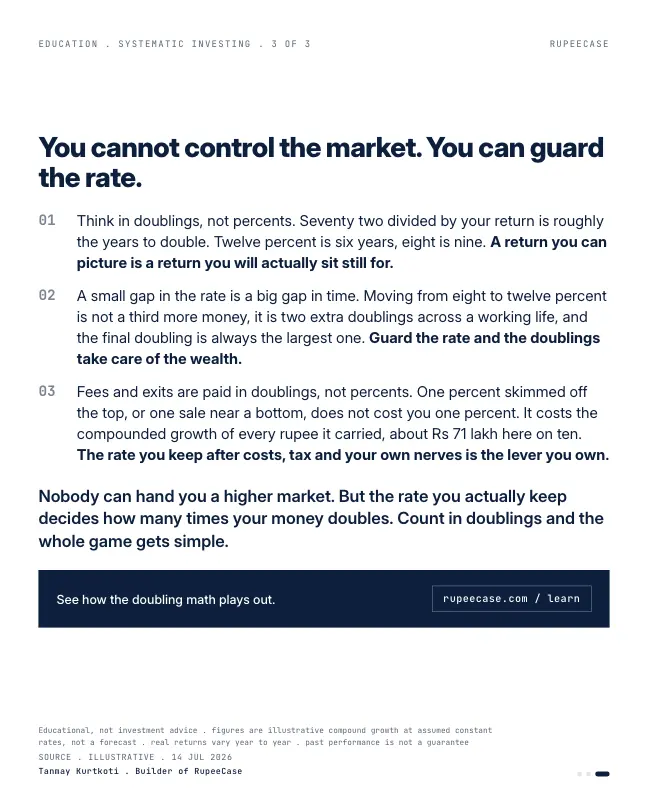
So I gave him the shortcut I run in my head. 72 divided by your return is roughly the years to double. At 12 percent, money doubles every 6 years. At 8, every 9. At 6, every 12.
Then we did the part that matters. Take Rs 10 lakh and leave it for thirty years. At 12 percent it becomes about Rs 3 crore. At 8, about Rs 1 crore. At 6, roughly Rs 57 lakh. Same money, same three decades.
Look at what that gap actually is. 12 percent buys you five doublings in thirty years. 8 percent buys just over three. The four points between them do not trim a little off the end, they delete close to two doublings, and the last doubling is always the biggest one you ever get.
Here is what made him put the cup down. Shave 12 down to 11, a fee you never notice, one lazy fund, a single panic exit, and about Rs 71 lakh quietly walks off that same ten lakh over thirty years. You did not lose one percent. You lost nearly a quarter of the whole pile.
That is the whole lesson for me. Nobody can hand you a higher market. But the rate you actually keep, after costs, after tax, after your own nerves, decides how many times your money doubles. Count in doublings and investing gets a lot simpler.
The ladder, drawn
At 12 percent, Rs 10 lakh doubles about every six years. Thirty years gives five rungs. Here is what each rung adds.
The exact figure at 30 years is Rs 10,00,000 x 1.12 ^ 30 = about Rs 3.0 crore, a little below the 320 on the ladder because 12 percent doubles in 6.1 years, not exactly 6. The shape is the lesson. Each rung is as big as everything below it. Lose a rung at the end and you lose half the pile.
How many doublings each rate buys
Count doublings over the same thirty years. The exact count is 30 x ln(1 + rate) / ln 2.
- 6%: Rs 57 lakh2.52
- 8%: Rs 1.01 crore3.33
- 11%: Rs 2.29 crore4.52
- 12%: Rs 3.00 crore4.90
Doublings of Rs 10 lakh in 30 years at a fixed rate. Arithmetic, not a forecast.
Twelve against eleven is 4.90 doublings against 4.52. That 0.38 of a doubling, at the very end of the ladder, is the Rs 71 lakh from the opening: Rs 3.00 crore against Rs 2.29 crore.
How good is the shortcut?
Rule of 72 is an approximation. The exact doubling time is ln 2 divided by ln(1 + rate). Try a few rates and compare.
Between about 6 and 12 percent the shortcut is within a fraction of a year. At 8 percent it is almost exact: 9.00 against 9.01. At 24 percent it says 3.00 years and the truth is 3.22. For high rates, 72 runs a little fast.
The same clock runs on prices
Doubling is not only about growth. It works on anything that compounds, including the cost of living.
CPI inflation, Aug 2026
MOSPI, 14 Sep 2026
years for prices to double at that pace
ln 2 / ln 1.0482
years to double at the 9.8% Nifty 50 TRI reference line
lineup.json, smoothed. Model, back tested, as of 27 Apr 2026
At the Aug 2026 inflation rate of 4.82 percent, prices double in about fifteen years. So a rupee that doubles every fifteen years is only standing still. What matters is how many doublings you get above that line, after costs and tax. That is why I keep coming back to the costs side of a portfolio. Nobody controls the market's rate. Expense ratios, turnover and tax are the parts you can actually read before you start.
The free Learn module on mutual fund structure and costs shows how expense ratios and plan choice change what compounds, with quizzes and a certificate. A related trap, quoting returns from a lucky start date, is in the since inception trap.
Questions readers ask
How accurate is the rule of 72?
Very close between about 6 and 12 percent: at 8 percent it gives 9.00 years against an exact 9.01. At higher rates it runs a little fast, for example 3.00 years against 3.22 at 24 percent. The exact time is ln 2 divided by ln(1 + rate).
How long does it take money to double at 12 percent?
About 6.1 years exactly, or 6 years by the rule of 72. Over thirty years that is close to five doublings, which turns Rs 10 lakh into about Rs 3 crore at a fixed 12 percent.
Why does a 1 percent difference in return matter so much?
Because it changes how many doublings fit in the time you have, and the last doubling is the largest. Over thirty years, 12 percent against 11 percent is about 0.38 of a doubling, which on Rs 10 lakh is about Rs 71 lakh.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
Related
- The first crore is the slowestA flat Rs 10,000 SIP at 12 percent takes about 20 years to the first crore, 5 more to the second and 3 to the third, with 72 percent of the final pot arriving in the last decade.Personal finance and tax . . 5 min
- The cost of waiting: start small, start nowA saver who invested Rs 10,000 a month from 25 to 35 and stopped ends with Rs 4.6 crore at 60, ahead of one who invested from 35 to 60, because time did the work.Personal finance and tax . . 5 min
- The since inception trapA six year old fund's 18.9 percent since inception rode a 75 percent birth year; on the same five years it did 10 against the fifteen year old fund's 13.Returns and risk maths . . 5 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.