

Personal finance and tax..4 min read
The flat rate trap
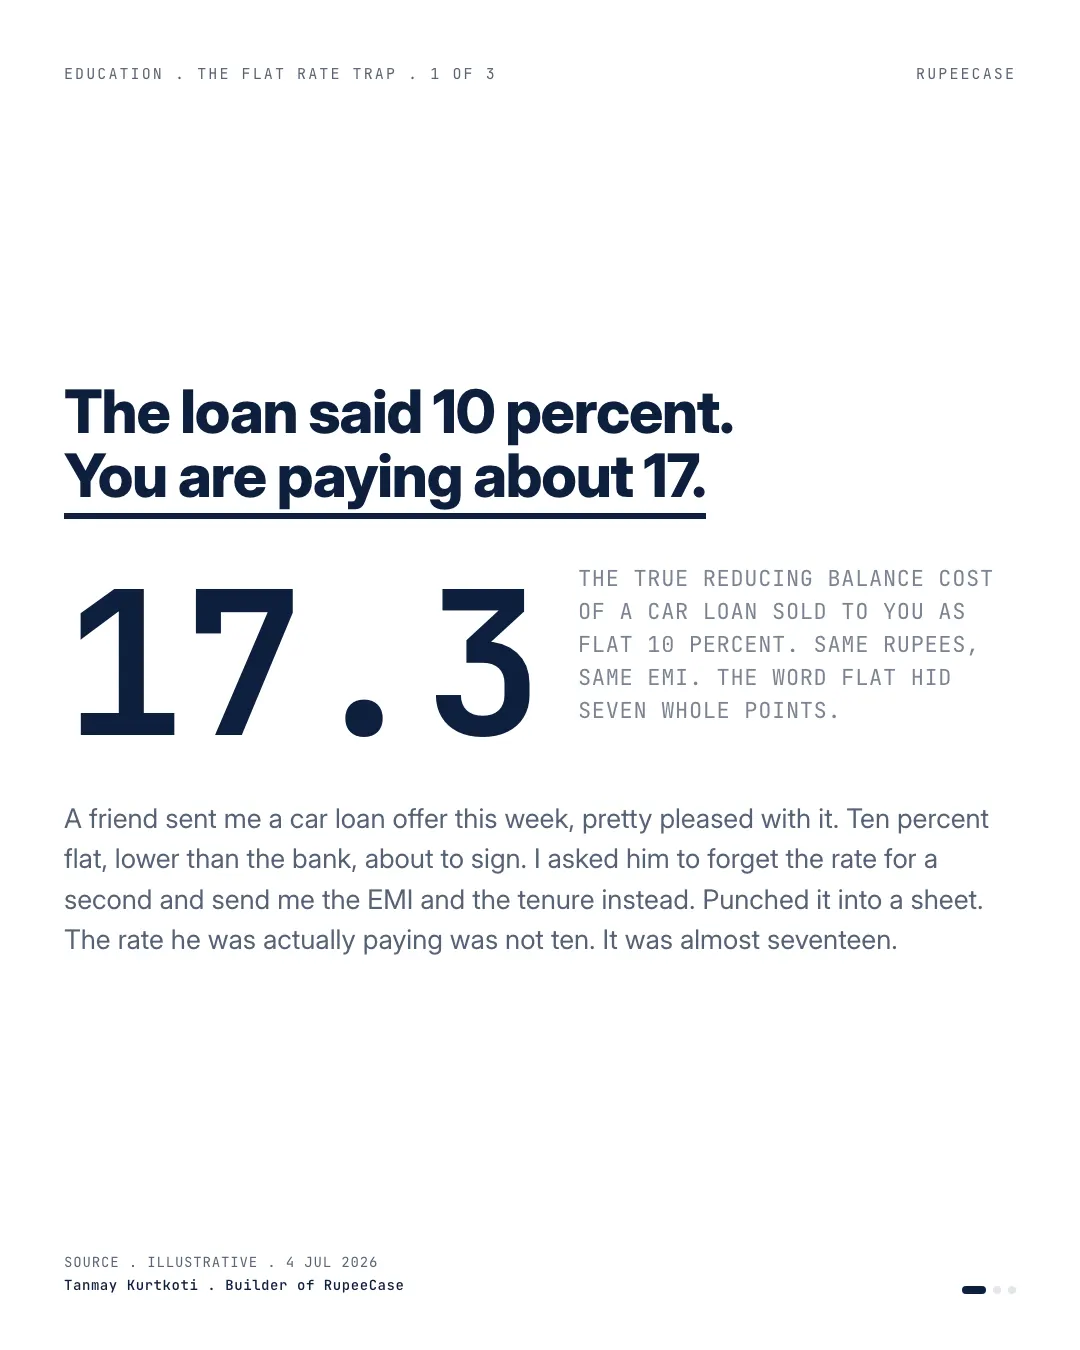
A 10 percent flat car loan on Rs 6 lakh over five years costs Rs 1,35,000 more than a 10 percent reducing balance loan, a true rate near 17.3 percent.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
A friend sent me a car loan offer this week, pretty pleased with it. Ten percent flat, he said. Lower than the bank's rate, so he was about to sign.
I asked him to ignore the rate for a second and send me two numbers instead. The EMI and the number of months.
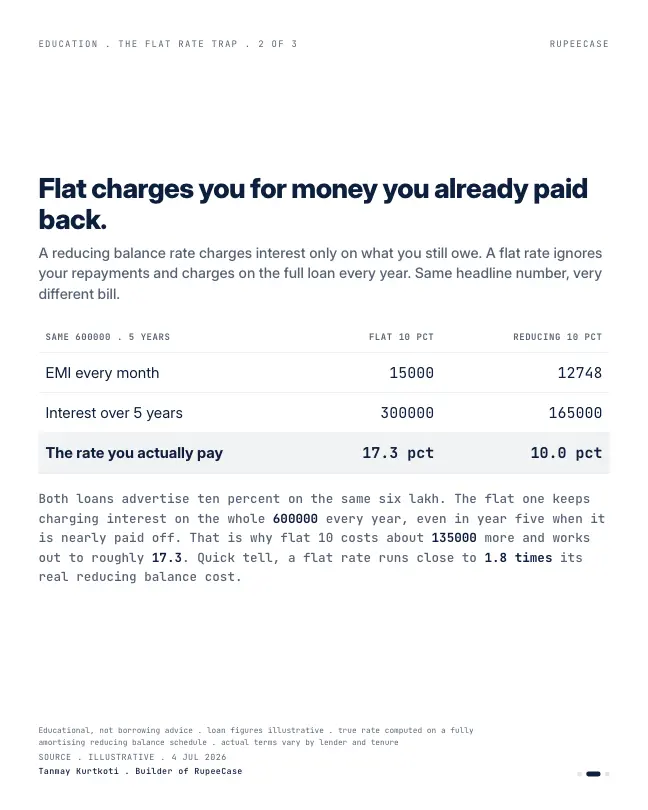
Here is what the word flat does. On a normal loan, interest is charged on what you still owe. Pay some back, you owe less, you are charged less. A flat rate ignores that. It charges interest on the entire original loan every year of the tenure. Even in the final year, when you have handed back almost all the principal, you are still paying as if the full amount were outstanding.
Run his numbers. Six lakh, five years, ten percent flat. That is 3,00,000 in interest and an EMI of 15,000. Now price the same six lakh at a genuine ten percent reducing balance. The interest is about 1,65,000 and the EMI is 12,748.
Same loan. Same advertised rate. The flat version costs 1,35,000 more, and the true rate you are paying works out to roughly 17.3 percent, not ten.
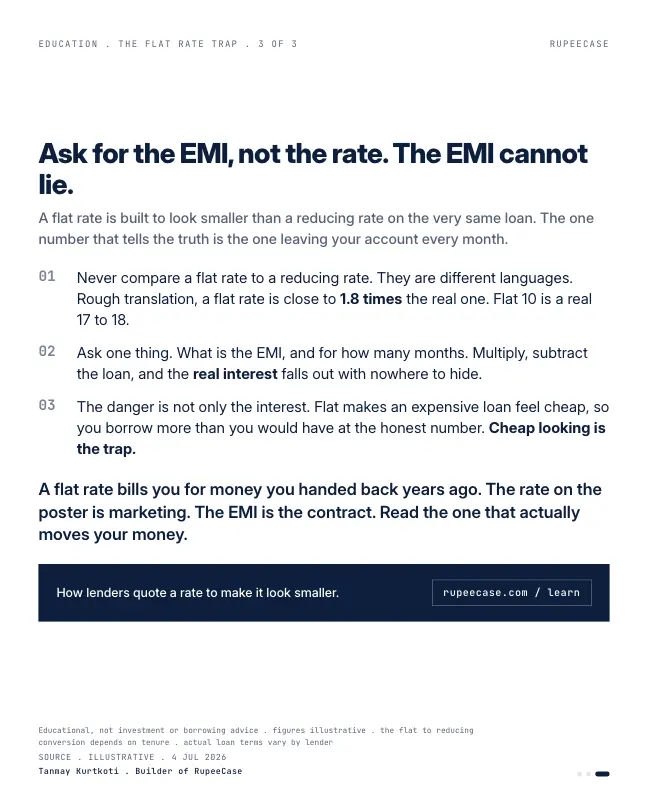
A quick tell for anyone comparing offers. A flat rate runs close to 1.8 times its real reducing balance cost. So a flat 10 is really a 17 to 18. If a lender quotes flat and a bank quotes reducing, you are not comparing two rates, you are comparing two languages.
The fix is one question. What is the EMI and for how many months. Multiply the two, subtract the loan, and you have the real interest no sticker can hide.
The rate on the poster is marketing. The EMI is the contract. Read the one that actually moves your money.
What the flat rate charges interest on
The whole trick fits in one picture. On a reducing balance loan, the amount you owe falls with every EMI, and so does the interest. A flat rate keeps charging on the starting amount for all five years.
On average over the five years, a reducing balance loan has only a little over half the principal outstanding. A flat rate charges on all of it. That is why the true rate comes out close to double the quoted one.
The two loans, side by side
- Interest, 10% flatRs 3,00,000
- Interest, 10% reducingRs 1,64,894
Worked example: Rs 6 lakh, 60 monthly EMIs. Flat EMI Rs 15,000; reducing balance EMI Rs 12,748.
I checked the opening's true rate: an EMI of Rs 15,000 for 60 months on Rs 6 lakh is the same cash flow as a reducing balance loan at about 17.27 percent a year. The 1.8 times rule is a good tell, and it drifts a little with the rate. On the same loan, a flat 8 percent works out to about 14.1 percent reducing, 1.77 times, and a flat 12 percent to about 20.3 percent, 1.69 times.
Flat quotes tend to show up where the loan is sold at the point of purchase: vehicles, consumer durables, some personal and education loans offered through a dealer or an app. The EMI is usually what the buyer is asked to approve, and the rate is a sales line. That is why the opening's fix works everywhere. The EMI and the number of months are in the contract, and from those two numbers the real interest and the real rate follow without any help from the lender.
Check any offer yourself
The disclosure that settles it
Regulation now gives you the number directly. The RBI's circular on the Key Fact Statement for loans, issued on 15 Apr 2024 and applicable to new retail and MSME term loans from 1 Oct 2024, requires lenders it regulates to give borrowers a standard summary before the loan is signed. It includes the annual percentage rate, the all in cost of the loan on a yearly basis, along with the repayment schedule. A flat 10 percent quote and a 17 percent annual percentage rate on the same page cannot both pass unnoticed.
MythA 10 percent flat rate is cheaper than an 11 percent bank loan.
FactOn a five year loan, 10 percent flat is about 17.3 percent reducing balance. Compare the annual percentage rate on the Key Fact Statement, or the EMI and months.
The free Learn module on leverage, debt and financial risk treats a household loan the way an analyst treats a company's debt, with the same coverage questions. Related: prepay the loan or invest and the minimum due trap.
Questions readers ask
What is the difference between flat and reducing interest rate?
A flat rate charges interest on the original loan amount for the whole tenure. A reducing balance rate charges interest only on what you still owe. On Rs 6 lakh over five years at 10 percent, the flat version costs Rs 3,00,000 in interest and the reducing version about Rs 1,64,894.
How do I convert a flat rate to an effective interest rate?
Work out the EMI and number of months, then find the reducing balance rate that gives the same EMI. As a quick estimate, a flat rate is about 1.7 to 1.8 times as costly as the same reducing rate on a five year loan: 10 percent flat is about 17.3 percent.
What is the annual percentage rate in a loan Key Fact Statement?
It is the all in yearly cost of the loan, including interest and charges, which the RBI's Key Fact Statement rules require regulated lenders to show before you sign. It lets you compare loans quoted in different ways.
The cards
3 cards. Swipe, or tap to open.
Related
- Rent vs buy: the two numbers the dead money line skipsMore than 80 paise of a first year EMI rupee is interest, rent runs about 3.5 percent of price against an 8.5 percent loan, and the down payment has an opportunity cost.Personal finance and tax . . 5 min
- The minimum due trapPaying only the minimum on a Rs 1 lakh card balance takes 341 months and Rs 3,72,861 of interest, because 3.5 percent a month plus GST is 4.13 percent a month.Personal finance and tax . . 6 min
- Prepay or invest: the schedule decidesA Rs 5 lakh prepayment in month 12 of a Rs 50 lakh loan kills Rs 21.04 lakh of interest, and investing it still wins by about Rs 6 lakh at a post tax 9.36 percent.Personal finance and tax . . 13 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.