

Personal finance and tax..5 min read
Prepay the loan or invest: the ITR decides
With the Section 24 deduction and LTCG stripped out, the prepay or invest call lives in the gap between the post tax loan cost and the post tax equity return.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
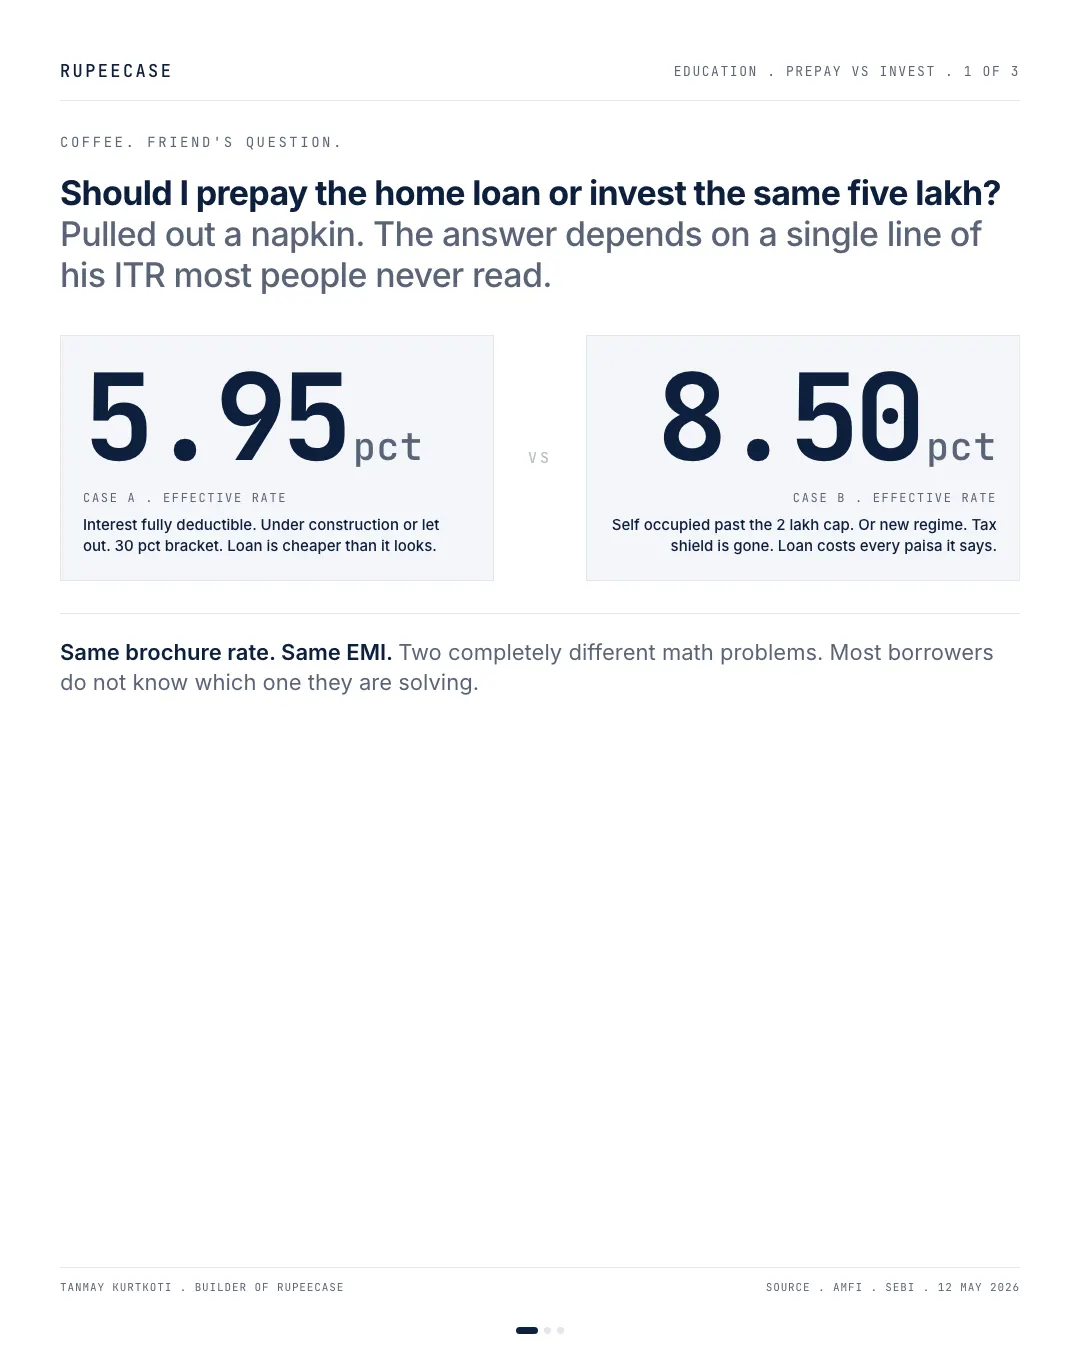
Friend asked over coffee whether to prepay his home loan or invest the same five lakh instead. The instinct from every fund app he opens says invest. The instinct from his father says prepay. Pulled out a napkin.
The right answer depends on one line of his ITR most people never read.
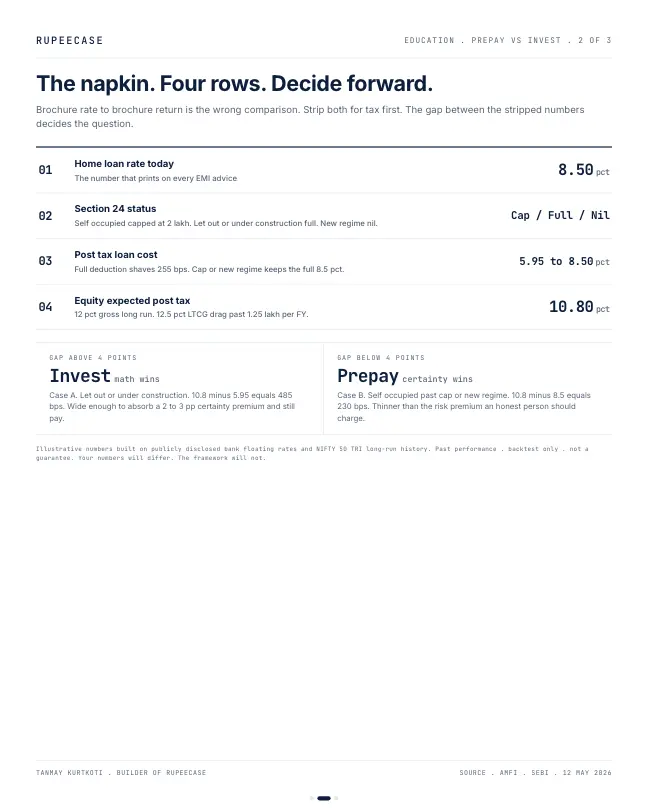
The napkin has four rows.
Row one is the loan rate. 8.5 pct floating on the statement. The number everyone quotes when they have this conversation.
Row two is the Section 24 status. Self occupied past the 2 lakh interest cap loses the marginal tax shield. Under construction or let out keeps the full deduction. New regime gives up the deduction entirely. One line on the ITR, and the same loan becomes a cheap loan or an expensive one.
Row three is the post tax loan cost. Full deduction in a 30 pct bracket shaves 255 basis points off. So the brochure 8.5 pct becomes a true 5.95 pct in Case A. Capped or new regime keeps the whole 8.5 pct in Case B. Same EMI, two different math problems.
Row four is the equity number stripped the same way. 12 pct long run nominal is the headline. Strip 12.5 pct LTCG on gains past the 1.25 lakh annual exemption and the honest expected is closer to 10.8 pct.
The decision sits in the gap between row three and row four. Above 4 percentage points, the equity premium pays for the variance. Below 4, you are giving up certainty for a margin that does not exist.
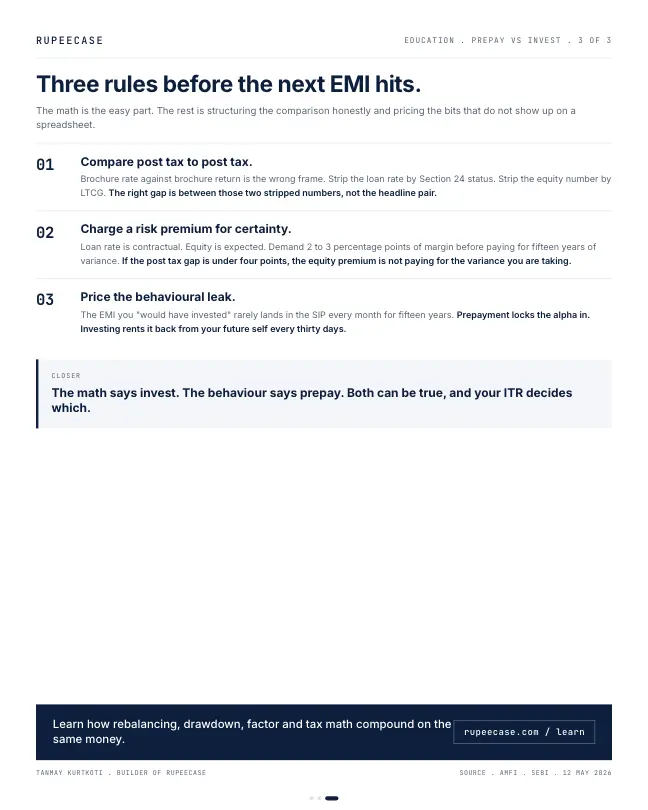
Then there is the part the spreadsheet misses. The EMI you "would have invested" rarely lands in the SIP every month for fifteen years. Prepayment locks the alpha in. Investing rents it back from your future self every thirty days.
The math says invest. The behaviour says prepay. Both can be true, and your ITR decides which
What row two says in the 2026 law
Row two has a new address. From 1 Apr 2026 the Income-tax Act 2025 replaced the 1961 Act, and the old section 24 deduction for interest on a home loan now sits in section 22 of the new Act. The Finance Bill 2026 memorandum confirms that section 22(2) keeps the Rs 2 lakh ceiling on interest for a self occupied house bought or built with borrowed money.
Three details decide which case you are in.
- Which regimeThe new regime is the default. Under it, interest on a self occupied home is not deductible at all.
- Self occupied or let outOld regime, self occupied: interest deductible up to Rs 2 lakh a year. Let out: interest is set against the rent without that cap.
- Above or below the capSelf occupied and already paying more than Rs 2 lakh of interest: the next rupee of interest saves no tax.
- Loss from the houseA let out house that shows a loss can reduce other income by at most Rs 2 lakh a year in the old regime; the rest is carried forward.
The last row tempers the opening's "keeps the full deduction" for let out property. Interest is deductible against the rent, but if that produces a loss, only Rs 2 lakh of it can be set against salary in a year. For a big loan on a modestly rented flat, the marginal rupee of interest may still save tax only in a later year, which makes it worth less today.
The four rows, side by side
Here is the napkin as a chart, using the opening's figures. Case A is a loan whose marginal interest is fully deductible at the 30 percent slab. Case B is a self occupied loan already over the Rs 2 lakh cap, or any self occupied loan in the new regime.
- Loan, Case A after tax5.95%
- Loan, Case B after tax8.50%
- Equity after LTCG10.80%
Worked example from the opening. 30% slab before cess; 12% gross equity return with 12.5% LTCG above Rs 1.25 lakh a year (rates from 23 Jul 2024, unchanged under the Income-tax Act 2025).
Case A leaves a gap of 4.85 points between the expected equity return and the loan's real cost. Case B leaves 2.3 points. On the opening's 4 point rule, Case A leans to investing and Case B to prepaying. The rule is a judgment about how much extra expected return you want for taking equity risk, not a law. The useful part is knowing which case you are in before you argue about it.
Run your own napkin
The equity line is an assumption, not a promise. Equity can return far less than 10.8 percent over a decade, or lose money in a five year stretch. The loan rate, once you know your case, is close to certain for as long as it stays fixed.
The loan rate moves with the repo rate
The opening calls the 8.5 percent floating. Since Oct 2019, the RBI has required new floating rate home loans from banks to be linked to an external benchmark, most often the RBI repo rate. The repo rate was 5.50 percent after the RBI policy of 7 Oct 2026, a 25 basis point increase. A floating home loan linked to repo moves with each such change at its next reset.
MythEvery home loan is cheap after tax because of the interest deduction.
FactOnly if the next rupee of interest is deductible. In the new regime, or above the Rs 2 lakh cap on a self occupied home, the post tax cost equals the full loan rate.
The free Learn module on leverage, debt and financial risk treats debt the way an analyst treats a company's balance sheet, with coverage ratios that work for a household too. The capital gains tax calculator shows what row four looks like on your own gains. Related: the flat rate trap and rent against buy.
Questions readers ask
Can I claim home loan interest in the new tax regime?
Not for a self occupied home. The e-filing portal's FAQ says interest on borrowed capital for a self occupied property is not allowed under the new regime. Under the old regime the deduction is capped at Rs 2 lakh a year, now in section 22 of the Income-tax Act 2025.
Should I prepay my home loan or invest?
Compare the loan's after tax cost with an after tax equity return you are willing to assume. If the next rupee of interest saves no tax, an 8.5 percent loan costs 8.5 percent; if it is fully deductible at the 30 percent slab, about 5.95 percent. How confident you are that the money will really stay invested matters too.
What is the section 24 limit on home loan interest?
For a self occupied house under the old regime, interest is deductible up to Rs 2 lakh a year. From 1 Apr 2026 the same limit sits in section 22(2) of the Income-tax Act 2025.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
- Free module 11.1Equity Taxation After July 2024: The New Rules10 min read
- StrategyAllcap strategyNifty Total Market, 50 stocks, every 2 weeks
- Free module 9.4Leverage, Debt and Financial Risk10 min read
- CalculatorLTCG and STCG on equityFree, with the formula and a worked example
- Blog topicPersonal finance and tax notes24 notes
Related
- The flat rate trapA 10 percent flat car loan on Rs 6 lakh over five years costs Rs 1,35,000 more than a 10 percent reducing balance loan, a true rate near 17.3 percent.Personal finance and tax . . 4 min
- Rent vs buy: the two numbers the dead money line skipsMore than 80 paise of a first year EMI rupee is interest, rent runs about 3.5 percent of price against an 8.5 percent loan, and the down payment has an opportunity cost.Personal finance and tax . . 5 min
- The minimum due trapPaying only the minimum on a Rs 1 lakh card balance takes 341 months and Rs 3,72,861 of interest, because 3.5 percent a month plus GST is 4.13 percent a month.Personal finance and tax . . 6 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.