

Costs: MF, PMS, RupeeCase..5 min read
The base rate of beating the market
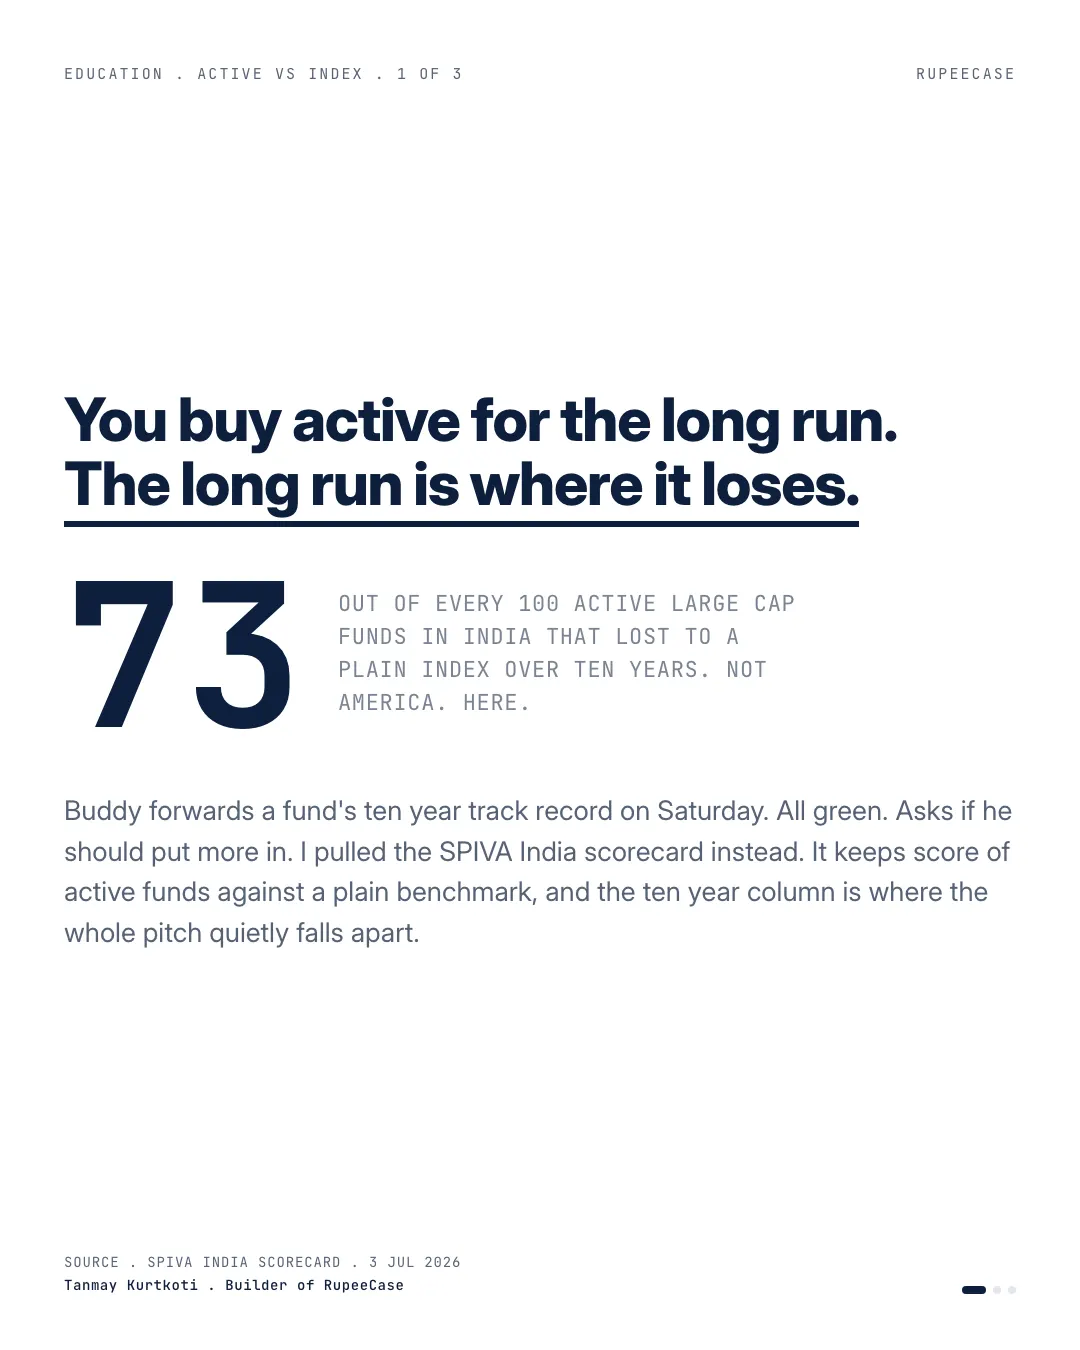
SPIVA India shows 73 of 100 active large cap funds and 82 of 100 mid and small cap funds trailed their benchmark over the ten years to June 2025.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
A friend forwarded me a fund's ten year track record on Saturday. Every year green. He wanted to know if he should put more in.
I did not look at his fund. I pulled the SPIVA India scorecard instead.
SPIVA keeps score of active funds against a plain benchmark. Over the ten years to June 2025, 73 out of every 100 active large cap funds in India lost to that benchmark. Not in America, where everyone quotes this number. Here.
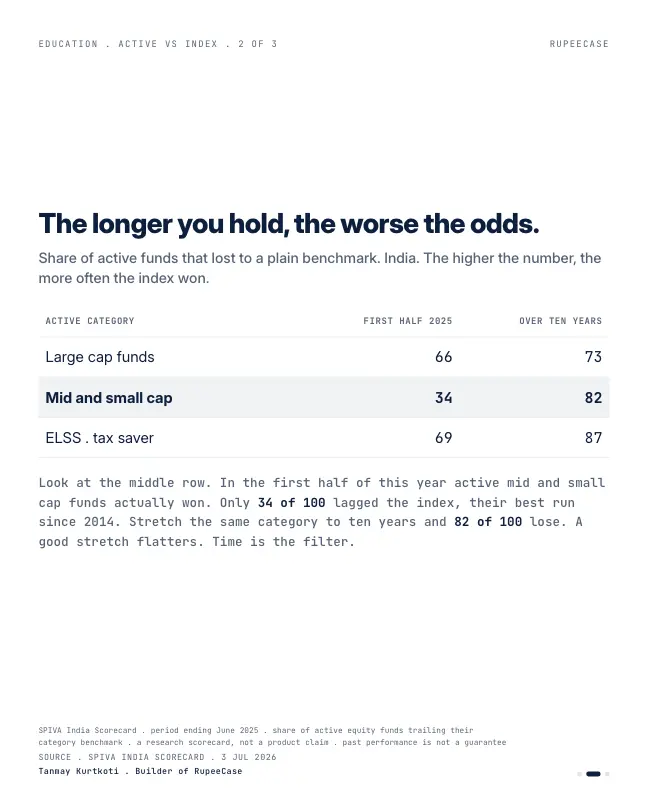
The reflex is to say large caps are efficient, so go active in the smaller names where a manager can actually dig. Fine. Look at the smaller names. Over the same ten years, 82 out of 100 mid and small cap funds lost too. Tax saving ELSS funds, 87 out of 100.
Now the part that fools people. In the first half of this year, active mid and small cap funds actually won. Only 34 of 100 lagged the index, their best run since 2014. Screenshot that window and active looks brilliant. Stretch the same category to ten years and 82 of 100 lose. A short window flatters. Time is the filter that separates a good stretch from a good process.
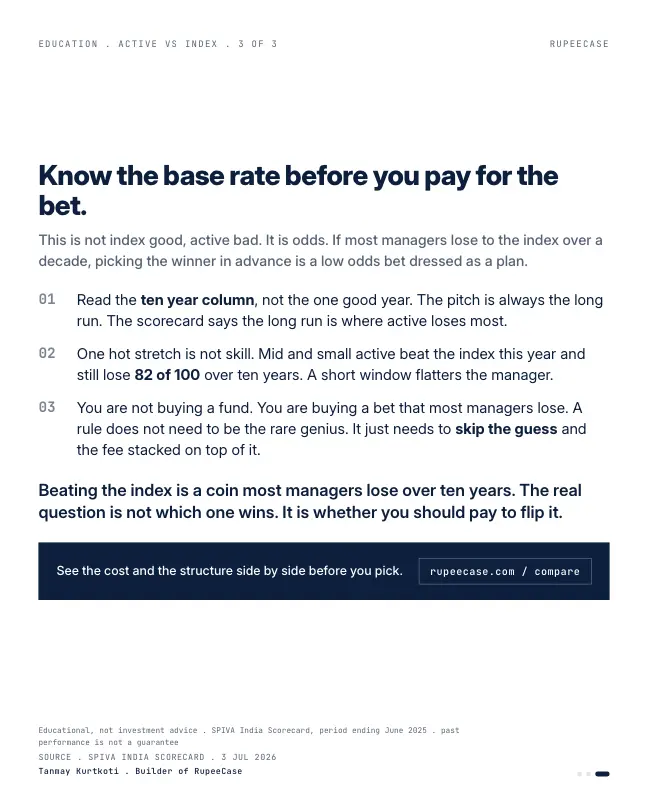
I want to be careful here. This is not index good, active bad. Plenty of excellent managers exist. It is a question of odds. If roughly three out of four lose to a plain benchmark over a decade, then "I will pick the winner in advance" is a low odds bet, not a plan.
That is the whole case for a rules based approach. A rule does not have to be the rare genius manager. It just has to skip the guess, and the fee stacked on the guess.
Beating the index is a coin most managers lose over ten years. The real question is not which one wins. It is whether you should pay to flip it.
Why the base rate leans against active
There is a piece of arithmetic behind those scorecard numbers that needs no data at all. Every share in the Nifty 50 is owned by someone. Add up all the investors who own the index's stocks, and before costs their average return is the index return, because together they are the index.
- All investorsTogether they own the whole market and earn its return.
- Passive partHolds the index. Earns the index, minus a small fee.
- Active partBefore costs, must also average the index return.
- After costsThe average active rupee trails by its fees and trading.
Some active managers will beat the index in any period. The arithmetic only says that, on average and after costs, they cannot all do it. The higher the fee, the larger the share that falls short. That is why the base rate reads worse over ten years than over one: the fee is charged every year, while luck tends to even out.
The benchmark you would have had to beat
SEBI has required mutual funds since 2018 to show their returns against the total return version of their benchmark, the version that includes dividends. So the bar is not the price index on a news ticker. It is this:
Nifty 50 TRI, a year over five years
NSE Indices factsheet, 30 Sep 2026
Nifty Midcap 150 TRI, a year over five years
NSE Indices factsheet, 30 Sep 2026
Nifty Smallcap 250 TRI, a year over five years
NSE Indices factsheet, 30 Sep 2026
Those five years to 30 Sep 2026 include a poor last twelve months for large caps: the Nifty 50 total return index was down 7.09 percent over that year. A mid cap fund that earned 13 percent a year over the five years would feel like a good result. It still trailed its benchmark by almost two points a year.
The odds of picking winners in advance
Here is the part I find most useful. Say the base rate is that one fund in four beats its benchmark over ten years. Picking one fund that beats is a one in four event. Most people own three or four funds. The chance that all of them beat is far lower.
With three funds at a one in four base rate, the chance that all three beat is about 1.6 percent. The chance that none does is about 42 percent. Real funds are not independent coin flips, since funds in one category tend to win and lose together, but the shape holds: a portfolio built on picking winners needs to be right several times in a row.
What the gap costs in rupees
Put the fee on the same Rs 10 lakh. Say the index earns 12 percent a year before costs. An index fund charging 0.2 percent keeps 11.8 percent and ends ten years at about Rs 30.5 lakh. An active fund with a 1 percent expense ratio that matches the index before fees keeps 11 percent and ends near Rs 28.4 lakh. To simply tie the index fund, the active manager has to add about 0.8 points a year before fees, every year, for ten years. Some do. The base rate says most do not.
The free Learn module on index funds, ETFs and active funds in India works through the evidence, the arithmetic and a core and satellite example, with a quiz. The fee drag calculator shows what any fee does over time. Related: the cost of switching funds and funds that vanished, which explains why a ten year leaderboard flatters the survivors.
Questions readers ask
Do most active mutual funds beat the index in India?
Over long periods, most do not. Before costs, the average actively managed rupee must earn the market return, because together all investors own the market; after fees, the average falls short. The base rate gets worse as the period lengthens, because fees are charged every year.
What benchmark should a mutual fund be compared with?
Its total return index, which includes dividends, not the price index. SEBI has required funds to benchmark against the TRI since 2018. Over the five years to 30 Sep 2026, the Nifty 50 TRI returned 6.38 percent a year and the Nifty Midcap 150 TRI 14.76 percent a year.
How much extra return does an active fund need to match an index fund?
About the difference in costs. If an index fund costs 0.2 percent and an active fund 1 percent, the active manager has to add about 0.8 percentage points a year before fees just to tie. On Rs 10 lakh over ten years at 12 percent, that gap is worth about Rs 2.1 lakh.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
- GuideHow to beat the Nifty 50, and why most people do notThe SPIVA evidence, the concentration problem and the rules that have, with their risks.
- Free module 6.3Mutual Funds, Structure, Types and Hidden Costs8 min read
- StrategyAllcap strategyNifty Total Market, 50 stocks, every 2 weeks
- CalculatorSIP calculatorFree, with the formula and a worked example
Related
- The cost of switching fundsHopping out of a fund inside a year on a Rs 11.5 lakh pot costs about Rs 41,500 in tax and exit load, so the new fund must out earn the old by 3.6 percent before it earns a rupee.Costs: MF, PMS, RupeeCase . . 5 min
- Funds that vanishedAbout one in four Indian large cap funds disappeared over ten years, and the category average you see is the average of the survivors.Costs: MF, PMS, RupeeCase . . 5 min
- SEBI's overlap cap and the overlap you ownSEBI's February rule treats two schemes as duplicates above 50 percent overlap but carves out large caps, which is exactly where two plain funds share 60 to 80 percent.Costs: MF, PMS, RupeeCase . . 5 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.