

Company numbers..6 min read
EBITDA is not profit
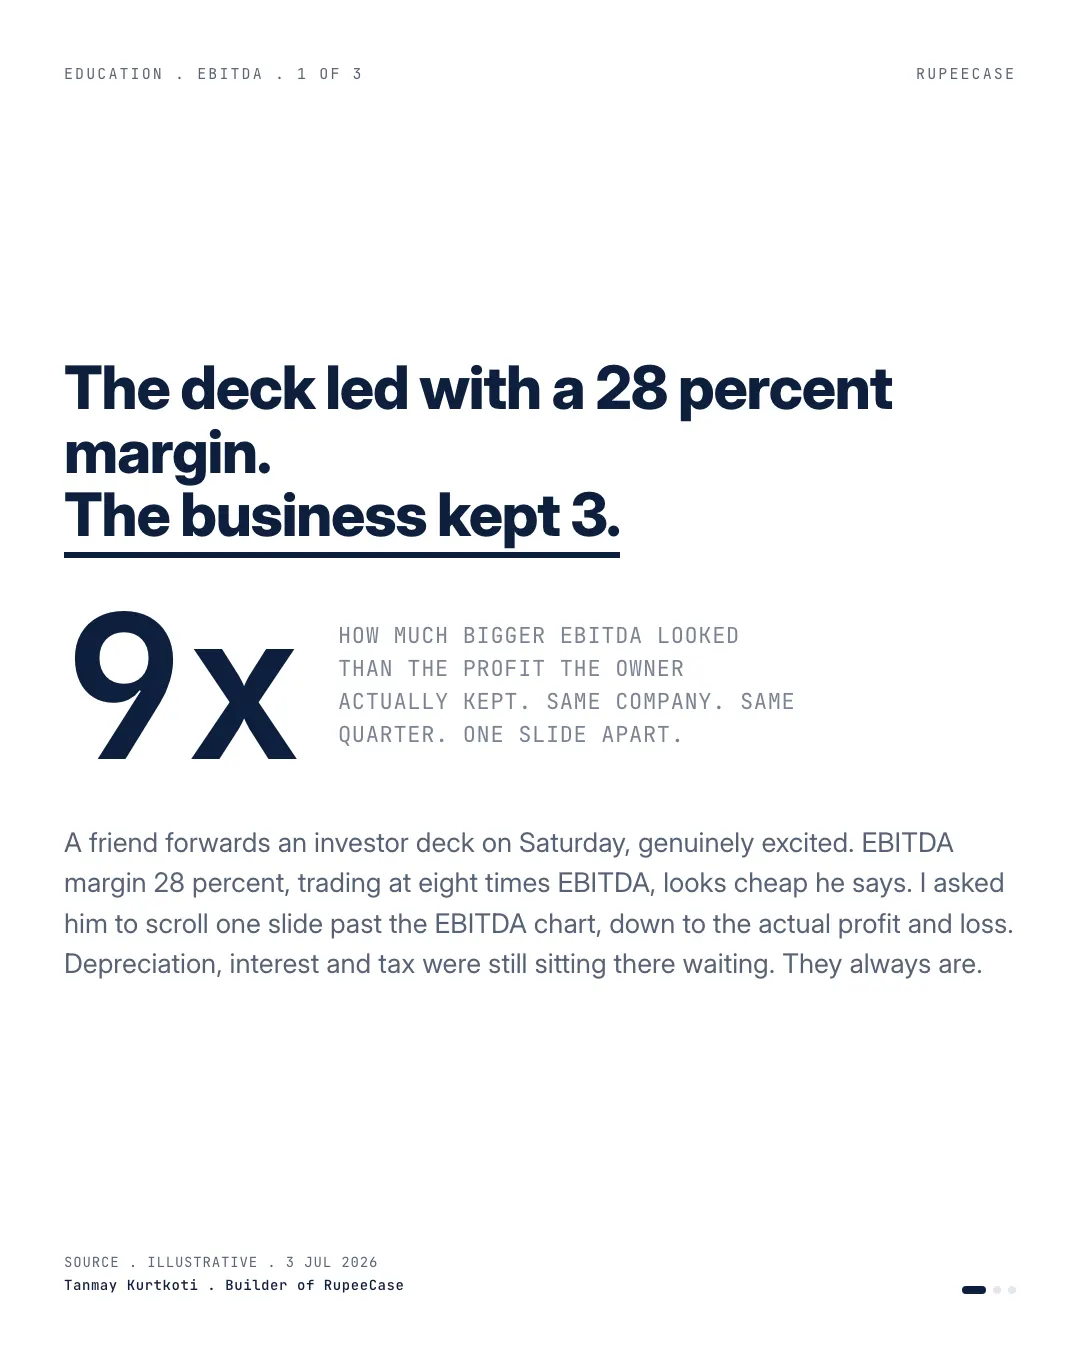
A 28 percent EBITDA margin became a 3 percent net margin after depreciation, interest and tax, and eight times EBITDA worked out to about 41 times earnings.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
A friend forwarded an investor deck on Saturday, genuinely excited. EBITDA margin 28 percent. Trading at eight times EBITDA. Looks cheap, he said.
I asked him to scroll one slide down.
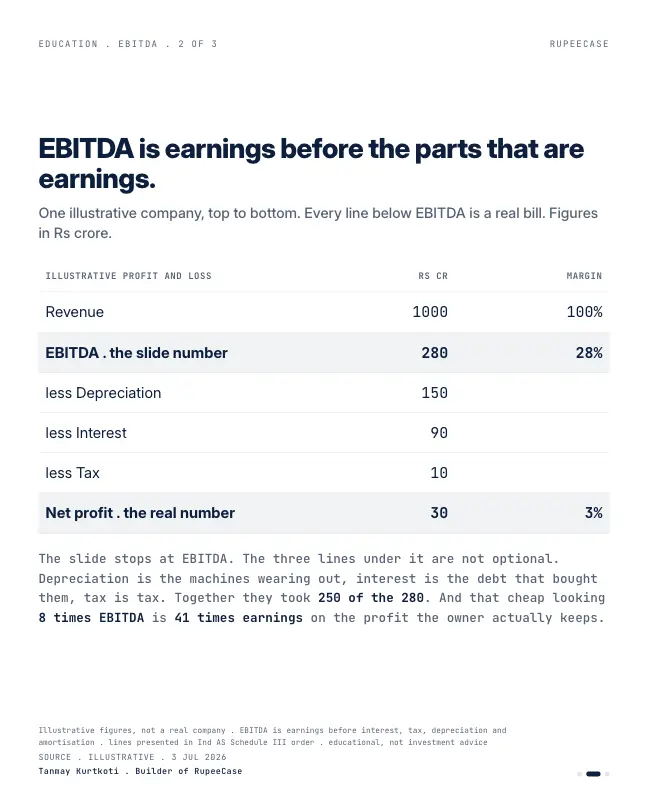
Past the EBITDA chart sits the actual profit and loss, and it tells a different story. EBITDA was 280 crore. Then came the lines the highlight slide leaves out. Depreciation of 150, which is the plants and machines wearing out and needing to be replaced. Interest of 90, the cost of the debt that bought those machines. Tax of 10. What reached the owner was 30 crore. A 28 percent margin on the slide became a 3 percent margin at the bottom.
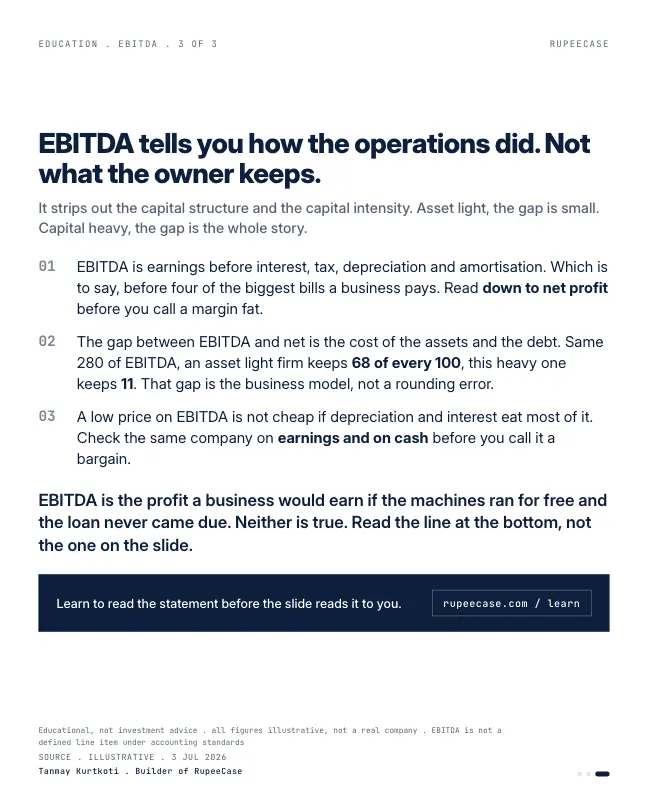
EBITDA stands for earnings before interest, tax, depreciation and amortisation. Read that again. It is the profit before four of the largest bills a business actually pays. For an asset light software firm, those bills are small and EBITDA sits close to reality. For a capital heavy business, telecom, steel, cement, hotels, the depreciation and the interest are the business, and EBITDA is a number that quietly pretends the machines were free and the debt does not exist.
Here is the part that catches people. That cheap looking eight times EBITDA works out to about 41 times earnings once you count what EBITDA skipped. Same 280 of EBITDA, an asset light company keeps 68 rupees of every 100 as profit. The heavy one keeps 11. The gap between EBITDA and net profit is not noise. It is the cost of the assets and the debt, and for a heavy business it is the whole story.
So before you call a margin fat or a multiple cheap, read down to net profit, then check the cash. EBITDA is the profit a business would earn if the machines ran for free and the loan never came due. Neither is true.
Walk the slide down to the owner
Put the deck's numbers on one page so you can redo them with a pencil. Call it Company A. Revenue is Rs 1,000 crore. After raw material, staff and other running costs, EBITDA is Rs 280 crore, the 28 percent on the slide.
Now take the bills one at a time. Depreciation of Rs 150 crore leaves an operating profit (EBIT) of Rs 130 crore. Interest of Rs 90 crore leaves Rs 40 crore before tax. Tax of Rs 10 crore, about 25 percent, leaves Rs 30 crore of net profit. That is 3 percent of revenue, and 11 percent of the EBITDA the slide led with.
- EBITDA on the slide280
- Depreciation-150
- Interest-90
- Tax-10
- Net profit30
Rs crore. Worked example from the opening, not a listed company.
Depreciation is the line people wave away because no cheque is written for it this year. But the cheque was written earlier, when the plant was bought, and another one is coming when it wears out. A company that spends Rs 150 crore a year just to keep its machines running has not earned that Rs 150 crore in any sense its owner can use.
How eight times becomes 41 times
The two multiples measure different things, which is why both can be quoted with a straight face. EV to EBITDA compares the whole business, the shares plus the debt, with profit before every financing and asset bill. P/E compares only the shares with what is left for shareholders.
Here is the arithmetic. Eight times Rs 280 crore puts the enterprise value at Rs 2,240 crore. Suppose net debt is about Rs 1,010 crore, which fits the Rs 90 crore interest bill at roughly 9 percent. Take the debt out and the shares are worth about Rs 1,230 crore. Divide by Rs 30 crore of net profit and you get 41 times earnings. Same company, same day, same price.
Try it. Set depreciation to 25 and interest to 0, as an asset light business might have, and net debt to 0. Net profit jumps to about Rs 191 crore and the P/E falls to under 12. That is the 68 rupees in every 100 from the opening. The slide multiple did not change. What the owner gets for it did.
Light and heavy, same EBITDA
Keeps about Rs 68 of every Rs 100 of EBITDA
- Depreciation Rs 25 crore: laptops and office fit outs
- No debt, so no interest line
- Tax of about 25 percent on Rs 255 crore
Keeps about Rs 11 of every Rs 100 of EBITDA
- Depreciation Rs 150 crore: plants that wear out
- Interest Rs 90 crore on the debt that built them
- Tax Rs 10 crore on what is left
This is why EBITDA comparisons across sectors mislead so easily. Two companies with the same EBITDA margin can sit a world apart on net margin, because one owns its assets and the other rents brains. Within one sector, where every company needs the same kind of plant, EBITDA is a fair first screen. Across sectors it compares unlike things.
One more Indian wrinkle. Since 1 April 2019, Ind AS 116 has moved most lease rent out of operating costs and into depreciation and interest. A retailer or a hotel chain that rents its sites now shows a higher EBITDA for exactly the same business it ran before. Nothing about the shops changed. The rent just moved below the line the slide stops at.
Where to find the lines EBITDA skips
Every listed company files its results with NSE and BSE under SEBI's listing rules, and the statement of profit and loss in that filing shows each line separately. The deck is optional and written by the company. The filing is the one with a fixed format.
- Depreciation and amortisationIts own line in the profit and loss. Compare it with capital spending in the cash flow statement: if capex runs well above depreciation year after year, the plant is still being built.
- Finance costsThe interest line. Divide operating profit by it for interest cover; under 2 times leaves little room in a bad year.
- TaxCurrent and deferred tax are shown apart. A tax rate far below the usual 25 percent deserves a look at the notes.
- Cash from operationsIn the cash flow statement. Set it against net profit, not against EBITDA, to see what was collected.
The free Learn module on reading financial statements walks the profit and loss, the balance sheet and the cash flow statement line by line, with a quiz at the end. For the next step, the five lines below the headline shows how to strip one off gains, and other income takes apart the line that flatters profit from the other side.
MythEBITDA is a cleaner number than profit because it removes accounting choices.
FactIt removes real costs. Depreciation is the plant wearing out and interest is the debt that paid for it. For a capital heavy business those two lines are most of the expense.
Questions readers ask
What is the difference between EBITDA and net profit?
EBITDA is profit before interest, tax, depreciation and amortisation. Net profit is what is left after all four. In the worked example here, Rs 280 crore of EBITDA became Rs 30 crore of net profit after Rs 150 crore of depreciation, Rs 90 crore of interest and Rs 10 crore of tax.
Is a low EV to EBITDA multiple always cheap?
No. EV to EBITDA ignores the costs of the assets and the debt, so a heavy business can look cheap on it and expensive on earnings. Eight times EBITDA turned into about 41 times earnings in the example, once the debt and the depreciation were counted.
Why do companies highlight EBITDA in presentations?
It is usually the largest profit figure available and it lets companies with different debt and asset levels look comparable. That is useful within one sector. It becomes misleading when it is used instead of net profit and cash from operations, which are the numbers that belong to the owner.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
Related
- Other income: you are buying the factory, not the FDReported profit rose from 170 to 200 while core business profit fell from 120 to 110, because other income's share of pre tax profit climbed from 29 to 45 percent.Company numbers . . 5 min
- The business that grows on its suppliers' moneyA 135 day cash conversion cycle needs Rs 37 crore to fund Rs 100 crore of extra sales, while a minus 35 day cycle is handed about Rs 10 crore for the same growth.Company numbers . . 5 min
- Five lines below the headlineA land sale, a deferred tax write back and a stretched depreciation life turned 3.8 percent profit growth into a 25 percent headline, and receivable days cracked first.Company numbers . . 5 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.