

Behaviour..5 min read
Sunk cost: the first loss is the cheapest
A 35 percent hole needs 54 percent to climb out, and a Rs 65,000 rump held flat for three years forgoes about Rs 30,000 against cutting and redeploying at the index.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
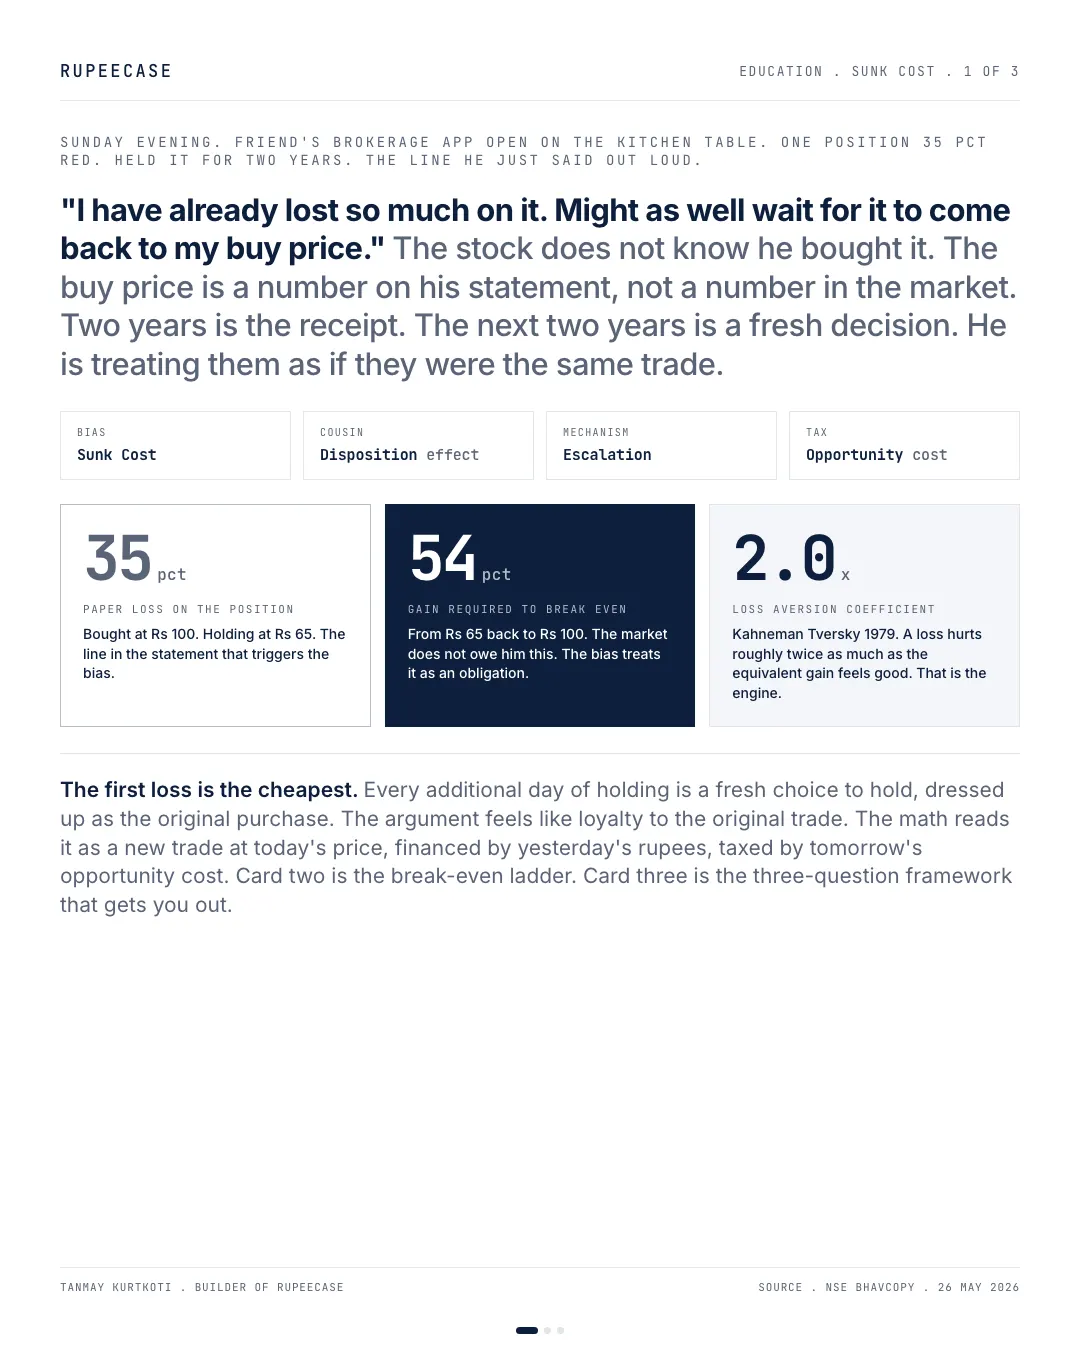
Sunday evening. Friend's brokerage app open on the kitchen table. One position 35 pct red. Held it two years. The line he just said out loud .
"I have already lost so much on it. Might as well wait for it to come back to my buy price."
The stock does not know he bought it. The buy price is a number on his statement, not a number in the market. Two years is the receipt. The next two years is a fresh decision. He was treating them as if they were the same trade.
The bias has a name. Arkes and Blumer wrote it up in 1985 . sunk cost fallacy. It rides on top of loss aversion (Kahneman and Tversky 1979 . a loss hurts roughly twice as much as the equivalent gain feels good) and escalation of commitment (Staw 1976 . the deeper in you are, the harder it is to walk away).
Run the math and the bias hides two costs, not one.
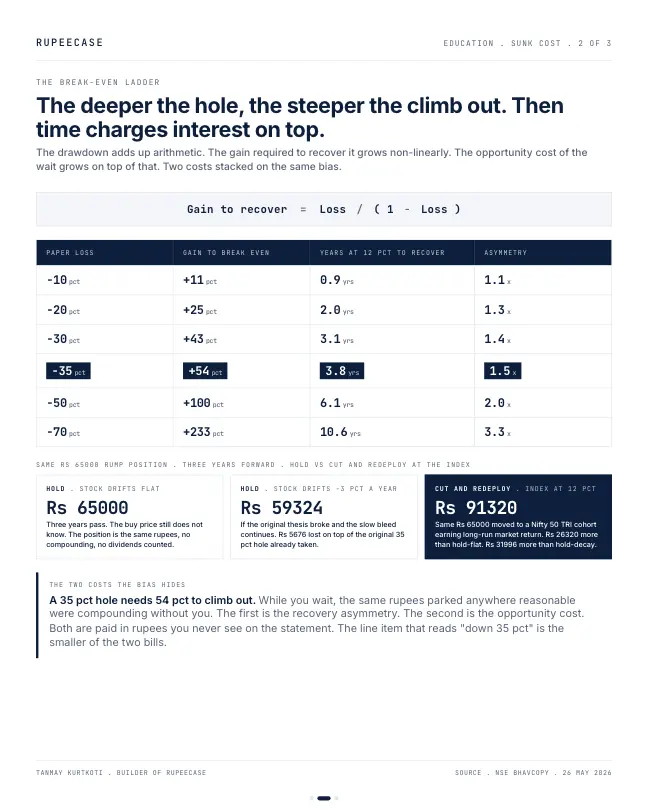
The first is the recovery asymmetry. A 35 pct hole needs 54 pct to climb out. A 50 pct hole needs 100 pct. A 70 pct hole needs 233 pct. The gain required to break even is loss divided by one minus loss. It grows non-linearly.
The second is the opportunity cost of the wait. Same Rs 65,000 rump position, three years forward. Hold flat lands at Rs 65,000. Hold with a -3 pct annual drift lands at Rs 59,324. Cut and redeploy at the index earning 12 pct lands at Rs 91,320. Roughly Rs 30,000 the portfolio never sees, on a Rs 65,000 base.
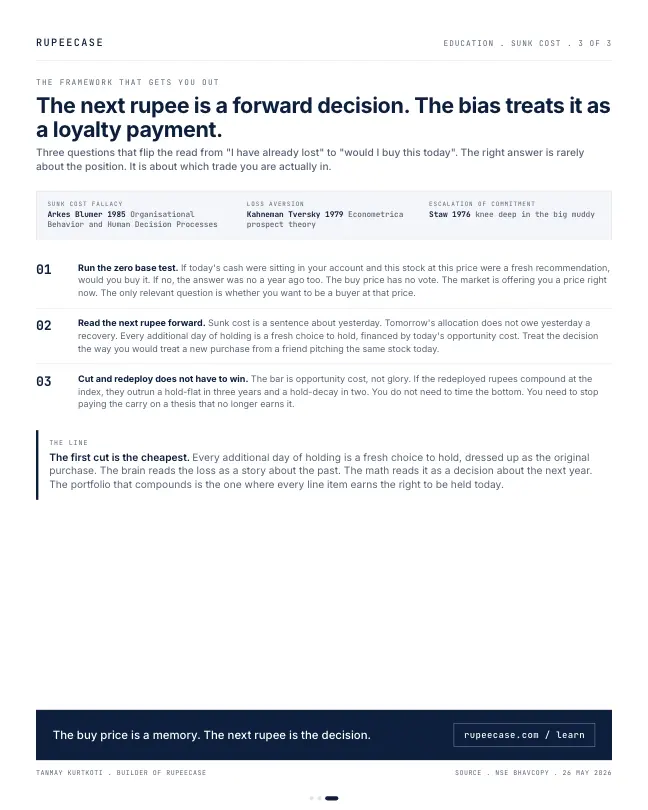
Three questions that flip the read. Would you buy this stock today at this price with fresh cash. Is the next rupee a forward decision or a loyalty payment. Does cut and redeploy have to win, or does it just have to not lose to break-even-with-the-original.
The first cut is the cheapest. Every additional day of holding is a fresh choice to hold, dressed up as the original purchase
The climb gets steeper with every step down
The recovery formula in the opening is easier to feel as a picture. Each bar is the gain needed just to get back to the starting value after a given fall.
- After a 10% fall11.1%
- After a 20% fall25.0%
- After a 35% fall53.8%
- After a 50% fall100.0%
- After a 70% fall233.3%
Gain needed = loss / (1 minus loss). Arithmetic, no data source needed.
The asymmetry is not an opinion about the stock. It is arithmetic. What it changes is the time. A stock that needs 54 percent to break even, and then returns a steady 12 percent a year, takes about 3.8 years to get there. At 8 percent a year it takes about 5.6 years. Waiting for the buy price is a bet on a specific rate of recovery, made without saying the rate out loud.
A real recovery, on the index
Even a broad index takes a while. On NSE's closes, the Nifty 50 set a record of 26,216.05 on 26 Sep 2024, fell to 22,082.65 on 4 Mar 2025, a fall of 15.8 percent, and first closed back above that record on 2 Jan 2026, about 15 months after it was set. A diversified index needed 15 months to climb out of a 16 percent hole. A single stock 35 percent down has no such guarantee: some recover, some never do, and the buy price has no say in which.
The index is in another hole as I write. It closed at 26,328.55 on 2 Jan 2026 and at 22,231.80 on 8 Oct 2026, 15.6 percent lower. Getting back needs 18.4 percent. That is the same formula applied to the market, and the same reason a rule that keeps buying through the fall is easier to hold than a single position you are trying to rescue.
Averaging down is the loyalty payment
The second question in the opening has a common disguise. Buying more of a falling stock to lower the average price feels like a plan. Sometimes it is one, when the reasons you bought still hold and the position is sized for it. Often it is the escalation of commitment from the opening: fresh rupees sent in to make the old entry price look better.
MythAveraging down brings my break even closer, so it reduces the loss.
FactIt lowers the average on paper and raises the rupees at risk in the same stock. The loss is unchanged until the price moves. Only the size of the bet changed.
Here is the test I use before adding to a red position. Strip the old holding out of the picture entirely. If a friend with no position asked whether this stock deserved this many new rupees today, against everything else available, what would the answer be? If the answer is no for the new money, holding the old money is the same decision with a story attached.
- Fresh cashWould I put this amount into this stock today if I held none?
- Forward or loyaltyIs the next rupee chasing a return, or defending a price?
- Bar to clearThe alternative only has to beat holding, not recover the old loss.
The third step is the one people miss. Cutting and redeploying does not need to earn back the 35 percent. The 35 percent is gone in both paths. It only has to do better than the stock from here. On the opening's numbers, moving the Rs 65,000 to something earning 12 percent ends near Rs 91,320 in three years, against Rs 65,000 flat or Rs 59,324 with a slow drift.
The free Learn module on loss aversion and prospect theory explains why a loss weighs about twice a gain and how that turns into the sunk cost habit. The related post on anchoring on the buy price covers the tax side of booking a loss, and the drawdown recovery calculator runs the climb for any fall.
Questions readers ask
How much does a stock need to rise to recover a loss?
The gain needed is the loss divided by one minus the loss. A 20 percent fall needs 25 percent, a 35 percent fall needs 53.8 percent, and a 50 percent fall needs 100 percent to get back to the starting value.
What is the sunk cost fallacy in investing?
It is letting money already lost decide what you do next, such as holding a falling stock only to get back to the buy price. The lost money is gone whichever way you decide, so the only useful comparison is what the remaining value can earn in this stock against elsewhere.
Is averaging down a good idea?
It lowers the average purchase price on paper but raises the amount at risk in one stock. It only makes sense when the original reasons still hold and the larger position still fits your plan; buying more to escape a loss is a different decision.
The cards
3 cards. Swipe, or tap to open.
Related
- By the time the group agrees, the trade is finishedA momentum strategy's time weighted 16.7 percent CAGR became about minus 4.9 percent money weighted, because the crowd arrived the year after the 72 percent print.Behaviour . . 5 min
- Recency bias meets factor crowdingA model basket up 60 percent on a trailing return screen is a momentum tilt with a friendly name, and the same factor has lost 28, 21 and 19 percent in its three crashes.Behaviour . . 6 min
- Mental accounting: the bonus that feels differentThaler's mental accounting explains why a Diwali bonus gets spent and a salary SIP never misses, and a Rs 2 lakh splurge carries a thirty year bill of about Rs 60 lakh.Behaviour . . 5 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.