

Personal finance and tax..5 min read
Day 364 vs day 366: the two day tax cliff
Redeeming a Rs 10 lakh lump sum two days after the year mark removes the exit load, drops STCG to LTCG and opens the exemption, worth Rs 40,225 on the same units.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
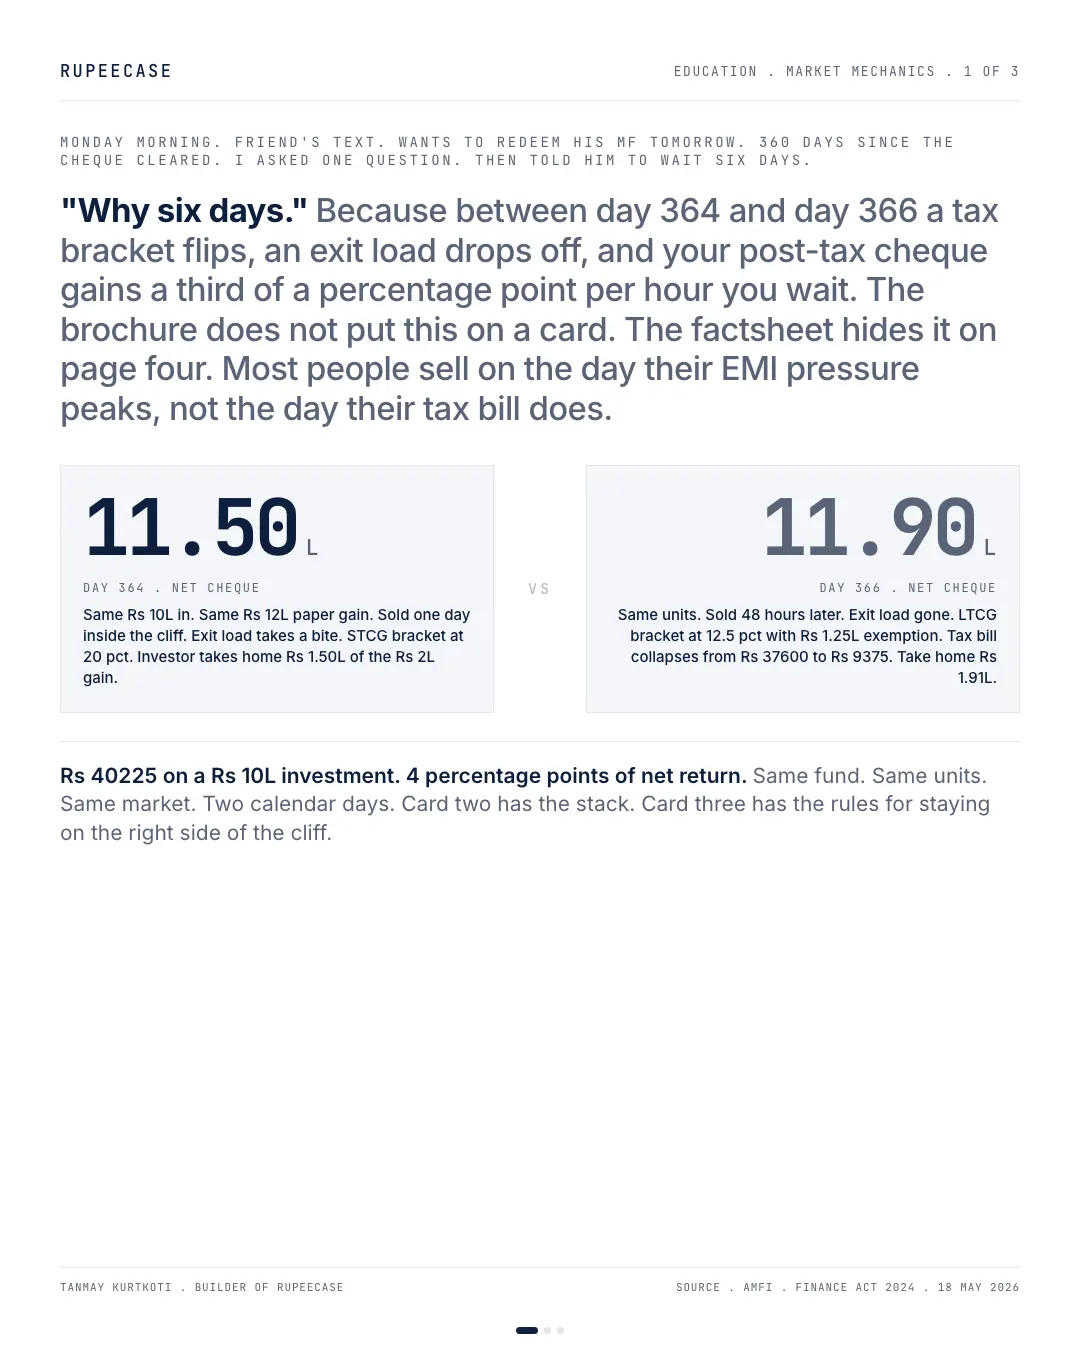
A friend texted me Monday morning. He wanted to redeem an equity mutual fund the next day. 360 days since the original cheque had cleared. He needed the money for an upcoming spend. Could he just hit sell.
I asked him one question. Lump sum or SIP. Lump sum, he said.
I told him to wait six days. Here is what those six days are worth.
Same Rs 10 lakh in. Same Rs 12 lakh paper value today. Two calendar days apart on the sell side.
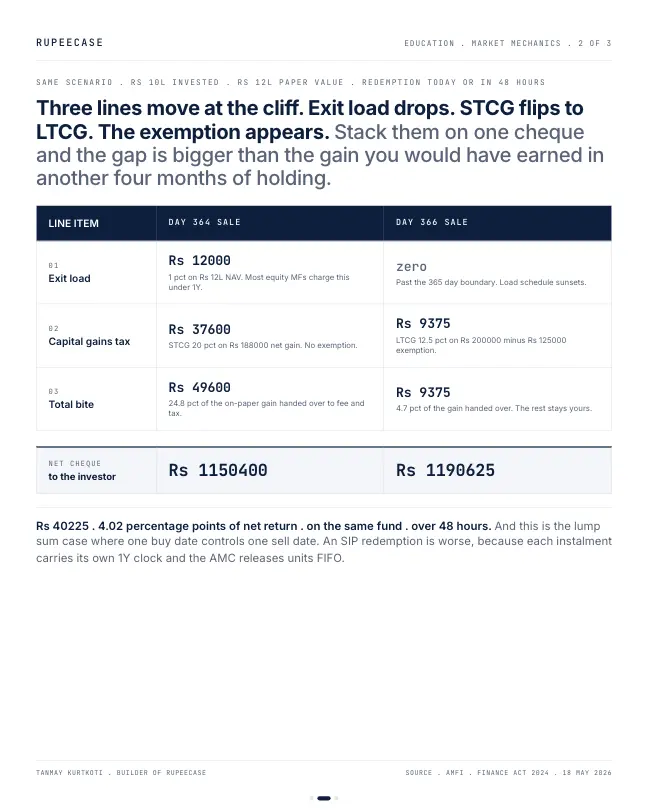
On day 364, three things are still alive on his ticket. The exit load schedule (most equity MFs charge 1 pct if redeemed inside a year, so Rs 12,000 on a Rs 12L NAV). The STCG bracket at 20 pct on the post-load gain of Rs 1.88L, which is Rs 37,600. And no LTCG exemption, because the unit clock has not crossed 365 days. Net cheque to him . Rs 11.50 lakh.
On day 366, all three move. Exit load is zero. The 20 pct STCG bracket falls to the 12.5 pct LTCG bracket. The Rs 1.25 lakh per financial year LTCG exemption opens up, so only Rs 75,000 of the Rs 2 lakh gain gets taxed at 12.5 pct, which is Rs 9,375. Net cheque . Rs 11.90 lakh.
Rs 40,225 of net return. Four percentage points on a Rs 10 lakh corpus. Same fund. Same market. Same units. 48 hours.
And this is the easy case. SIP redemptions are worse. The AMC releases units FIFO, so 13 monthly instalments do not mean 13 months of long-term holding. Only month one is past the cliff.
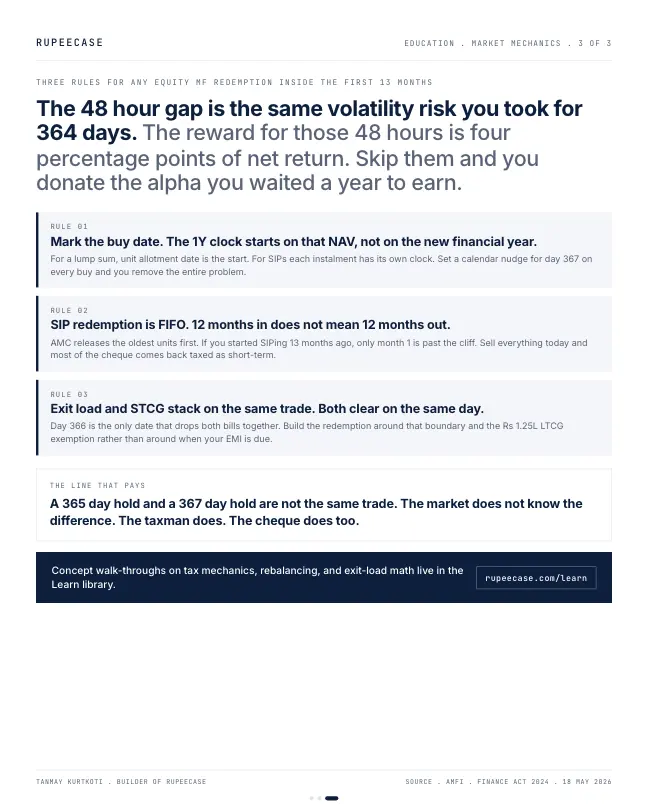
Three rules I gave him. Mark the buy date on every fresh purchase and set a calendar nudge for day 367. Treat SIPs as 12 separate clocks, not one. Plan the sell around the cliff, not around the EMI calendar.
The market does not know the difference between a 365 day hold and a 367 day hold. The taxman does.
The rule behind the cliff, as of 2026
For listed equity shares and equity oriented mutual fund units, a gain is long term if the units were held for more than 12 months. That rule has applied to all listed securities since 23 Jul 2024. Short term gains on these assets are taxed at a flat 20 percent, long term gains at 12.5 percent on the part above Rs 1.25 lakh in a financial year. From 1 Apr 2026 the same rates sit in the Income-tax Act 2025 (sections 196 and 198 replace the old 111A and 112A), and the Finance Bill 2026 left them unchanged.
Two details matter at the edge. "More than 12 months" means you count from the purchase date, so a unit bought on 5 Jun 2025 turns long term on a sale from 6 Jun 2026. And the exit load is a fund rule, written in each scheme's documents, not a tax rule. Many equity funds charge 1 percent within a year, but the period and the rate vary.
The two tickets, side by side
Net Rs 11,50,400
- Exit load 1%: Rs 12,000
- Short term gain Rs 1,88,000 at 20%: Rs 37,600
- No exemption
Net Rs 11,90,625
- Exit load: nil
- First Rs 1,25,000 of gain exempt
- Rs 75,000 at 12.5%: Rs 9,375
With the 4 percent health and education cess added, the short term tax is Rs 39,104 and the long term tax Rs 9,750, so the gap widens slightly, to about Rs 41,354. One more thing the cess does not change: the Rs 60,000 rebate that makes income up to Rs 12 lakh tax free in the new regime cannot be used against these special rate gains. A modest earner pays the 20 percent too.
tax on day 364, with cess
Worked example, 20% + 4% cess
tax on day 366, with cess
Worked example, 12.5% + 4% cess
more in hand, load and tax together
Worked example
Your own redemption, before you click
Set the exemption to zero if you have already booked Rs 1.25 lakh of long term equity gains this year. The exemption is one pool for all listed equity and equity fund gains, not one per fund.
A SIP is twelve clocks, not one
Units leave a folio first in, first out. Each SIP instalment is its own purchase with its own date, so the oldest units become long term first and the newest are always short term.
- First instalment
Long term on a sale from 6 Jun 2026.
- Seventh instalment
Long term on a sale from 6 Dec 2026.
- Thirteenth instalment
Short term until 6 Jun 2027.
- Redeem everything
Only the first instalment's units are long term. The other twelve are taxed at 20 percent.
A Rs 10,000 SIP running for 13 months and redeemed in full on 10 Jun 2026 is about 92 percent short term by money. If only part of the folio is needed, redeeming that part first removes the oldest units, which are the long term ones. That is the order the rule already uses.
MythMy SIP has run for over a year, so all of it is long term.
FactEach instalment has its own date. After 13 monthly instalments, only the first one has been held for more than 12 months.
The free Learn module on equity taxation after July 2024 has the full rule set, worked examples and the new section numbers. The post on the Rs 1.25 lakh you forget every April shows how to use the exemption every year rather than once.
Questions readers ask
When does an equity mutual fund become long term?
Units of an equity oriented fund are long term if held for more than 12 months. A unit bought on 5 Jun 2025 is long term on a sale from 6 Jun 2026. Each SIP instalment has its own date.
What is the tax on equity mutual funds sold within one year?
Short term gains on equity oriented funds are taxed at 20 percent plus 4 percent cess, for transfers from 23 Jul 2024. The rate is unchanged for tax year 2026-27 under the Income-tax Act 2025, and the new regime rebate does not apply to it.
Is the Rs 1.25 lakh LTCG exemption per fund?
No. It is a single limit of Rs 1.25 lakh per financial year for all long term gains on listed equity shares, equity oriented funds and business trust units together.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
- GuideCapital gains tax on shares in India: the rules for 2026-27, worked in rupees20% short term, 12.5% long term above ₹1.25 lakh: the rules for 2026-27, in rupees.
- StrategyAllcap strategyNifty Total Market, 50 stocks, every 2 weeks
- Free module 11.1Equity Taxation After July 2024: The New Rules10 min read
- CalculatorLTCG and STCG on equityFree, with the formula and a worked example
- Blog topicPersonal finance and tax notes24 notes
Related
- NPS, PPF, ELSS: the order matters more than the rateThe Rs 50,000 NPS slot under 80CCD(1B) sits on top of the 80C ceiling, so a rate led picker leaves Rs 15,600 a year of saved tax on the table at the 30 percent slab.Personal finance and tax . . 5 min
- The Rs 1.25 lakh you forget every AprilBooking about Rs 1.25 lakh of long term gains each year and rebuying cuts the exit tax on a Rs 96 lakh corpus from Rs 10.65 lakh to Rs 7.68 lakh.Personal finance and tax . . 5 min
- A loss you do not book is a rebate you do not claimBooking a Rs 60,000 short term loss against a Rs 1 lakh short term gain cuts the tax from Rs 20,000 to Rs 8,000, and unused losses carry eight years if you file on time.Personal finance and tax . . 10 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.