

Costs: MF, PMS, RupeeCase..6 min read
IDCW vs Growth: the dividend that is your own money
A fund payout drops the NAV by the same amount and is taxed at slab, so Rs 10 lakh over twenty years ends near Rs 96 lakh in Growth and Rs 69 lakh on the IDCW path.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
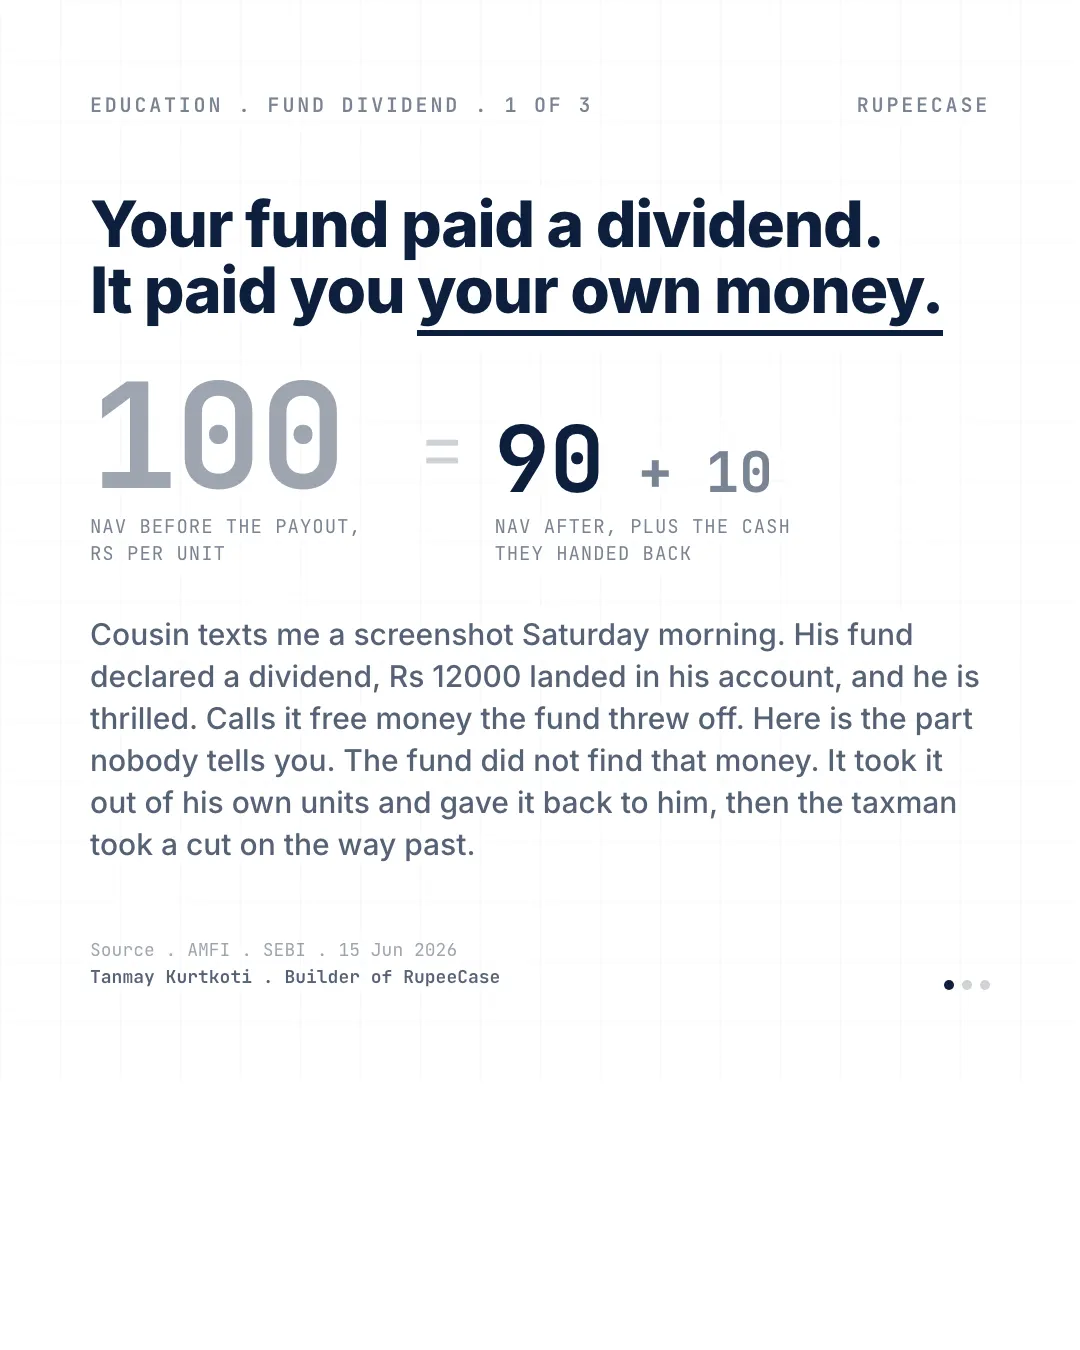
A cousin texts me a screenshot on Saturday morning. His mutual fund declared a dividend, Rs 12,000 landed in his account, and he is genuinely thrilled. He calls it free money, something the fund threw off on top of his returns. I hated being the one to tell him where that Rs 12,000 actually came from.
The fund did not find it. It took it out of his own units and handed it back to him.
This is the part most people never get told. When a fund pays a dividend, its NAV falls by exactly the amount paid. NAV of 100 pays out 10, and the NAV is now 90. You hold 90 in units plus 10 in cash. You are still sitting on 100. Nothing was created, the money simply moved from one pocket to another.
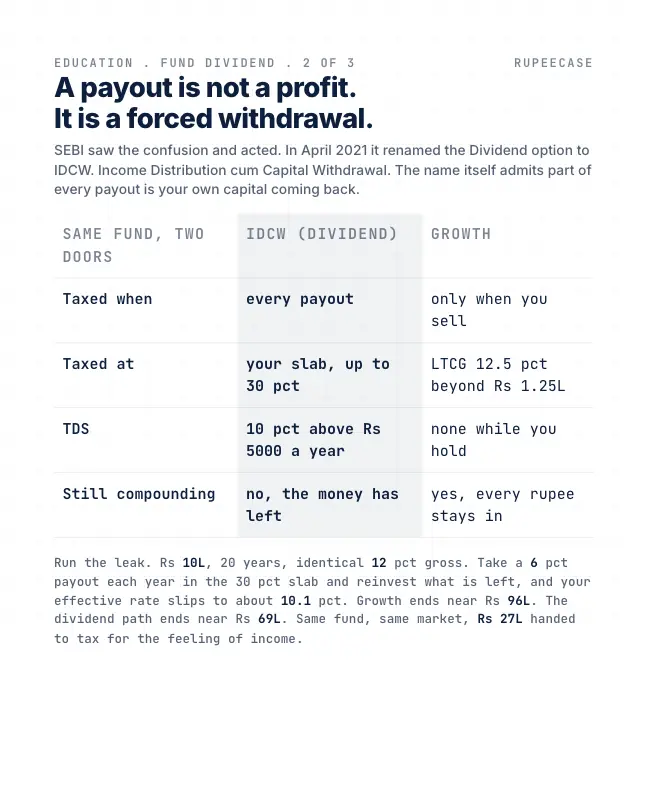
SEBI noticed how much this misled people. In April 2021 it renamed the Dividend option to IDCW, which stands for Income Distribution cum Capital Withdrawal. Read those last three words. The regulator is telling you, in the official name, that part of every payout is your own capital coming back to you.
And then it gets taxed. IDCW is added to your income and taxed at your slab, up to 30 percent, with 10 percent TDS once a fund house's payouts to you cross Rs 10,000 in a financial year, the threshold since 1 Apr 2025. The Growth option of the same fund is taxed at 12.5 percent for long-term equity gains, and only when you decide to sell. One path taxes you every year at the highest rate you pay. The other lets the whole amount keep compounding and taxes you once, later, at a lower rate.
Run the leak. Rs 10 lakh, twenty years, identical 12 percent gross. Take a 6 percent payout each year in the 30 percent slab and reinvest what is left, and your effective rate slips to about 10.1 percent. Growth ends near Rs 96 lakh. The dividend path ends near Rs 69 lakh. Same fund, same market, about Rs 27 lakh handed to the taxman for the feeling of receiving income.
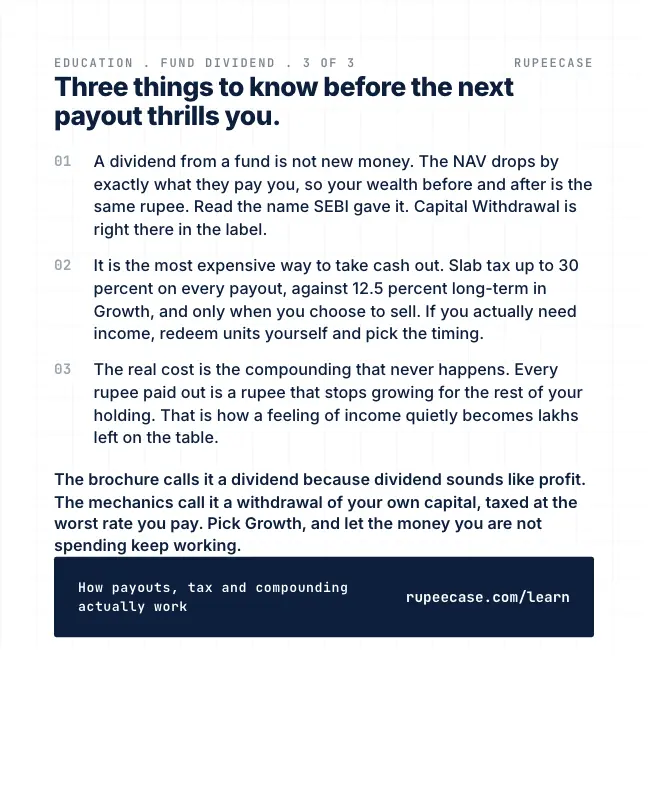
If you actually need cash from your investments, redeem units yourself and control the timing and the tax. If you do not need the cash, there is no reason to invite a withdrawal you did not ask for. Pick Growth and let the money you are not spending keep working.
The payout, step by step
The cousin's Rs 12,000 is easier to see with the units in front of you. Say he holds 10,000 units at a NAV of Rs 100, a holding of Rs 10 lakh. The fund declares an IDCW of Rs 1.20 per unit.
- Before the record date10,000 units at Rs 100. Holding: Rs 10,00,000.
- PayoutRs 1.20 a unit, Rs 12,000 to his bank account.
- AfterNAV falls to Rs 98.80. Units: Rs 9,88,000. Plus Rs 12,000 cash. Still Rs 10,00,000.
- TaxThe Rs 12,000 is added to his income and taxed at his slab, 30 percent in the top bracket: Rs 3,600.
- NetRs 9,96,400. The payout cost him Rs 3,600 for money he already owned.
Because Rs 12,000 crosses Rs 10,000 in the year, the fund also deducts 10 percent TDS before paying, Rs 1,200, which he adjusts in his return.
How the label changed
None of this is new, but the name used to hide it. Until 2020 the fund paid a dividend distribution tax before the payout, and the payout was tax free in your hands. That made the option look like free income. Two changes ended that.
- Payouts taxed in your hands
Dividend distribution tax abolished; mutual fund payouts added to your income at slab rates.
- SEBI orders the new name
Circular on reviewing the dividend option in mutual fund schemes.
- Dividend becomes IDCW
Income Distribution cum Capital Withdrawal, on every scheme.
- TDS threshold Rs 10,000
Up from Rs 5,000 for income from mutual fund units.
Twenty years, after every tax
The opening compares Growth before its exit tax with the payout path after its yearly tax. Here is the full version, with every tax paid, so the comparison is fair. Rs 10 lakh, 12 percent a year before costs, twenty years.
- Growth: the units grow to about Rs 96.46 lakh. At exit, the gain above Rs 1.25 lakh is taxed at 12.5 percent, about Rs 10.65 lakh. He keeps about Rs 85.81 lakh.
- IDCW, reinvested after tax: at each year end the fund pays out 6 percent of the holding, he pays 30 percent of it in tax and buys units with the other 70 percent. The holding ends near Rs 67.08 lakh, close to the opening's figure; the small difference is the timing of each payout. His reinvestments count as cost, so the exit gain is smaller, but there is still tax at the end: he keeps about Rs 63.46 lakh.
- Growth, taxed once at exitRs 85.81 L
- IDCW at 30% slabRs 63.46 L
Rs 10 lakh, 12% a year gross, 20 years, 6% yearly payout reinvested after 30% tax. Rates for transfers from 23 Jul 2024, before surcharge and cess. Worked example.
The gap is smaller than the Rs 27 lakh in the opening, because Growth also pays tax in the end. It is still about Rs 22 lakh on a Rs 10 lakh start: more than twice the original cheque, handed over for the feeling of receiving income.
At a 5 percent slab the leak is 0.30 percent a year and the two options sit much closer. So the cost of IDCW depends on who receives it. For a retired investor whose income sits in a low slab, it can be small. For a salaried investor in the top slab, it is the most expensive way to get cash out of a fund.
Cash without the payout
If you need regular cash, there is another way to get it from the same fund: redeem units yourself. A systematic withdrawal sells a fixed amount of units each month. Only the gain inside each redemption is taxed, and on units held more than 12 months it is taxed at 12.5 percent, with the first Rs 1.25 lakh of long term gains in the year exempt.
Take the Rs 12,000. If the units he sells to raise it were bought at Rs 70 and are now worth Rs 100, the gain inside the Rs 12,000 is Rs 3,600. That is likely inside the yearly exemption, so the tax is zero, against Rs 3,600 on the IDCW payout at 30 percent.
MythA fund that pays IDCW is earning extra income on top of its return.
FactThe NAV falls by every rupee paid out. Your total does not change until the tax comes off.
The free Learn module on tax treatment of mutual funds, ETFs and bonds sets out IDCW, Growth, debt fund and ETF tax with worked examples and a quiz. The capital gains tax calculator runs a redemption. Related: direct against regular and the tax you pay for someone else's trades.
Questions readers ask
Is IDCW better than Growth in a mutual fund?
They hold the same portfolio. IDCW pays out part of your holding, the NAV falls by the same amount, and the payout is taxed at your slab rate every year. Growth keeps the money invested and taxes the gain only when you sell. On Rs 10 lakh over twenty years at 12 percent, with a 6 percent payout in the 30 percent slab, Growth keeps about Rs 22 lakh more after all tax.
How is IDCW taxed in India?
The payout is added to your income and taxed at your slab rate. If a fund house pays you more than Rs 10,000 of such income in a financial year, it deducts 10 percent TDS first, under the threshold in force from 1 Apr 2025.
Why did SEBI rename dividend to IDCW?
Because the payout is not extra income: part of it is your own capital returned. SEBI's circular of 5 Oct 2020 renamed the option Income Distribution cum Capital Withdrawal, in force from 1 Apr 2021, so the name says that plainly.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
- GuideHow dividends are taxed in India: slab rates, TDS and what a dividend is really worthSlab rates, 10% TDS above ₹10,000 a company, record dates and what a yield is worth.
- Free module 6.3Mutual Funds, Structure, Types and Hidden Costs8 min read
- StrategyAllcap strategyNifty Total Market, 50 stocks, every 2 weeks
- CalculatorExpense ratio impactFree, with the formula and a worked example
Related
- The tax you pay for someone else's tradesA PMS realises gains in your name every year while a fund defers to exit, and on the same 14 percent gross over ten years the structure alone keeps five to twelve lakh more invested.Costs: MF, PMS, RupeeCase . . 6 min
- ETF vs index fund: cheaper sticker, not the cheaper holdA 0.04 percent ETF loses to a 0.07 percent index fund for a monthly SIP once Rs 20 of brokerage, the spread and demat charges land twelve times a year.Costs: MF, PMS, RupeeCase . . 6 min
- Direct vs regular: the finder's fee you pay foreverA one point trail commission on Rs 10 lakh over twenty years costs Rs 14.5 lakh, almost one and a half times the original cheque, for a fund sold once.Costs: MF, PMS, RupeeCase . . 6 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.