

Costs: MF, PMS, RupeeCase..9 min read
The index rewrites itself
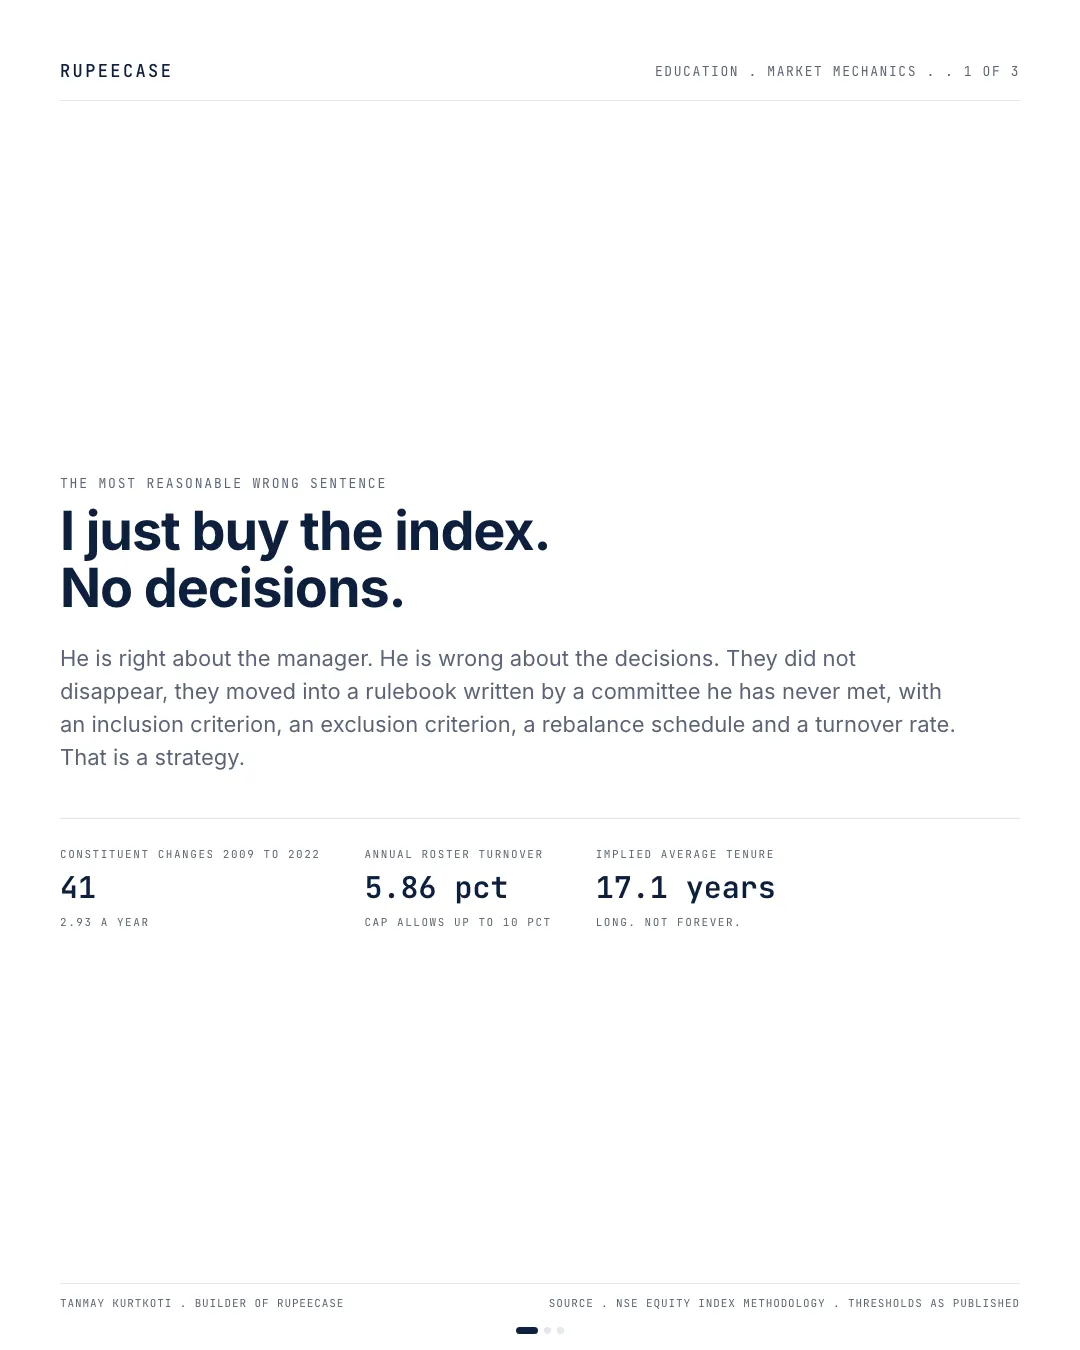
The Nifty 50 made 41 constituent changes from 2009 to 2022, 2.93 a year, with a twenty rank buffer between joining and leaving and a cap of five additions a year.
By Tanmay Kurtkoti, founder of QC Alpha and builder of RupeeCase
A colleague said something at lunch last week that I have heard maybe two hundred times, and it is the most reasonable wrong sentence in Indian personal finance.
"I just buy the index. No decisions, no manager, nothing to think about."
He is right about the manager. He is wrong about the decisions, and he is wrong in an interesting way, because the decisions did not disappear. They got moved into a rulebook written by a committee he has never met, and that rulebook trades.
Somebody is running an active strategy. It is just not him.
An index is a set of rules for deciding which companies belong in a list. Rules about size, about how much of the stock actually floats freely, about how reliably it trades. When a company stops satisfying those rules, it comes out. When another starts satisfying them, it goes in.
That is a strategy. It has an inclusion criterion, an exclusion criterion, a rebalance schedule and a turnover rate. The only thing separating it from what everybody calls active management is that the rules are published in advance and applied without discretion.
The calendar of that strategy is published too. The NSE factsheet for the Nifty 50, dated 30 Sep 2026, sets out the cycle every tracking fund has to follow.
- EligibilityF&O listed, at least one month of listing, average impact cost of 0.50 percent or less on a Rs 10 crore basket for 90 percent of observations over six months.
- Cut-offSix months of average data ending 31 January or 31 July.
- NoticeChanges announced four weeks before they take effect.
- Funds tradeEvery tracker buys the entrant and sells the exit on the same date.
Which is a real and important difference. It is not the same as no decisions.
Between 2009 and 2022 there were 41 constituent changes in the Nifty 50. Fourteen years, fifty slots, forty one changes. That is 2.93 changes a year, or 5.86 percent of the roster turning over annually.
Put differently, the number of changes across those fourteen years is equal to 82 percent of one full roster.
The buffer is where the design shows
The interesting part is not that the list changes. It is how carefully the rules are built to stop it from changing too much.
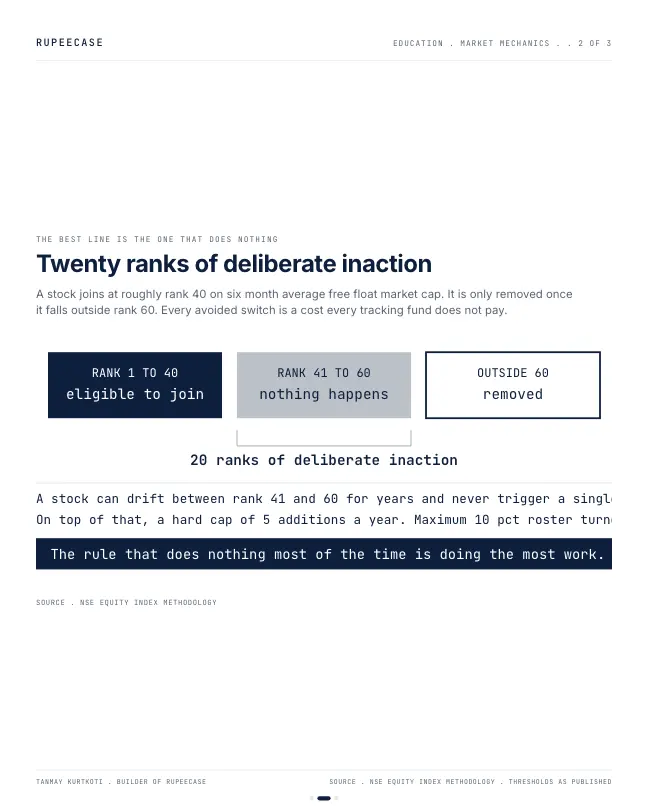
A stock does not enter the index the moment it becomes the fifty first largest. It has to break into roughly the top forty on six month average free float market capitalisation. And an existing constituent is not removed the moment it slips to fifty first. It stays until its rank falls outside the top sixty.
Twenty ranks of nothing. A stock can wander between forty first and sixtieth for years and never cause a trade in any of the funds tracking the index.
That buffer is not laziness. It is the single most valuable line in the methodology, and it exists because every unnecessary switch imposes a real cost on every tracking fund at once, in an order everybody can see coming. On top of it sits a hard cap of five additions in any calendar year, which puts a ceiling of 10 percent on how much of the roster can turn in twelve months.
Compare that to what most discretionary equity funds do with their portfolios in a year and the index starts looking like the disciplined one, which is exactly the point.
The arithmetic of a rulebook that trades slowly
| What the rules produce | Number |
|---|---|
| Constituent changes 2009 to 2022 | 41 |
| Changes per year | 2.93 |
| Annual roster turnover | 5.86 pct |
| Implied average time a company stays in | 17.1 years |
| Maximum turnover the cap allows | 10.00 pct |
| Ranks of buffer between joining and leaving | 20 |
Seventeen years is the number I keep coming back to. At the observed rate of change, the average company in the index gets about seventeen years in it. That is a long time, and it should be, because the whole point of a large cap index is to hold the companies that matter until they demonstrably stop mattering.
It is also not forever, which is the part my colleague had not thought about.
What the turnover rate buys, expressed as time
Turnover percentages are hard to feel. Convert them into how long a company gets to stay and they become obvious immediately.
At the observed rate of 2.93 changes a year, a slot in the index turns over once every 17.1 years. If the committee used its full allowance of five additions every single year, that would fall to 10.0 years. A rule that made only one change a year would stretch it to 50. And a hypothetical aggressive rule making ten changes a year would compress it to 5.
The bar worth noticing is the third one. The methodology permits twice the turnover that actually happens. The committee has the authority to change five names a year and uses, on average, less than three.
That restraint is a design choice being made repeatedly in your favour, and it is invisible unless you go looking for it. Nobody issues a press release about the switch they did not make.
What I cannot tell you
I went looking for a clean number on how many of the original 1996 constituents are still in the index today, because it is the fact everybody wants, and I could not find one I would stand behind.
There is no shortage of confident claims about it online. What I could not find was a source that both listed the original roster and reconciled it against every name change, merger, demerger and reclassification in the thirty years since. A company that merged into another is not the same as a company that was dropped for underperforming, and a lot of the counts floating around treat those identically.
So I am leaving it out rather than repeating something I have not verified. The observed rate of change is the honest number I have, and it is enough to make the point.
Where my colleague is more right than I have made him sound
An index fund really does remove almost every decision that costs ordinary investors money. Which fund manager, which style, when to switch, whether last year's outperformance means anything. Those decisions are removed, they are the expensive ones, and removing them is the reason index investing has worked for so many people.
The rules also apply themselves. Nobody wakes up and decides to be scared. A committee applies a published criterion on a published date and the fund follows, and that indifference to sentiment is worth more than most active judgement.
And the turnover is genuinely low. At 5.86 percent a year, the trading cost of index membership changes is a small fraction of what most active funds spend, and my colleague pays almost none of it in visible fees.
MythAn index fund never trades, so it has no turnover cost.
FactIt trades at every review, on dates the whole market knows in advance. The cost is small because changes are rare, not because they are free, and it shows up as tracking difference rather than a fee.
What he does not get is exemption from the two things every rulebook has. Concentration, because a cap weighted index will let its winners grow without limit and there is no rule that stops that. And style, because a rule that selects on size and traded liquidity is a rule that systematically prefers large, liquid and already successful companies. That is a defensible bet. It is still a bet, and understanding what you are actually holding is what the stock level pages and the strategy comparison view are for.
What the concentration looks like today
The concentration point is easy to put a number on. On the same factsheet, ten companies out of fifty carry more than half the index.
Weight of the ten largest Nifty 50 stocks
NSE Indices, Nifty 50 factsheet, 30 Sep 2026
Weight of the single largest stock
NSE Indices, Nifty 50 factsheet, 30 Sep 2026
Weight of the largest sector, financial services
NSE Indices, Nifty 50 factsheet, 30 Sep 2026
None of those figures is a decision anybody took in a meeting. They are what a free float weighted rule produces when a few companies keep growing. The rulebook decides who gets in. The market decides how big each one gets once inside, and no rule trims it back.
Three rules
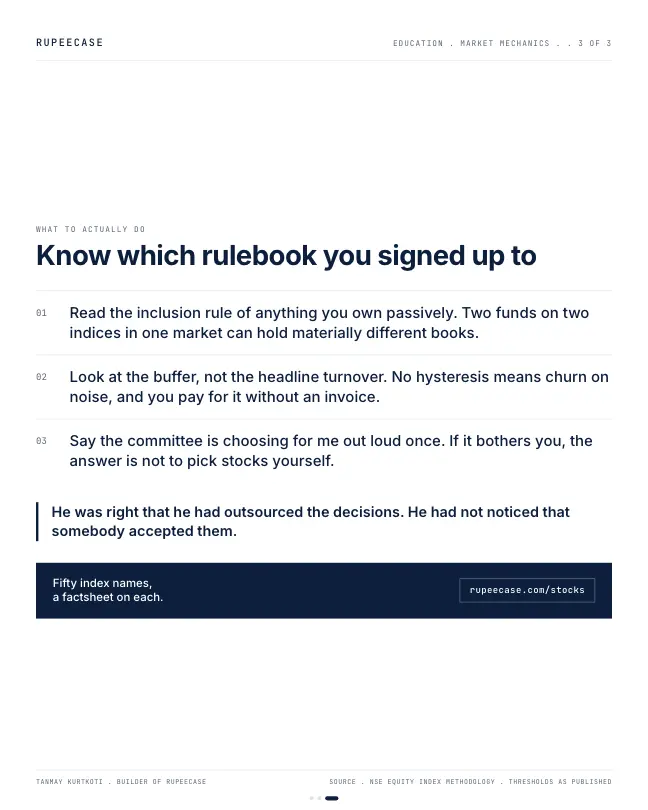
Read the inclusion rule of anything you own passively. Two funds tracking two indices in the same market can hold materially different books because one uses a top forty threshold and the other uses something else.
Look at the buffer, not the headline turnover. A methodology with no hysteresis will churn on noise, and every one of those churns is a cost you pay without seeing an invoice for it.
Say "the committee is choosing for me" out loud once. If that sentence bothers you, the answer is not to pick stocks yourself. It is to know which rulebook you signed up to, which is what reading the methodology of anything systematic is for.
My colleague was right that he had outsourced the decisions.
He had not noticed that somebody accepted them.
How to read any index you own
The same three questions work for any passive product, from a Nifty 50 fund to a sector index fund. What is the eligibility rule. How often is it applied, and with what notice. And what stops the weights from bunching. The answers sit in the index factsheet and methodology document, usually two pages, and they tell you more about what you own than the fund's own brochure.
The free Learn module on indices and benchmarks builds this from the ground up, and the note on why a 1 percent fee is not 1 percent shows what the low cost of an index buys over twenty five years.
Questions readers ask
How often does the Nifty 50 change its constituents?
NSE reviews the index twice a year, on six months of average data ending 31 January and 31 July, with four weeks notice before changes take effect. On the count in this post, that produced 41 changes between 2009 and 2022, about 2.93 a year.
Why is the Nifty 50 so concentrated if it holds fifty stocks?
It is weighted by free float market capitalisation, so the biggest companies get the biggest weights. On the NSE factsheet of 30 Sep 2026 the ten largest stocks were 52.27 percent of the index and financial services alone was 37.45 percent.
The cards
3 cards. Swipe, or tap to open.
Explore next
Learn it properly, then see it applied.
- Free module 6.3Mutual Funds, Structure, Types and Hidden Costs8 min read
- StrategyAllcap strategyNifty Total Market, 50 stocks, every 2 weeks
- Free module 1.3Indices & Benchmarks13 min read
- CalculatorTracking errorFree, with the formula and a worked example
- Blog topicCosts: MF, PMS, RupeeCase notes25 notes
Related
- A 1 percent fee does not cost you 1 percentOn Rs 10 lakh at 12 percent gross for 25 years a 1.00 percent fee costs 20.1 percent of the ending corpus, and more than half of that is charged in the last five years.Costs: MF, PMS, RupeeCase . . 13 min
- The Rs 1.25 lakh you throw away every yearRealising gains yearly in your own name beats deferring to exit up to about Rs 60 lakh of portfolio, because ten shots at the exemption are worth Rs 1,56,250 of tax.Costs: MF, PMS, RupeeCase . . 14 min
- The diversifier that concentratesFinancial services is 37.7 percent of the Nifty 50, so a sector fund that must hold 80 percent financials pushes a 30 percent sleeve past half the book in one sector.Costs: MF, PMS, RupeeCase . . 10 min
Educational content only. Figures are illustrative and computed on historical or representative data for teaching purposes, not investment advice. Past performance does not guarantee future returns. Sourced from NSE, BSE, SEBI, AMFI and RBI public data.